Mobile DRAM and Mobile NAND Flash latest market supply/demand update.
Global DRAM manufacturers are accelerating new fab construction and capital expenditures, with new capacity set to release in phases starting two years from now. As cleanrooms and equipment installations advance across major suppliers, large-scale capacity is expected to online progressively over the coming years, driving a structural expansion in industry supply. However, actual bit output remains subject to construction variables and product qualification timelines.
Strong CSP capex fuels steady AI server growth as cloud giants expand GPU rack orders and self-developed chip programs.
DRAM contract prices remain firm while spot activity stays subdued. Major suppliers are expanding capacity via new facilities, driving strong multi-year bit supply growth while dynamically adjusting output to sustain industry balance.
TrendForce Offers you a complete analysis on DRAM industry wafer input, production output, technology node…etc. by each company.
Consumer DRAM remains undersupplied, with contract prices still rising but decelerating as buyer cost tolerance tightens, while spot trading stays subdued. On technology, focus centers on open software frameworks and zHBM architectures aimed at improving system efficiency and power. Cloud demand supports near-term contract prices, but accelerating capacity expansion points to longer-term pressure on pricing and industry revenue.
Hyperscale CSPs ramp capex, fueling strong AI server growth as ODMs expand GPU rack output and cooling tech advances.
DRAM contracts delayed to Aug. Spot market flat on low volume. CSP demand boosts Korean Q2 results and LTA signings.
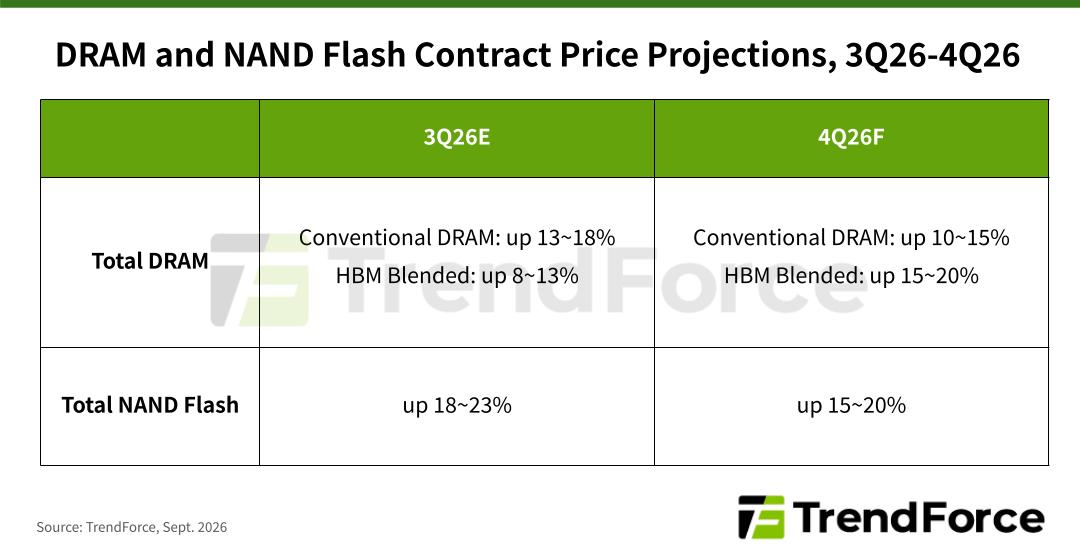
With mobile DRAM inventory restocking largely completed and demand starting to soften, the urgency of procurement negotiations has diminished, and 3Q26 contract price settlements are likely to be pushed back further. On the pricing front, Samsung’s hikes have clearly moderated this quarter, as its previous quotes were already at elevated levels; by contrast, if SK hynix and CXMT aim to close the pricing gap, their increases will appear relatively more pronounced. TrendForce projects that the overall quarterly hike will narrow from last quarter to around 8-13% QoQ.
Looking ahead to 4Q26, under the combined pressure of weak end demand and elevated inventory levels, price increases are expected to further converge. However, the ongoing trend of suppliers shifting capacity toward server and HBM applications will remain intact, providing key support for keeping quarterly contract prices from falling back.
Server DRAM contract prices are trending upward. Supply shortages and HBM crowding effects strengthen vendor pricing power. High-capacity module premiums are narrowing due to stable yields and demand shifts. Despite temporarily rising inventory levels, long-term market tightness is expected to intensify as processor supply recovers.
Research Areas:
Industry News