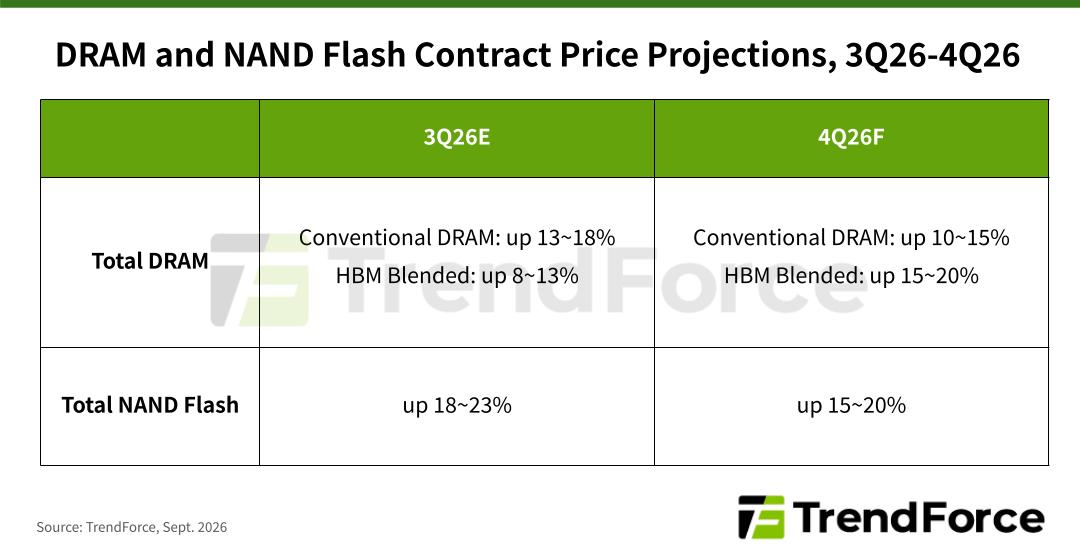
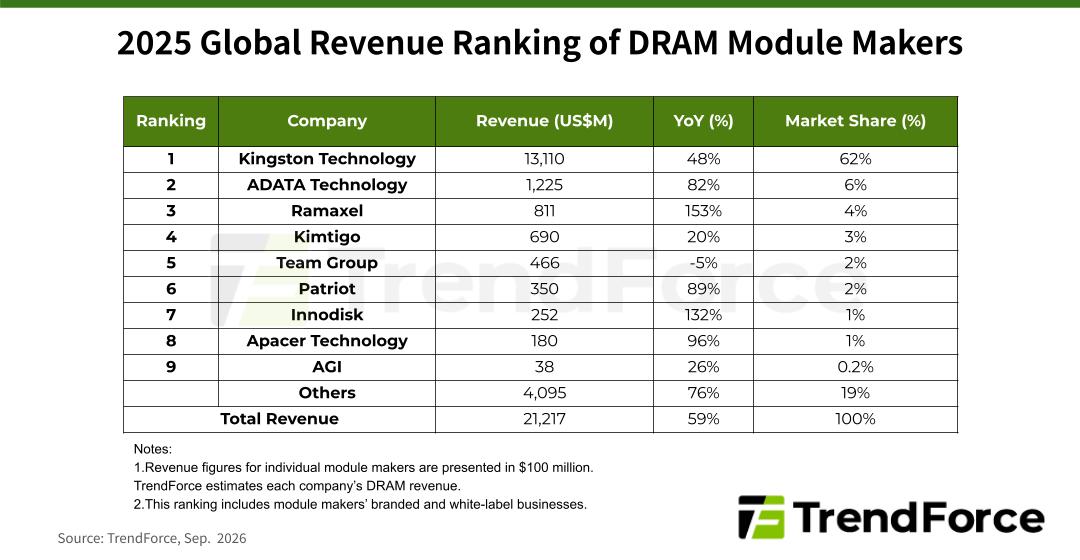
Driven by the AI wave, demand for high-capacity memory continues to surge, powering strong industry revenue growth and contract price hikes. Although top suppliers are accelerating advanced process transitions and expanding new facilities, supply expansion still trails robust demand. Elevated prices significantly boost profit margins, while Taiwanese makers also benefit by filling maturity-process supply gaps.
Hyperscaler capex stays strong, lifting AI server growth, while tight supply now shapes shipment pace.
New CEO Ternus leads Apple's first foldable launch; modest specs upgrade amid surging memory costs puts pricing and AI delivery at center stage.
PC DRAM contract prices saw their quarterly increase revised upward, while spot transactions stayed subdued. HBM negotiations remain deadlocked with specifications still in flux, yet prices retain strong upside. Ahead, HBM shifts from a single-spec race toward customization, layering, and simplified packaging.
Server DRAM prices rise due to strong demand and HBM capacity crowding out. Buyers shift to mid-to-low capacity modules to optimize costs, while high-capacity stock flows to OEMs, helping suppliers maintain low inventory and strong pricing power. High-capacity premiums narrow as suppliers hike lower-capacity prices. Meanwhile, lower HBM stack specs may boost long-term bit supply.
Quarterly Server DRAM latest market revenue/output update
The supply gap in consumer DRAM persists, keeping prices on a slight upward trend. However, as buyer cost tolerance reaches its limit, contract price growth is moderating. With suppliers locking in most capacity through long-term agreements (LTAs) and surging demand for enterprise SSDs crowding out standard consumer applications, this structural market tightness is expected to extend over the next couple of years.
Rising memory costs triggered premature purchases as consumers sought to beat price hikes, driving a short-term rebound in smartphone production and prompting TrendForce to revise its full-year output forecast upward. However, this momentum reflects front-loaded demand rather than a genuine market recovery. As persistent cost pressures trickle down to end-user pricing, entry-level models are set to disappear, leaving the market vulnerable to structural contraction risks ahead.
Rising chipmaker quotes and modest shipment recovery drive PC DRAM contract price increases. Facing future supply contraction, OEMs aggressively build inventory while adopting component downgrades to manage costs. Meanwhile, spot prices remain firm, prompting vendors to initiate long-term agreements for market visibility.
Mobile DRAM revenue surged sharply in 2Q26; four vendors dominate. Growth will moderate in 3Q26 as price gains slow.
Research Areas:
Industry News