TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
CSP capex growth lifts server and AI shipments, chip forecasts rise, ODMs shift to racks, cooling gains traction.

Driven by AI infrastructure, server storage demand surges, prompting manufacturers to shift capacity and advanced nodes. Conversely, consumer electronics languish due to high costs, inflation, and sup...
AI chip demand surges in 2026, with high-end GPUs dominating. NVIDIA leads, ASICs gain share, liquid cooling expands, and AI server value hits record highs.
Photonic packaging drives AI infra, shifting to mass production. CPO and glass platforms solve bottlenecks.
Driven by AI server demand, 3Q26 memory contract prices continue to rise. However, due to high baselines and consumer cost limits, overall price growth will decelerate.

Analyst View: Anticipating future supply shortages, buyers are actively replenishing server memory inventories, boosting suppliers' pricing power. Although long-term agreement price caps limit av...
TrendForce combines its expertise in the Foundry/Server industry and leverages it with the supply chain to accurately estimate AI chip shipments, AI Server application ratios, AI major suppliers&a...
TrendForce combines its expertise in memory market and leverage it to provide a multi-faceted study of server market in this report. The content of it is as follows: 1. Server CPU Market: State of Co...
AI drives data centers from air to liquid cooling. Vendors deploy high-density power and tech, boosting growth.

Diverging HBM4 certification timelines are reshaping 2026 market share, with Samsung gaining ground as SK hynix faces delays.
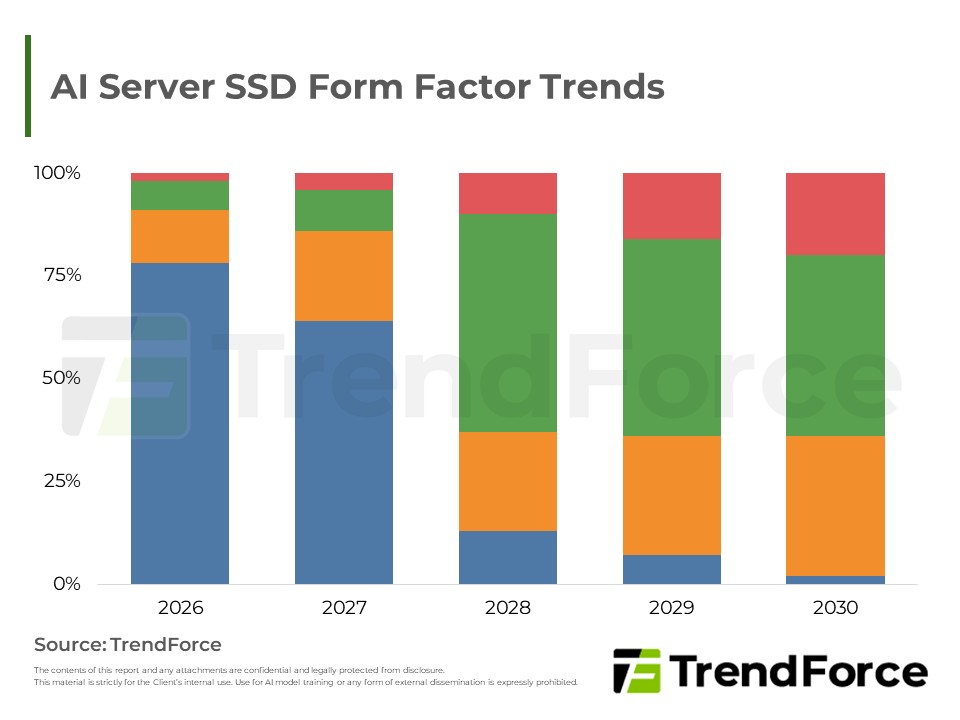
As AI power and heat surge, legacy storage faces thermal bottlenecks. Giants driving thin, blade-like form factors to optimize airflow and surface area. While legacy builds dominate short-term due to...
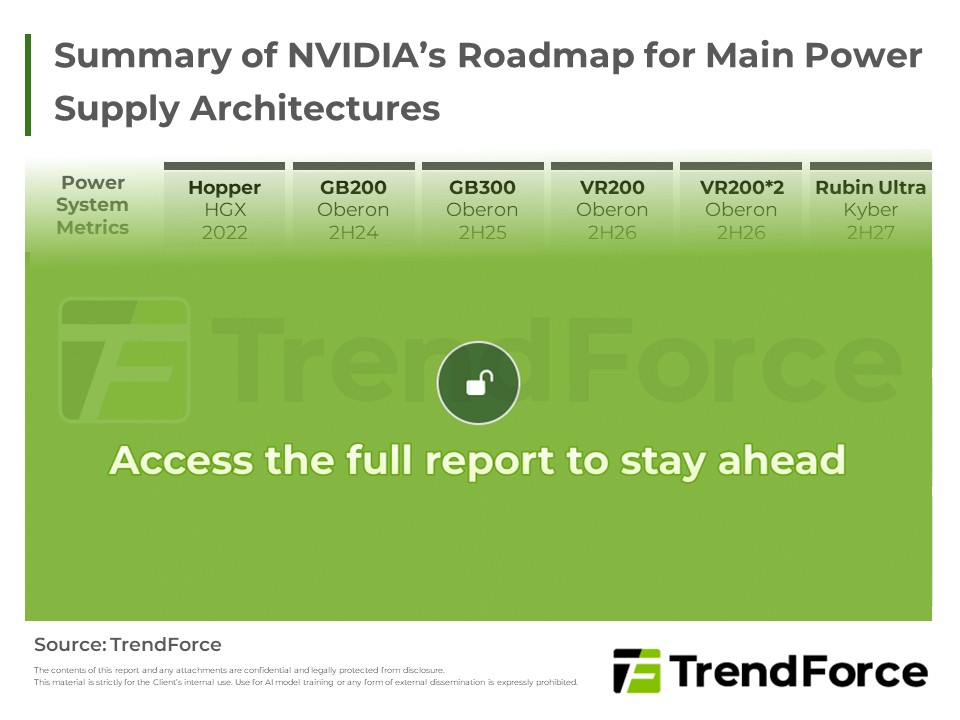
NVIDIA advances its 800V Power Rack roadmap, with mass adoption expected from Rubin Ultra onward, while North American data center buildouts face delays from grid and equipment constraints.
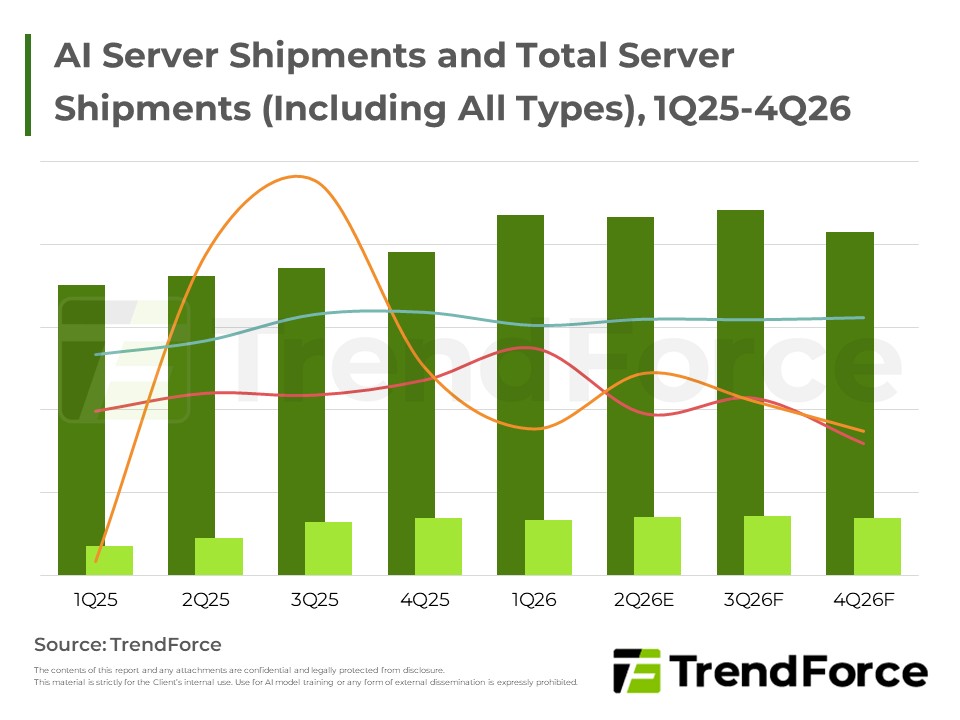
Global server growth accelerates in 2026 as CSPs expand AI infrastructure investment and custom silicon adoption reshapes procurement strategies.
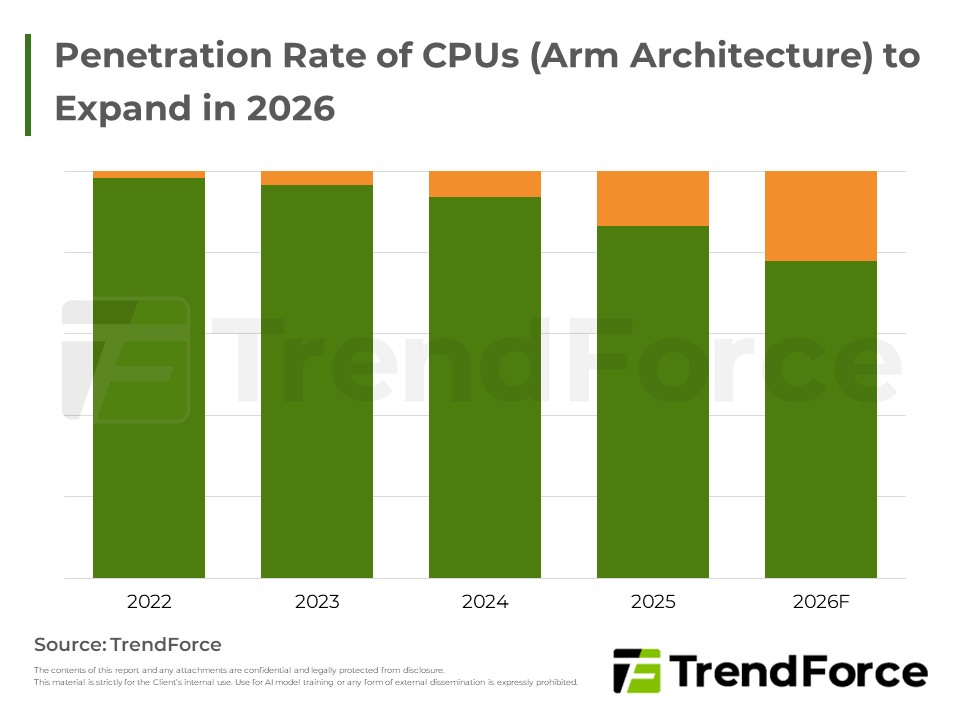
As AI shifts from training to inference and agentic workloads, Server CPU evolves from auxiliary to core orchestrator, lifting both ARM and x86 demand into a new growth cycle.
The year 2026 marks the watershed transition of AI data center optical interconnects from adoption to mass production. The actual volume driver is not scale-out CPO switches, but GPU scale-up networks...


