TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
Driven by AI server demand, 3Q26 memory contract prices continue to rise. However, due to high baselines and consumer cost limits, overall price growth will decelerate.

Analyst View: Anticipating future supply shortages, buyers are actively replenishing server memory inventories, boosting suppliers' pricing power. Although long-term agreement price caps limit av...
AI drives data centers from air to liquid cooling. Vendors deploy high-density power and tech, boosting growth.

Diverging HBM4 certification timelines are reshaping 2026 market share, with Samsung gaining ground as SK hynix faces delays.
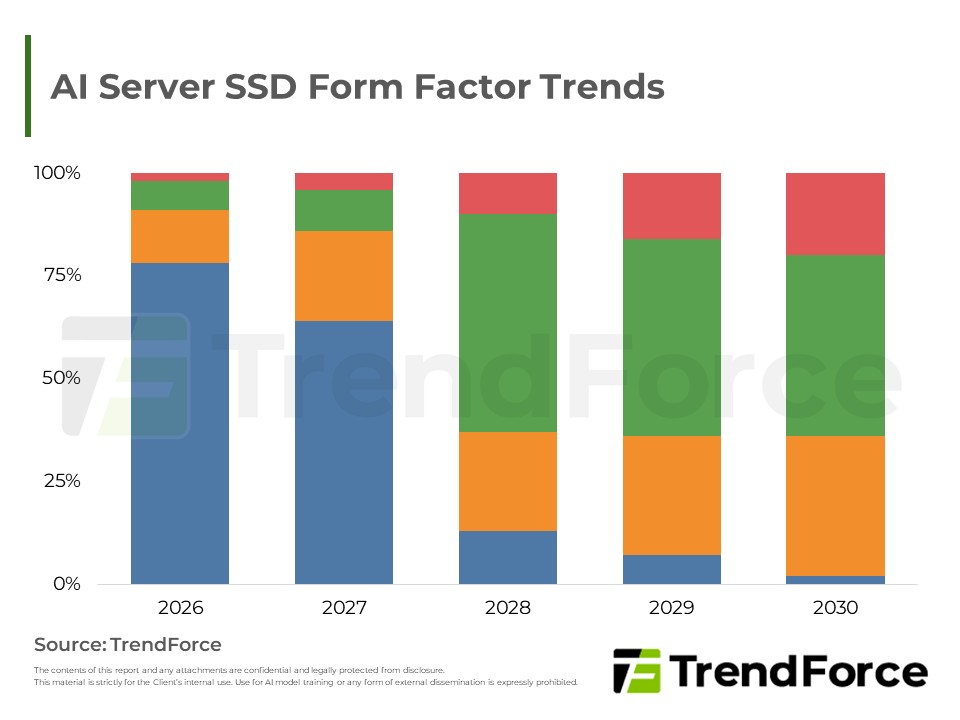
As AI power and heat surge, legacy storage faces thermal bottlenecks. Giants driving thin, blade-like form factors to optimize airflow and surface area. While legacy builds dominate short-term due to...
NVIDIA advances its 800V Power Rack roadmap, with mass adoption expected from Rubin Ultra onward, while North American data center buildouts face delays from grid and equipment constraints.
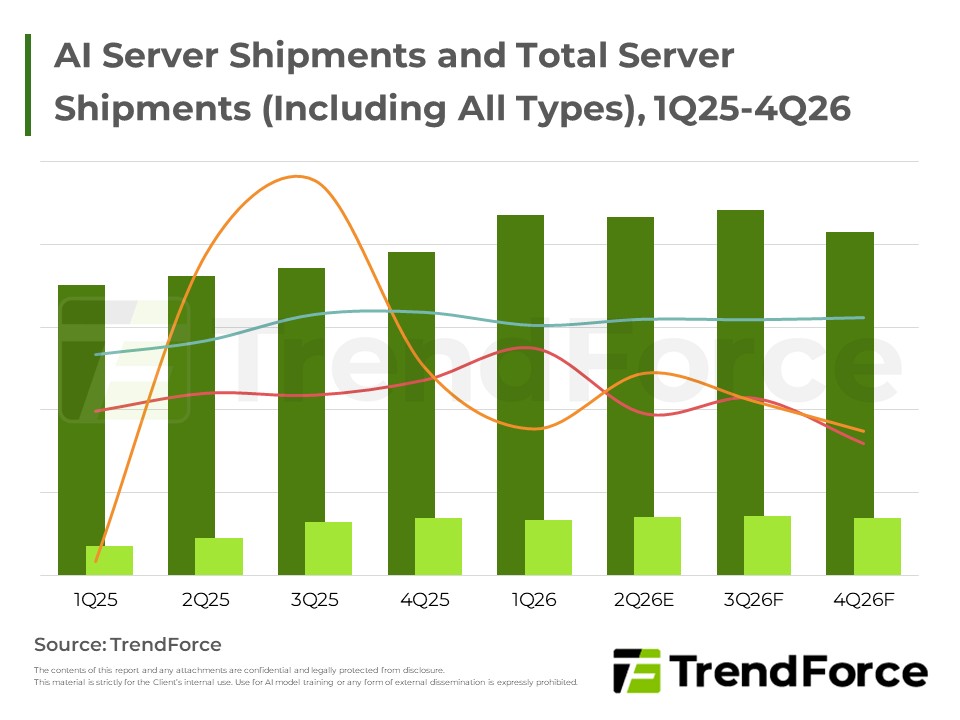
Global server growth accelerates in 2026 as CSPs expand AI infrastructure investment and custom silicon adoption reshapes procurement strategies.
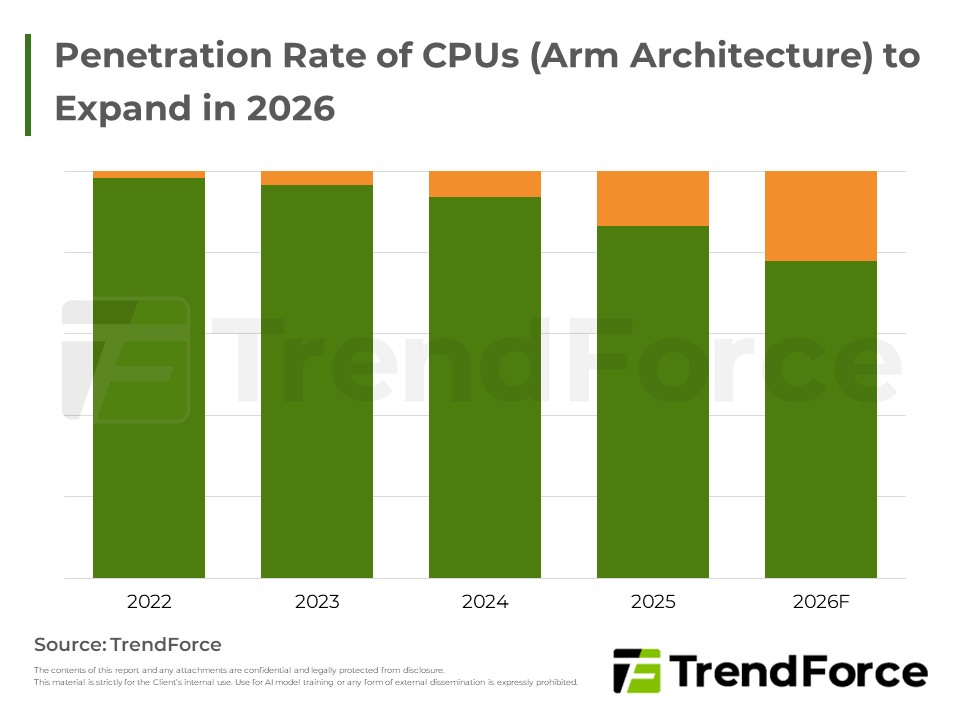
As AI shifts from training to inference and agentic workloads, Server CPU evolves from auxiliary to core orchestrator, lifting both ARM and x86 demand into a new growth cycle.
The year 2026 marks the watershed transition of AI data center optical interconnects from adoption to mass production. The actual volume driver is not scale-out CPO switches, but GPU scale-up networks...
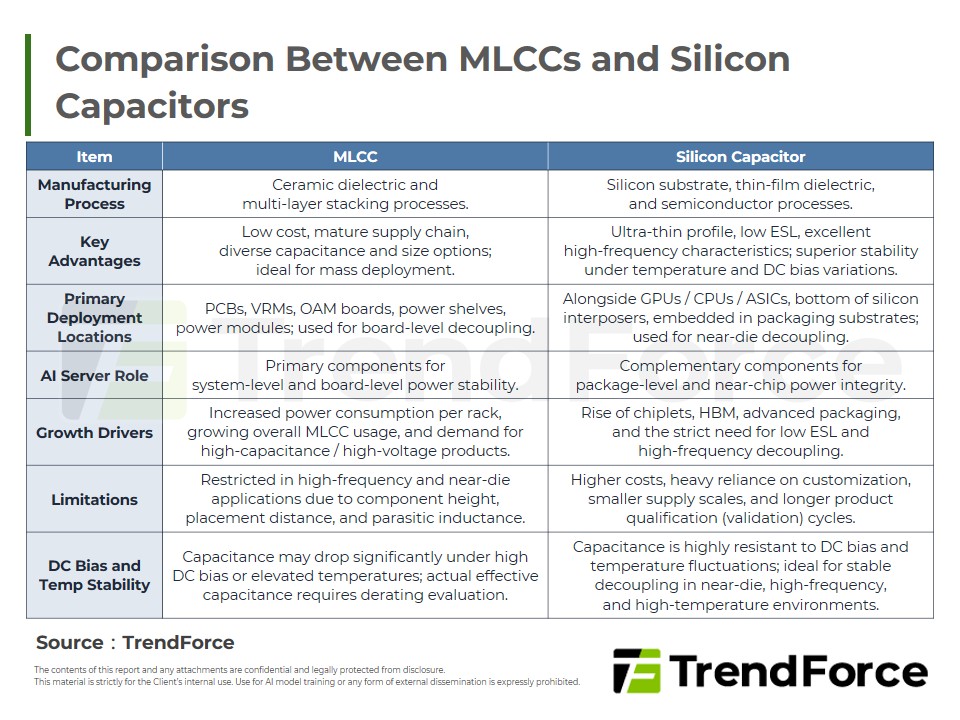
The need for power integrity in AI servers is extending from the board level directly into the package. This shift is driving a transition in capacitor technology, moving beyond a sole reliance on tra...
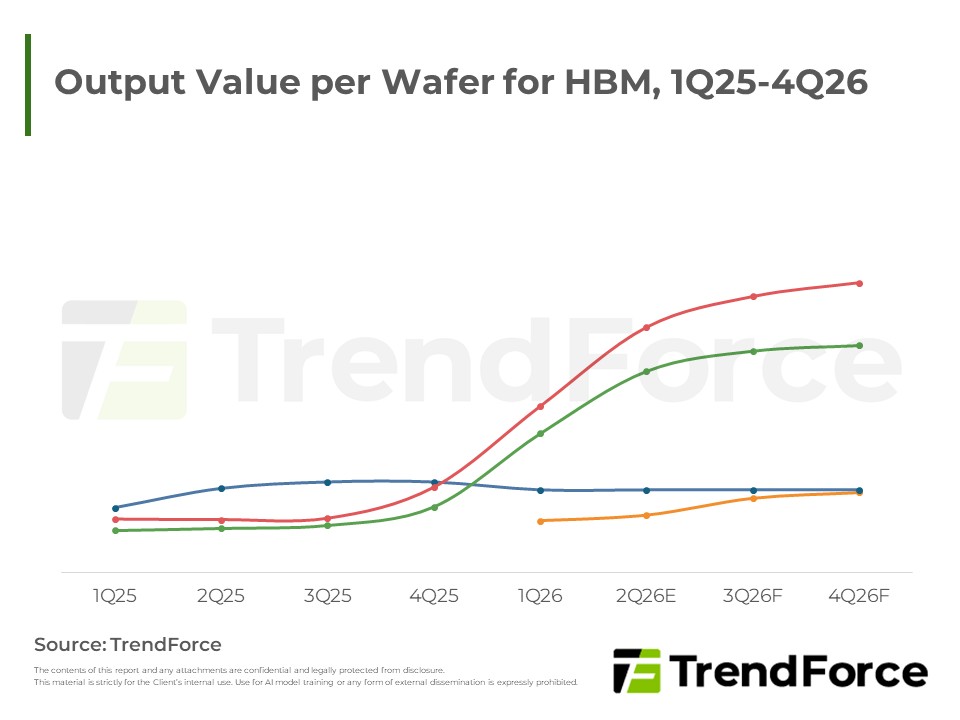
HBM 2027 supply talks remain unresolved as suppliers push for steep price hikes; NVIDIA's SOCAMM adjustment reflects supply constraints, not demand reduction.
AI demand and proprietary chip adoption drive upward revisions in global server shipments. Despite supply bottlenecks, memory face severe shortages and soaring prices. AMD and alternative architecture...
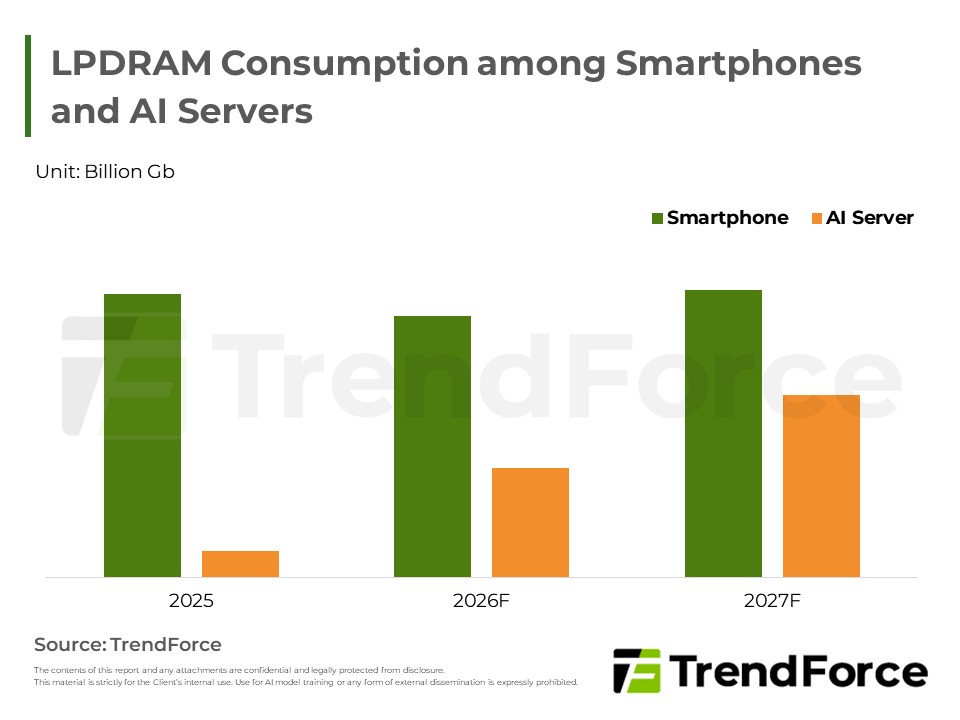
Beyond full-rack solutions, NVIDIA is also actively promoting its standalone Vera CPU to capture the AI inference market. However, given the LPDRAM supply bottleneck, NVIDIA has decided to reduce the...
Driven by agentic AI applications, the server DRAM market experienced explosive growth. The need for models to handle complex computations and offload long contexts has led to a severe shortage of key...
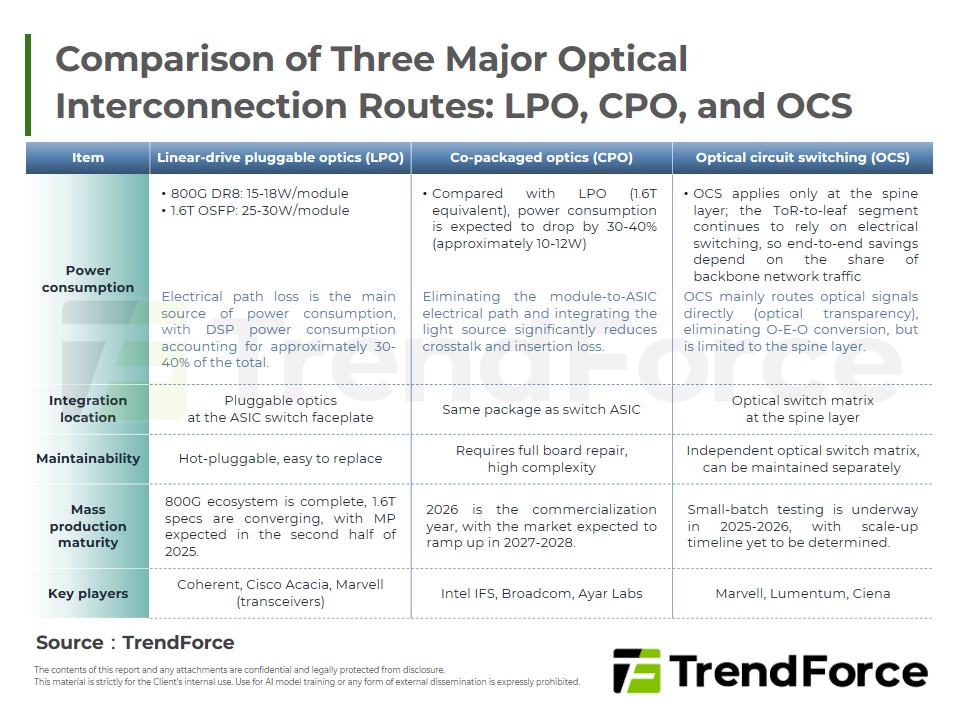
Co-packaged optical (CPO) technology is entering the commercialization stage, driven by AI data center demand for higher bandwidth and lower power consumption. Volume production begins in 2026, with l...


