TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
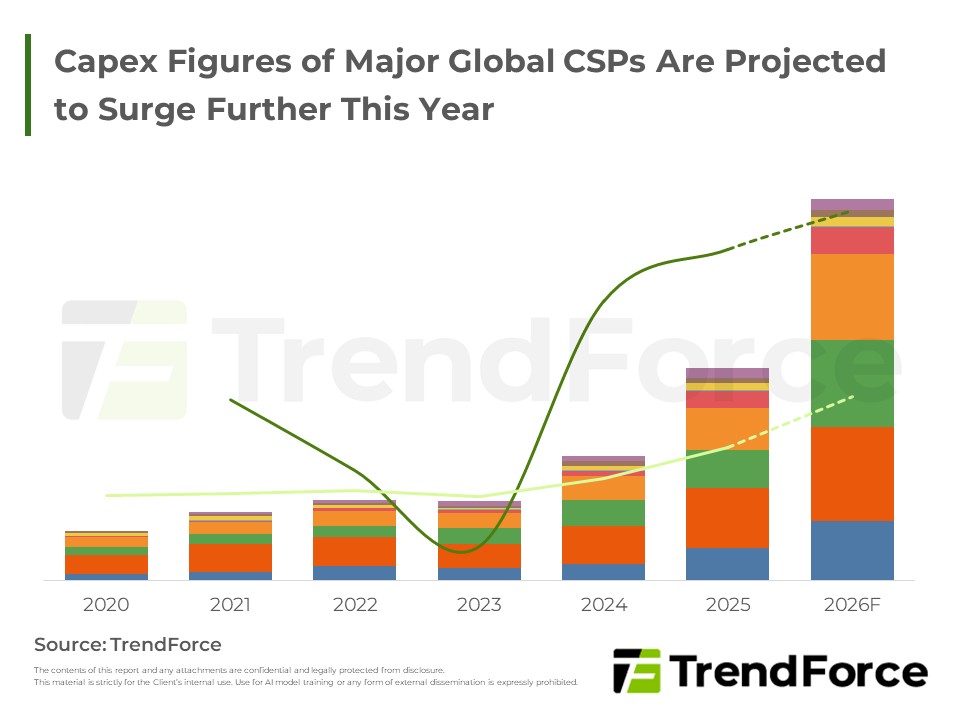
NA CSPs raised Capex sharply, cementing AI infra as core strategy and powering AI server and data center growth.
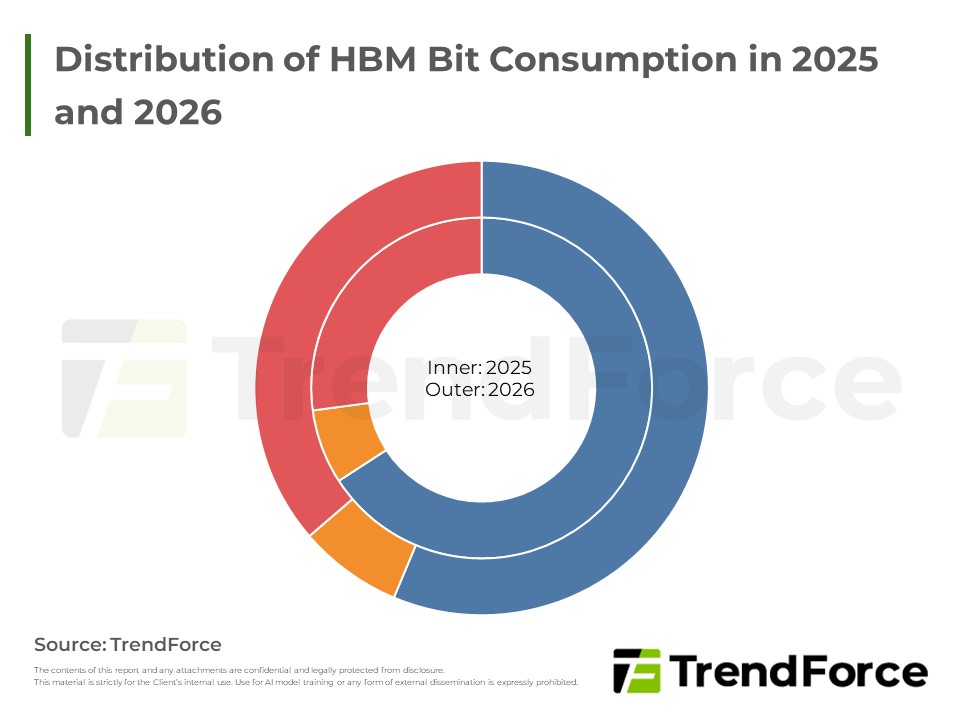
HBM grows strongly in 2026 as CSP/ASIC demand lifts HBM3e prices; SK hynix leads, Samsung rebounds, Micron expands TSV.

Driven by supply shortages and bottoming supplier inventories, server memory makers now hold absolute pricing power, leading to continuous and substantial upward revisions in contract prices. Although...
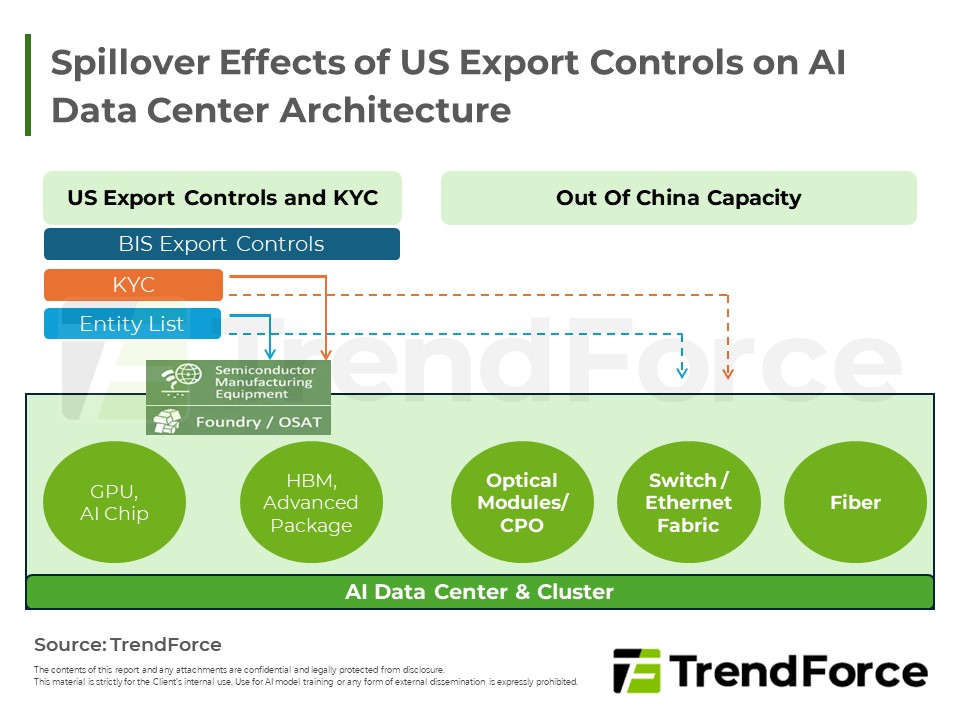
As U.S. export controls extend from chips to AI infrastructure, the traditional optical interconnect industry is undergoing supply chain restructuring. While optical modules are not subject to blanket...
Global Server Market – Trends and Outlook for 2Q26
Driven by the artificial intelligence boom, soaring enterprise storage demand caused suppliers to heavily shift capacity, triggering severe consumer memory shortages and doubling prices. However, with...
Global CSPs expand AI infrastructure investment, with Google and Microsoft leading on TPU and GPU racks while Chinese peers diversify amid geopolitical constraints.

Memory pricing hits a historic inflection as server DDR5 profitability overtakes HBM; CSP long-term contracts lock in floors, signaling a sustained upward pricing trend into 2027.
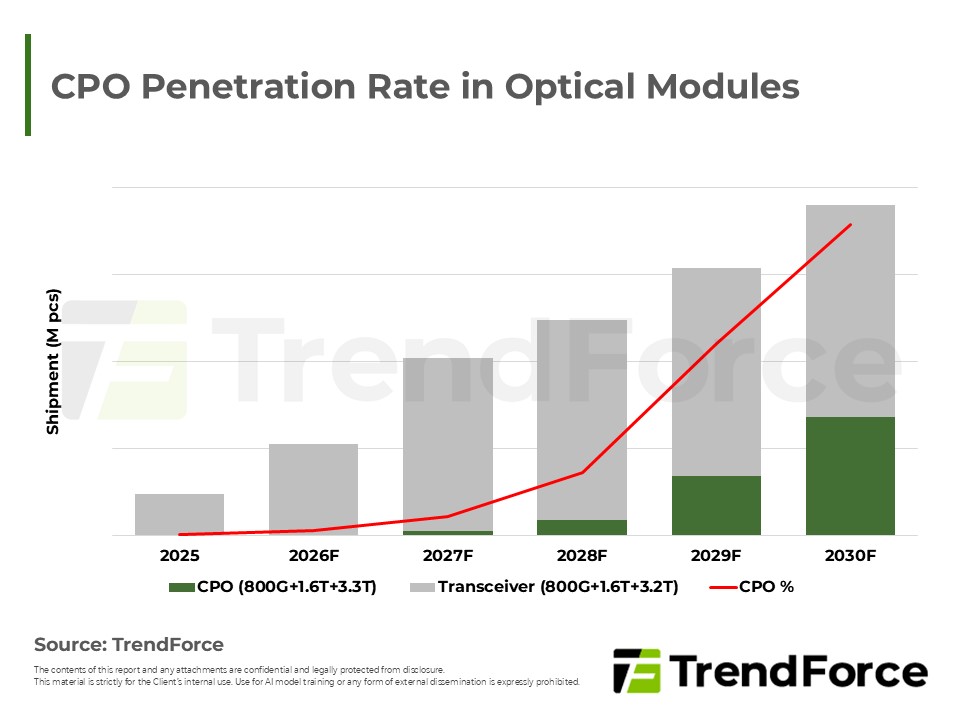
NVIDIA shifts AI competition from computing performance to system interconnects, leveraging CPO and silicon photonics to break I/O bottlenecks. By integrating high-speed fabric with advanced packaging...
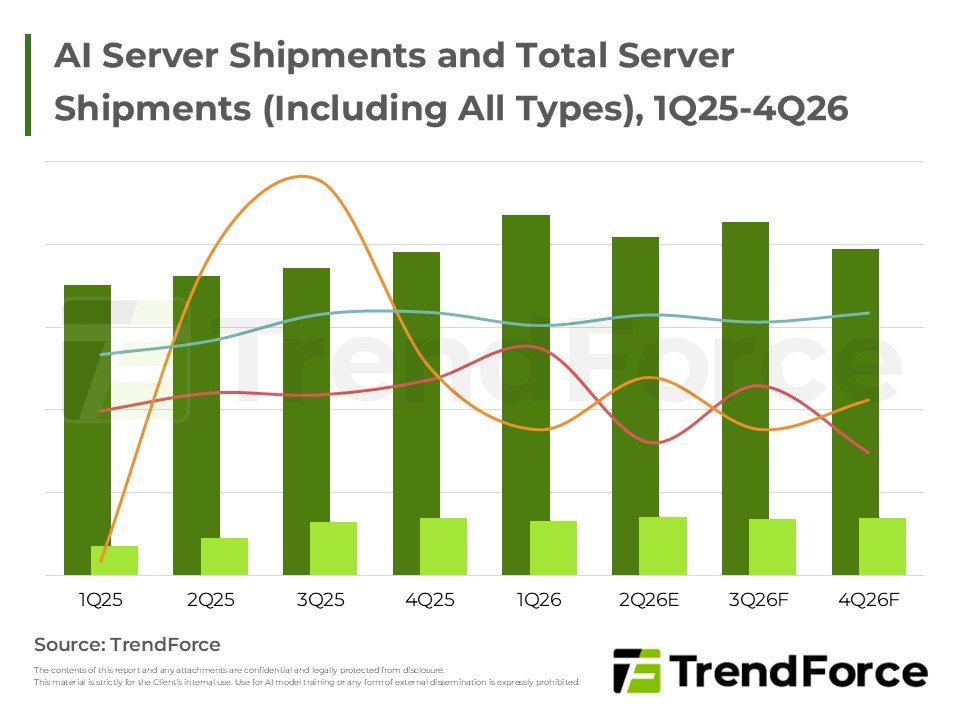
AI server demand stays robust with GB leading H1; Rubin ramps in Q3. ASIC share dips slightly as GPU dominates. Component shortages cap general server growth. Liquid cooling competition intensifies.
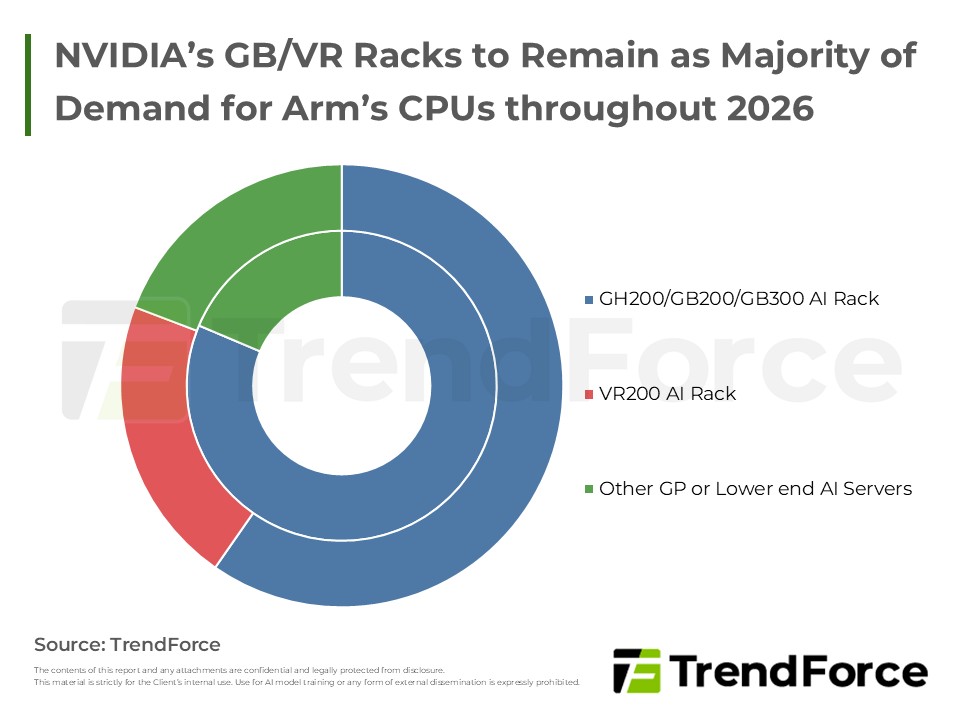
Arm's AGI CPU marks a strategic shift from IP licensor to platform provider, targeting AI data centers and accelerating Arm's gains against x86.
Driven by AI and general servers, industry value grows robustly. Despite geopolitical risks and custom chip delays, NVIDIA and AMD's push for premium integrated racks significantly boosts average pric...
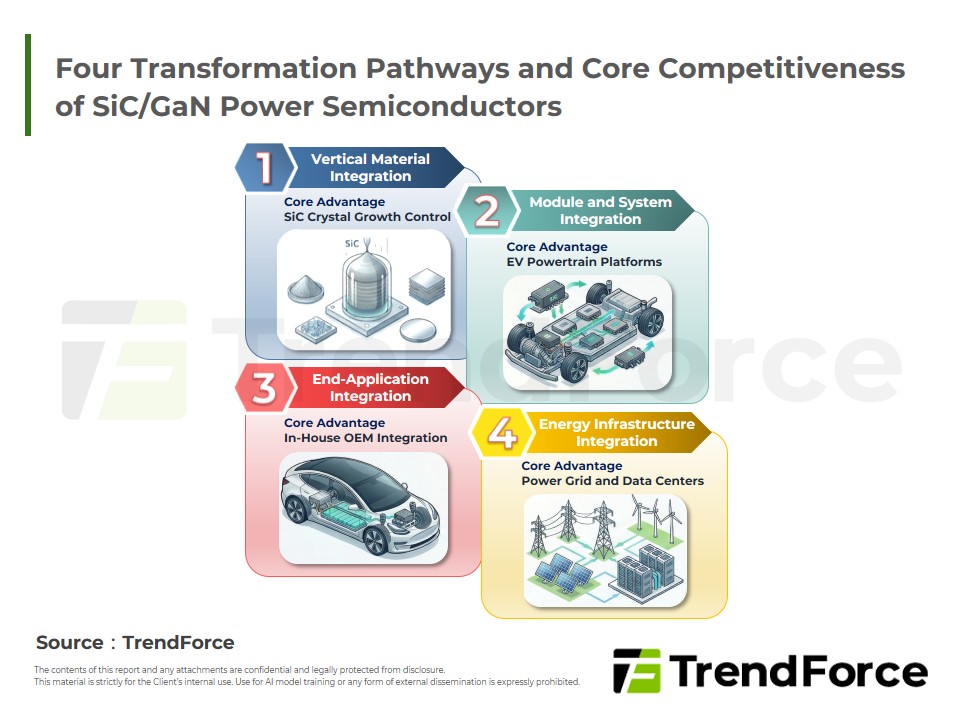
In 2026, power semiconductors have evolved from conventional components into strategic enablers reshaping the global energy landscape. SiC and GaN technologies are entering a phase of large-scale depl...

Server DRAM prices surge on tight supply but future hikes will ease. Buyers globally rush to secure long-term contracts.
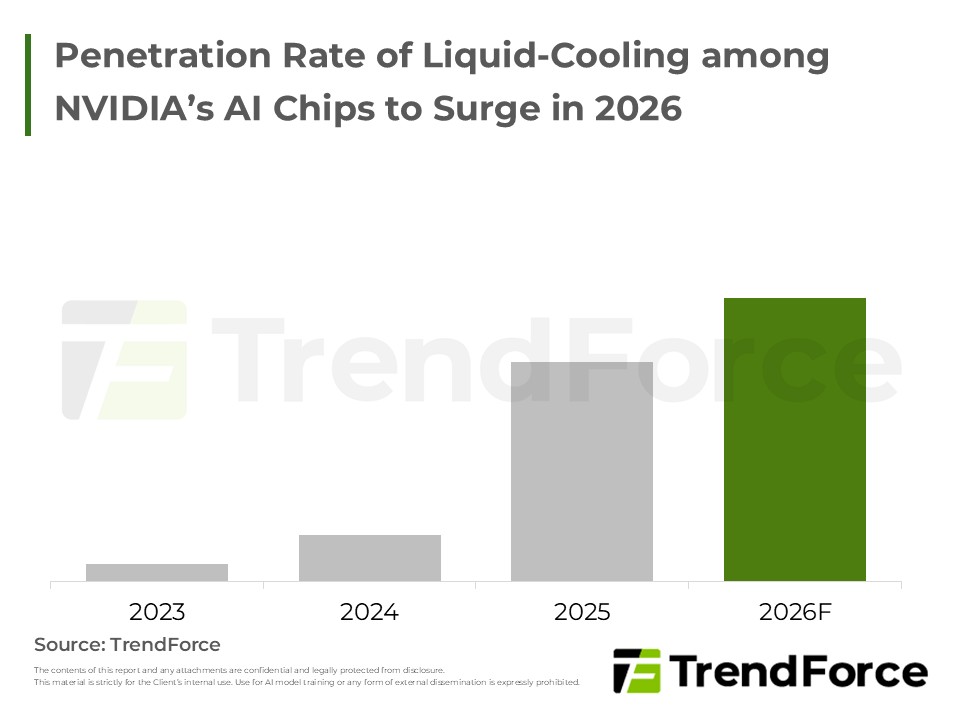
Rapid AI factory scaling is reshaping data center infrastructure. In the near term, independent power racks stabilize power delivery, while the mid-to-long-term roadmap points to centralized HVDC dist...


