TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
AI drives huge server memory demand. Depleted inventory sparks surging prices. Custom chips disrupt processor markets.
TurboQuant breaks language model memory bottlenecks via lossless dimensional compression, drastically boosting efficiency. Plummeting costs spark massive long-sequence application demand, comprehensiv...
AI data centers are undergoing structural upgrades, with HVDC and independent power racks becoming the standard. As power density exceeds critical thresholds, demand for liquid cooling and power suppl...
AI demand shifts memory capacity to enterprise products. Severe shortages will drive continuous contract price hikes.
AI demand and surging prices boosted server DRAM revenue. Buyer stockpiling depleted inventory, fueling an upcycle.

NVIDIA's upgraded HBM4 specifications have delayed supplier validations. Samsung, leading in chip performance, is poised to complete certification first and increase market share, while competitors re...
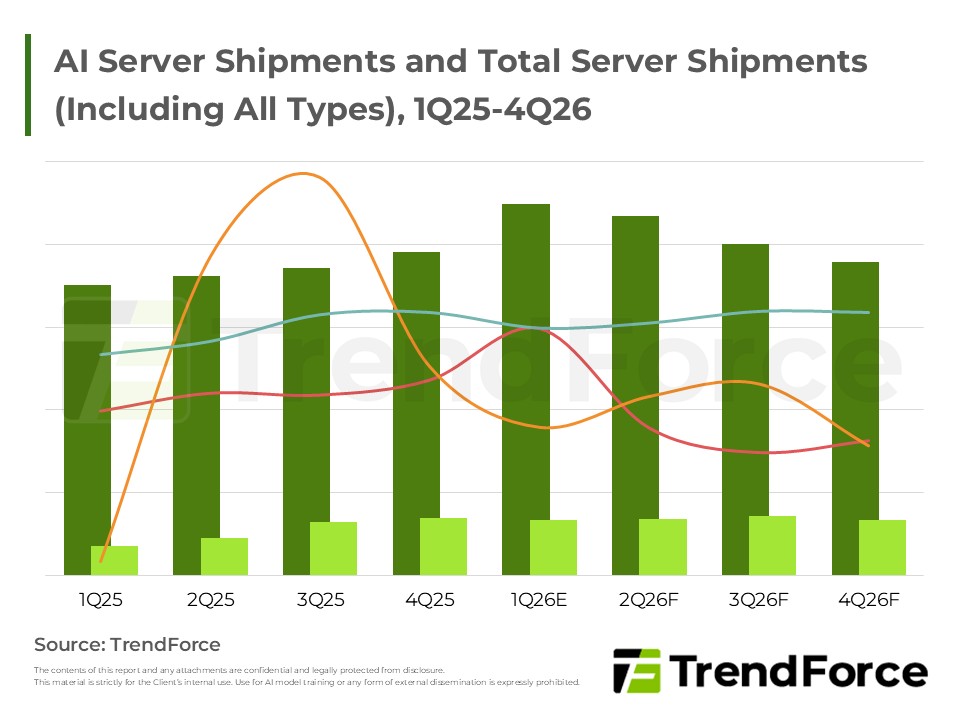
Cloud giants are drastically expanding Capex for AI infrastructure, driving explosive demand for GPU/ASIC racks. However, immense computing demand faces structural component shortages. Meanwhile, OEMs...
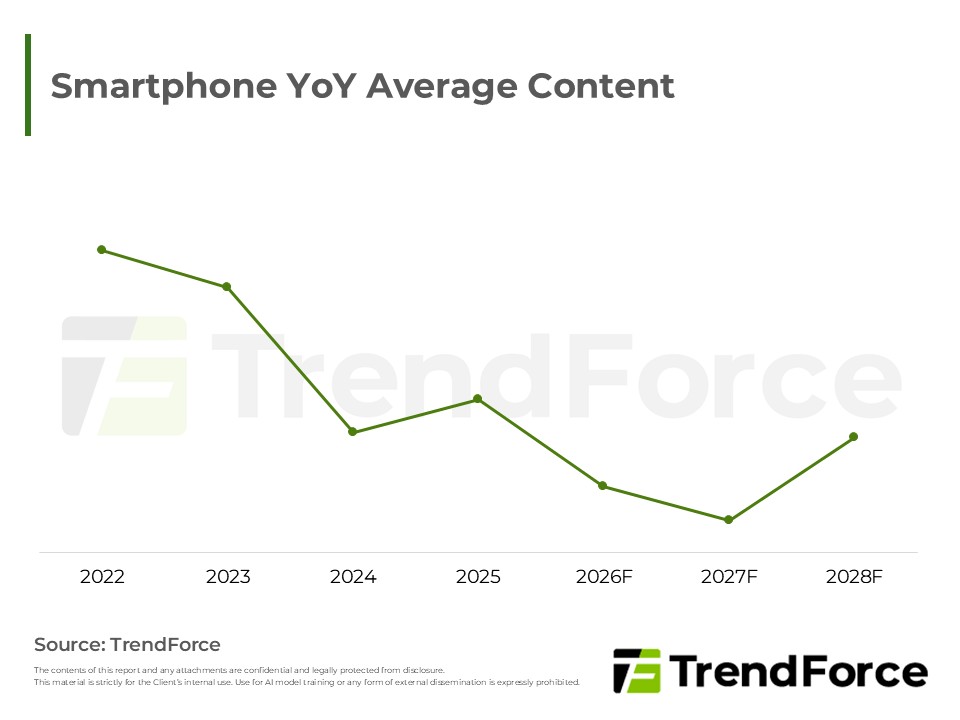
AI demands and chip upgrades drive smartphone storage growth despite high costs. Brands raise base specs, making large capacities the new standard.
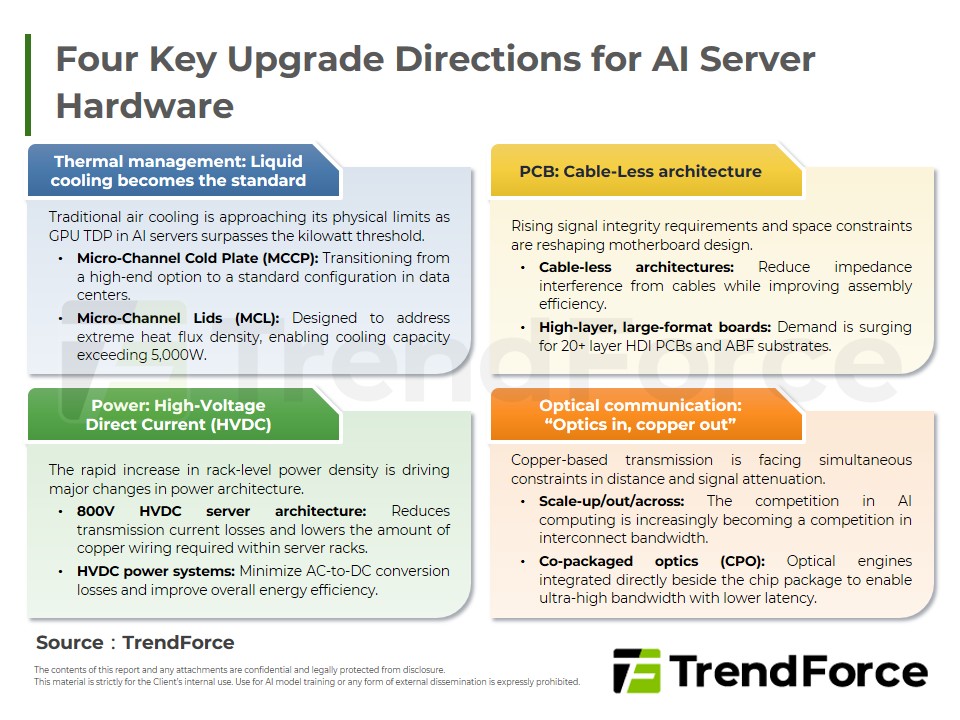
As data centers adopt HVDC architectures to reduce grid-to-chip power losses, demand for advanced power conversion and next-gen semiconductors surges. Meanwhile, Asian manufacturers continue to domina...
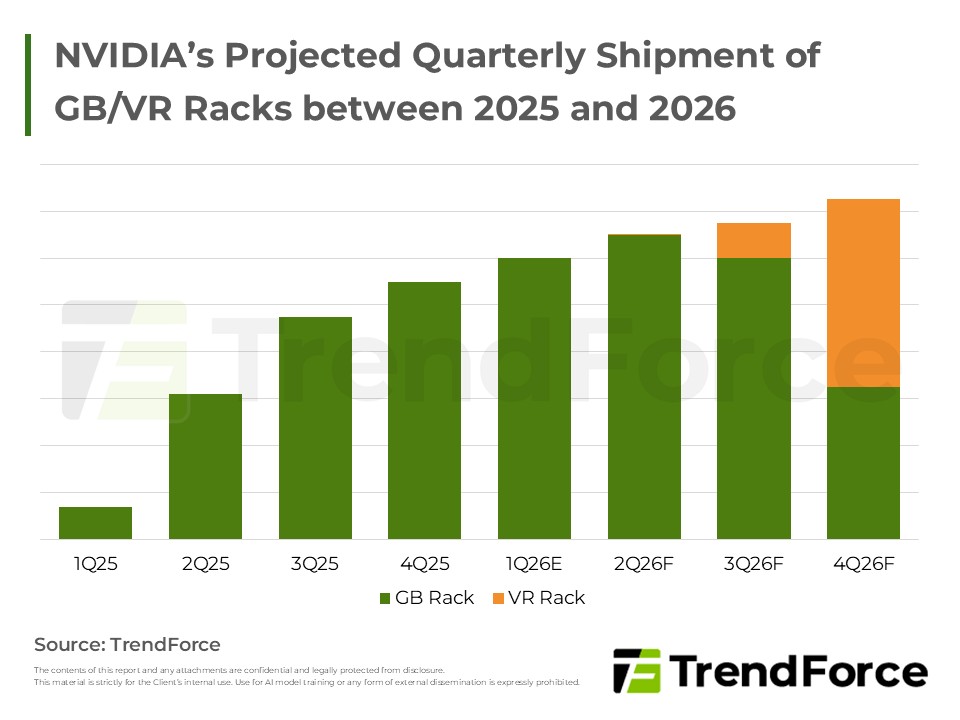
NVIDIA expands its AI factory via integrated GPU, CPU, and LPU racks for training and inference, securing its market lead.

NVIDIA's strategic investment in Lumentum and Coherent secures critical InP laser and high‑power CW light‑source capacity, shifting supply‑chain focus from module assembly to upstream optical componen...
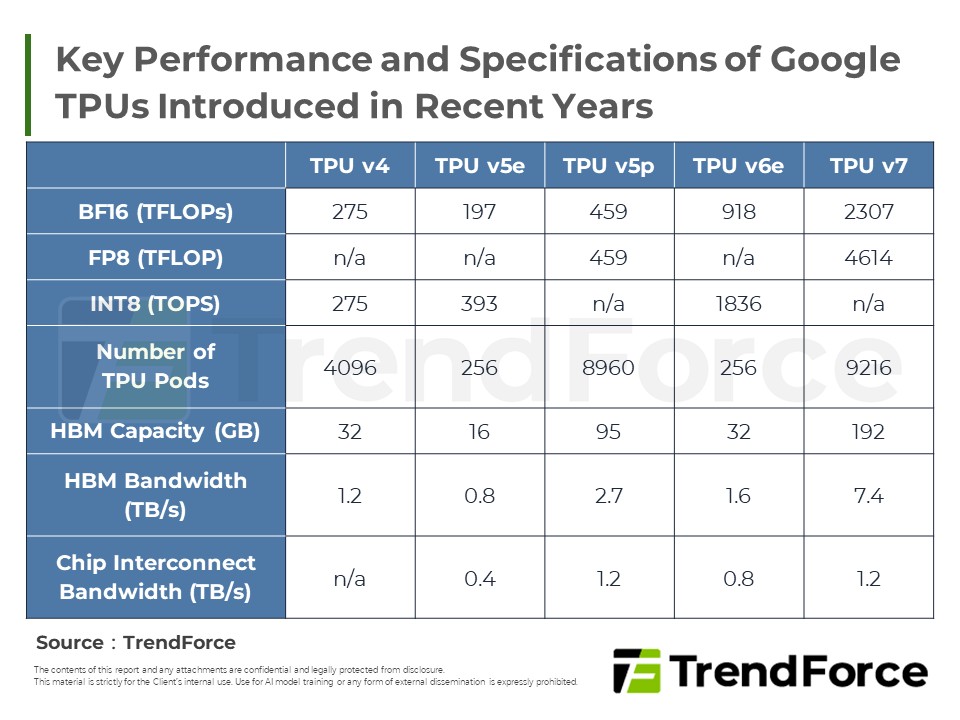
AI chips represent the core cost component of computing infrastructure. Recently, reports that Google’s TPU has been adopted by several leading companies have drawn attention to the possibility of mor...

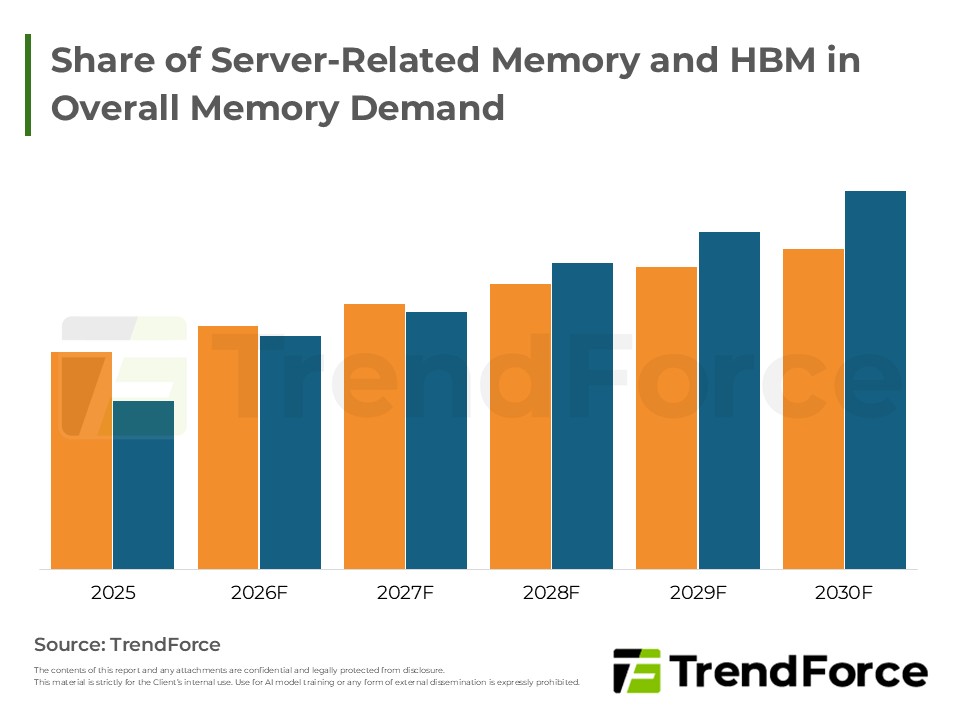
CSPs' AI push fuels HBM shortages and price hikes. Strong conventional DRAM dilutes HBM share; base die production shifts to TSMC.

North American CSP CAPEX expansion drives dual demand for NVIDIA and custom chips. ODMs like Foxconn benefit from rack solutions and are expanding US/Mexico production. Power leaders Delta and LiteOn...
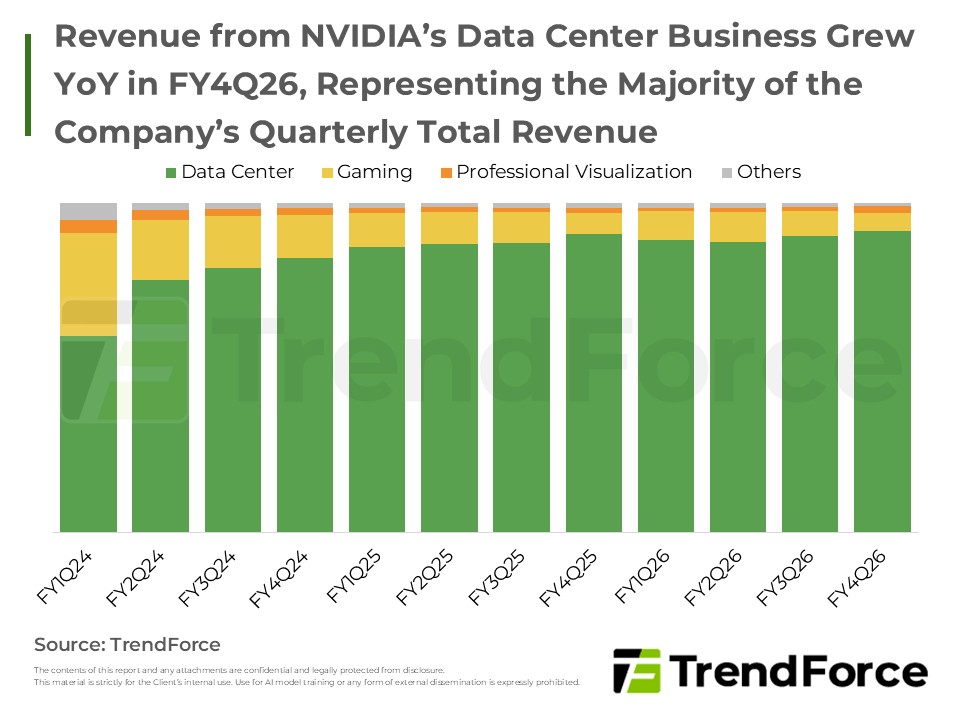
NVIDIA achieved record revenue driven by cloud AI and data center dominance. North American CSPs lead demand, establishing the GB series as mainstream and accelerating liquid cooling. However, HBM4 de...


