TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
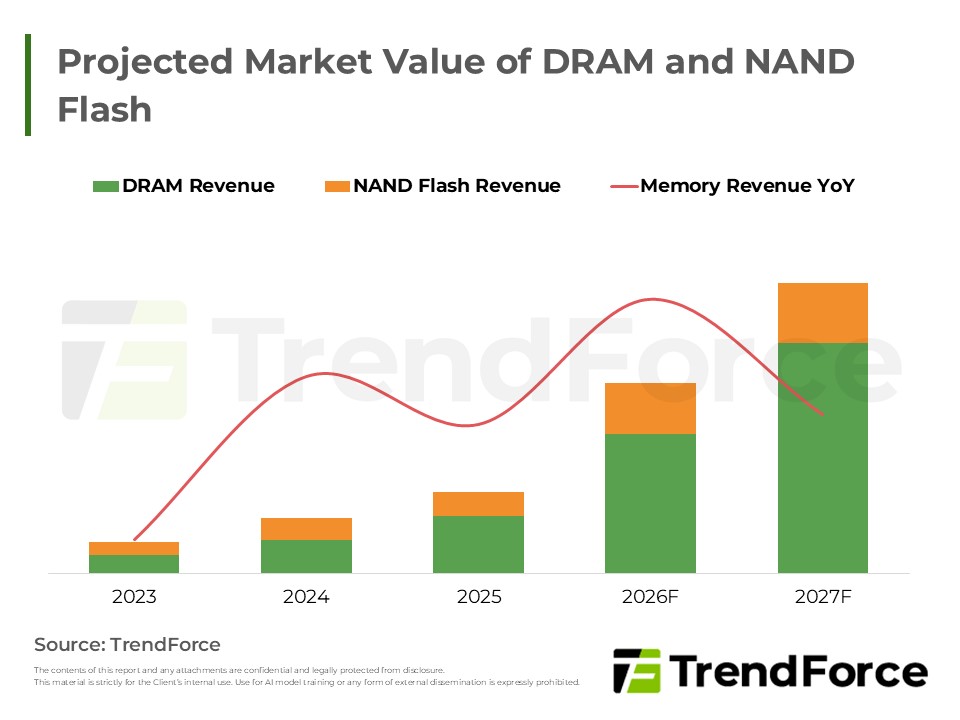
AI infrastructure upgrades are driving structural memory demand, making DRAM and NAND Flash critical resources. Heavy CSP investment is pushing prices and revenue to record highs. With persistent shor...
Driven by robust Server and AI demand, the displacement of DDR5 capacity has triggered price surges. HBM3e prices are poised to rise due to increased orders and specification upgrades, strengthening s...
Despite market headwinds, strategic pivots and supply chain optimization successfully offset revenue pressure. Cost controls significantly improved margins. With continued R&D investment strengthening...
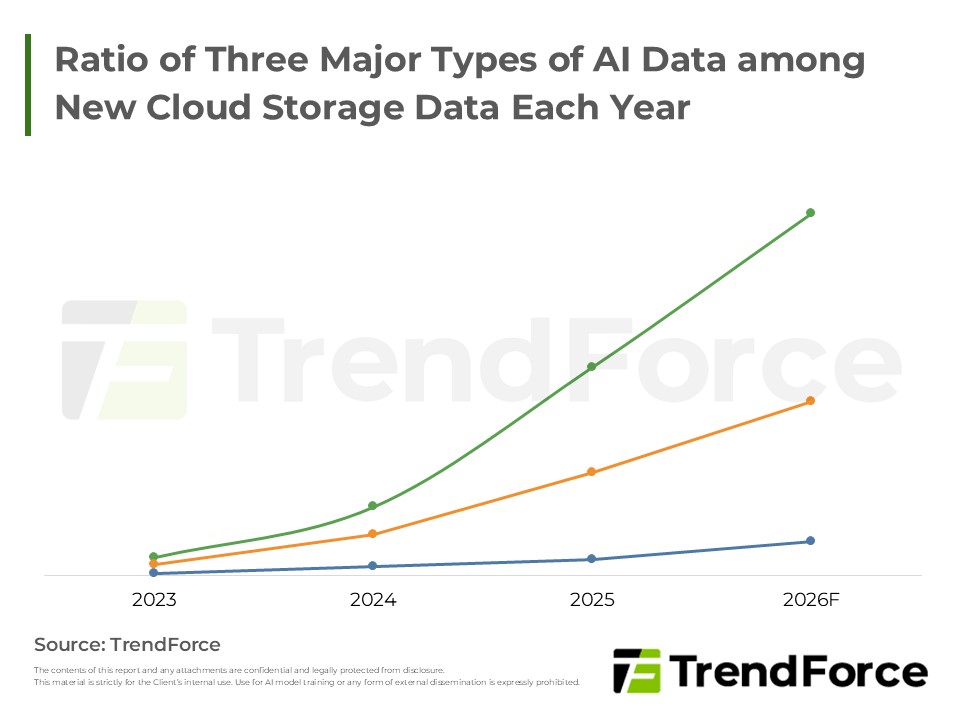
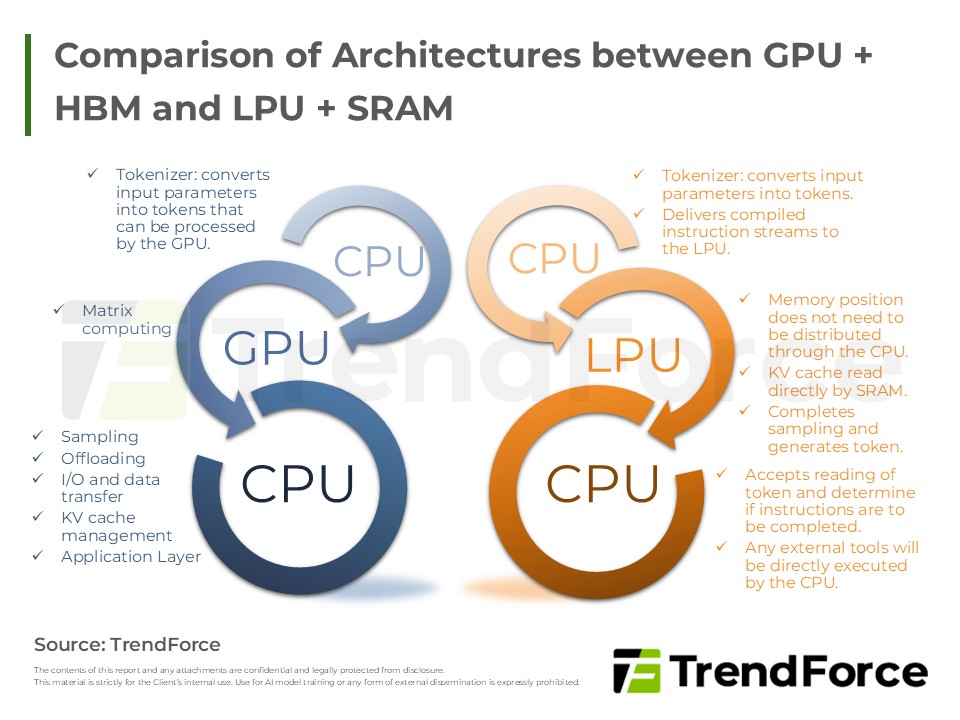
AIGC mass adoption drives AI Agent and inference demand. NVIDIA's BlueField-4 platform optimizes network architecture, expanding DDR5 memory pools and boosting high-performance SSD requiremen...

Driven by strong demand from US and China CSPs, 2026 AI server shipments will surge. Key drivers include NVIDIA and Google's ASICs, accelerating liquid cooling adoption. While general server refresh c...

NVIDIA's H200 supply upside is limited by tight advanced packaging and memory capacity prioritized for new platforms. While targeting the Chinese market, geopolitical risks are driving China...
Raised specs delayed HBM4 production, keeping HBM3e dominant. Samsung leads verification with advanced tech, while SK hynix retains the top share.
Driven by expanding CSP capital expenditures, AI server demand remains robust. Liquid cooling adoption accelerates as the high-end standard. Strong demand pushes HBM3e prices up amid tight supply, whi...

Server DRAM prices surge due to depleted inventory and robust AI demand. HBM expansion squeezes standard supply, causing shortages. Suppliers prioritize major CSPs, cutting allocations for others. Sig...
AI demand drives a 1Q26 seller's market. Capacity shifts to servers cause shortages. DRAM and NAND Flash prices rise broadly despite weak consumer demand.

Looking to 2026, sustained AI infrastructure build-outs will drive server demand. High CAPEX from North American CSPs supports NVIDIA's new platforms and ASICs. While Tier-2 risks exist, robust m...
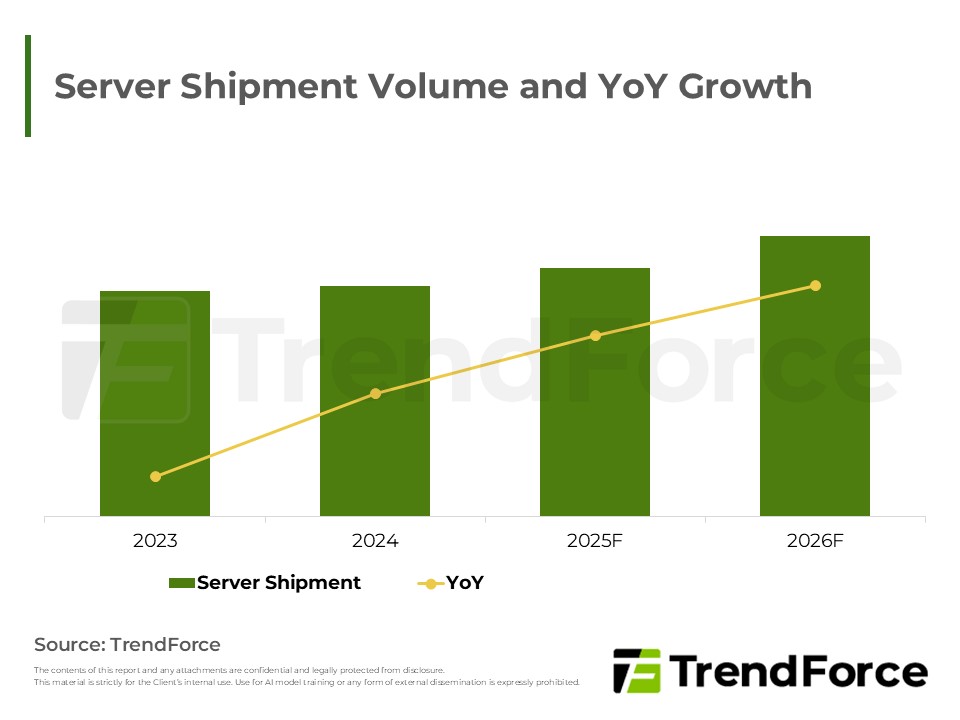
CSP AI investment fuels robust server growth.

Driven by Server DDR5 shortages and rising AI demand, DDR5 profitability now rivals HBM. With suppliers regaining pricing power and buyers increasing orders, the forecasted 2026 HBM3e price decline ha...
North American CSPs' expanded investment in AI and general servers has confirmed a DRAM industry upcycle. With supplier inventory bottoming out and buyers actively restocking, prices and revenue...
The global AI hardware market continues to expand, driven by increasing CSP capital expenditures and accelerated procurement of advanced computing resources. In response, companies are partnering with...


