TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
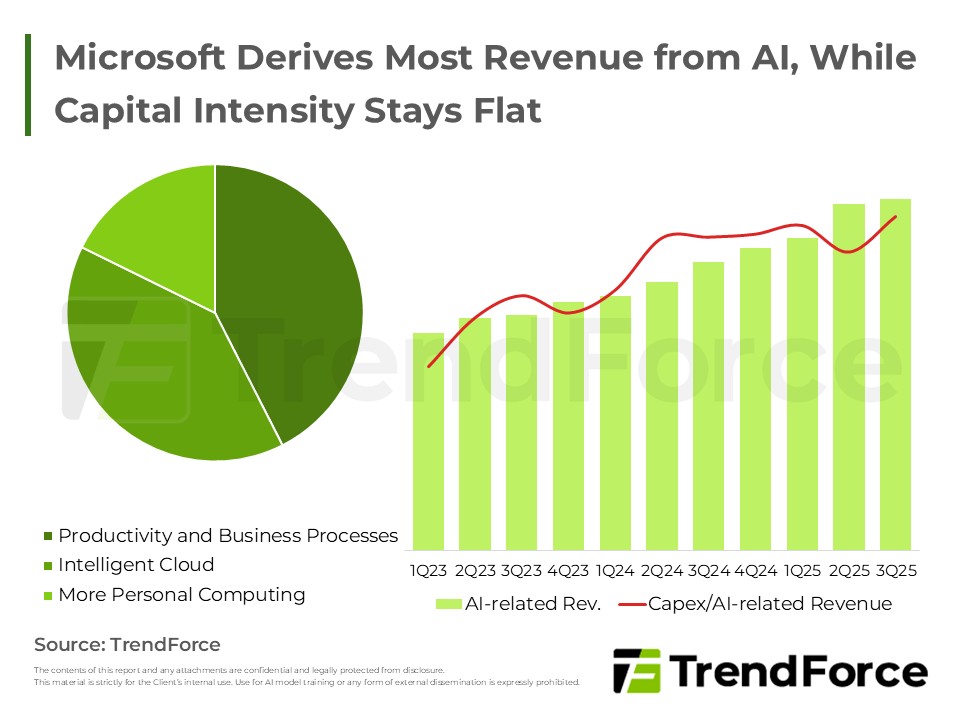
Microsoft and Meta are accelerating AI infrastructure. Microsoft balances capacity constraints via leasing, trading margins for growth. Meanwhile, Meta shifts to an aggressive strategy, leveraging rap...

The global server market is expanding, driven by robust AI infrastructure investments from CSPs and a general server replacement cycle. Major tech giants like Alibaba, Oracle, and Google are increasin...
North American CSPs' expanded investment in AI and general servers has confirmed a DRAM industry upcycle. With supplier inventory bottoming out and buyers actively restocking, prices and revenue...

The US may permit NVIDIA H200 exports to China to hinder full localization. As a strategic compromise, the H200 aims to fill the void left by H20. While facing competition from domestic policies, it r...
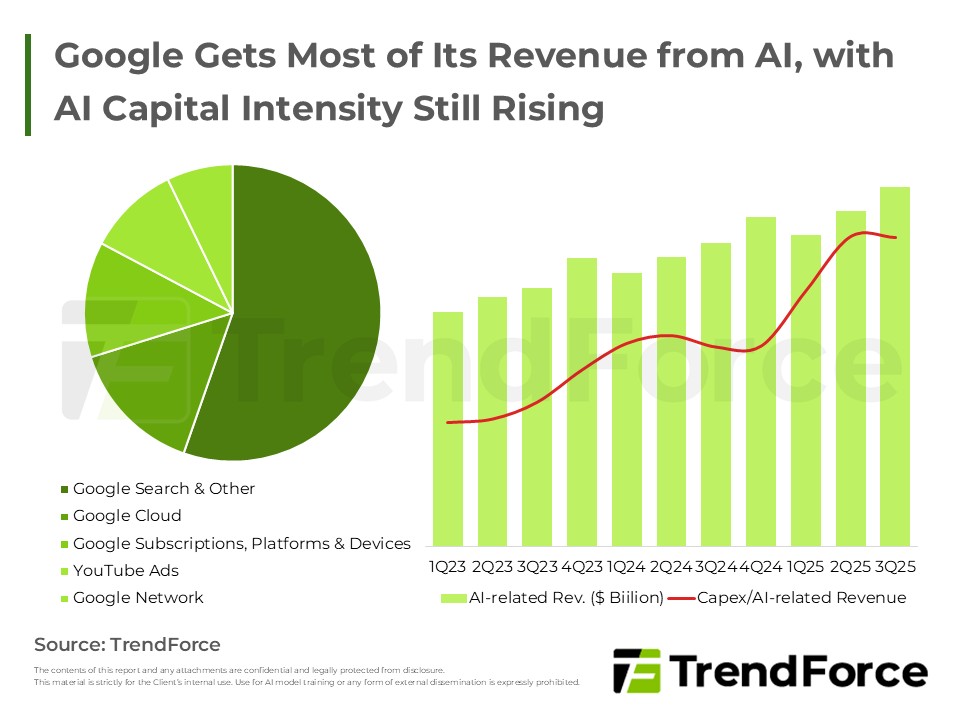
Google and Amazon leverage custom chips for superior AI cost-efficiency. Google pursues aggressive infrastructure expansion to meet demand, while Amazon uses retail cash flow to sustain high capital i...

US data centers drive DDR5 and HBM demand. Rising DDR5 prices boost profitability. Future growth relies on HBM4 and standard DRAM synergy. Revenue mix will shift as standard memory prices recover agai...

CSP self-developed chips and NVIDIA's platforms are driving Arm adoption, eroding x86 dominance in server markets.
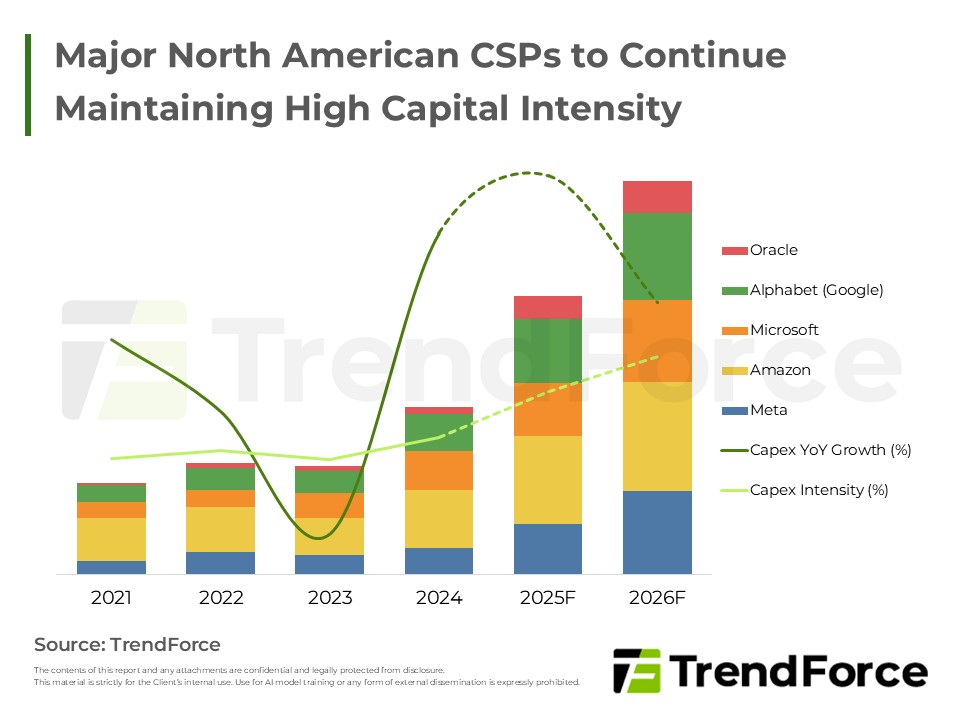
2026 marks the GW-level data center era. CSPs prioritize AI dominance with massive spending. OpenAI shifts to co-developing infrastructure, driving a structural power demand surge.

Server DRAM contract prices surge in 2025 due to tight supply and low inventory. Cloud firms and OEMs accept price hikes, while suppliers accelerate capacity expansion to meet rising 2026 demand; furt...

The report shows AI-driven demand reshaping the server market, with cloud and enterprise deployments accelerating, core focus on GB rack solutions and all-in-one enclosures, and partnerships to streng...
Global Server Market – Trends in 4Q25 and Outlook for 2026

TrendForce shows AI-driven DRAM demand surge, creating supply tension. Samsung, SK hynix, and Micron plan to expand DRAM production through 2026.

This report focuses on NVIDIA data-center growth and rack-based solutions, highlighting large architectures and liquid cooling as core innovation drivers, with regional markets and risk management not...

AI demand lifts memory; fab limits push per-wafer pricing. HBM tight; suppliers favor DDR5; extras may rise.

This report notes AI investment drives cloud and server demand as CSPs and OEMs expand capex and deployment, with in-house chips advancing.


