TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
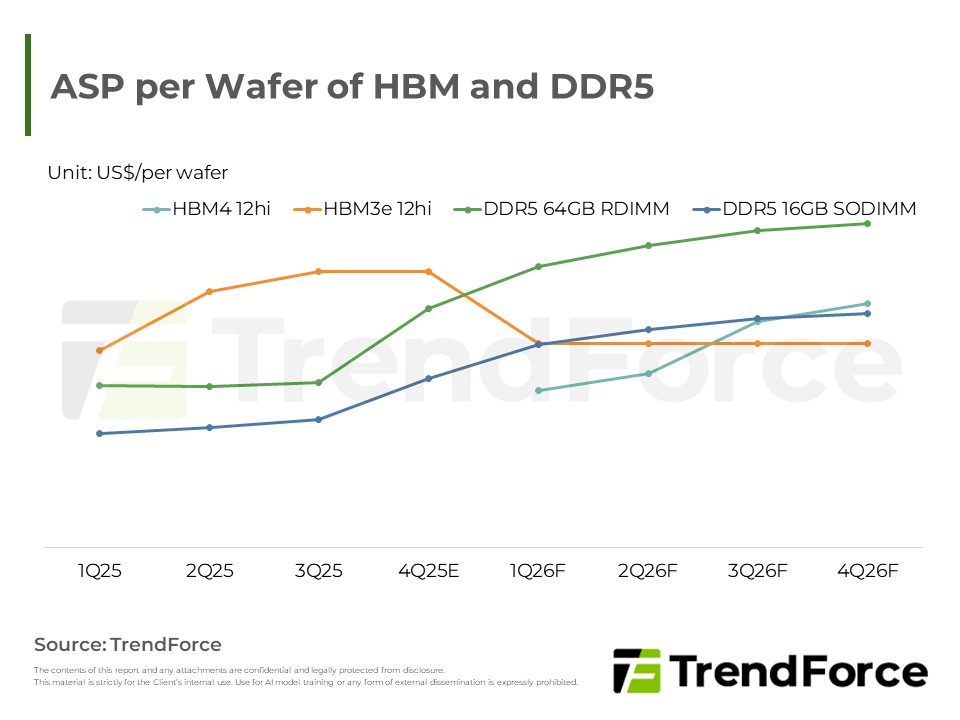
Server DRAM prices are projected to surge due driven by tight supply and robust cloud service provider demand. To secure supply, clients are aggressively negotiating long-term agreements, incentivizin...

AI's evolving demands shift storage from HDDs (high latency) to SSDs (speed, low latency). SSDs offer superior performance and TCO benefits, accelerating their adoption in AI infrastructure.

This report analyzes the global AI server market and supply chain, highlighting key players, tech shifts, and demand-capacity balance.
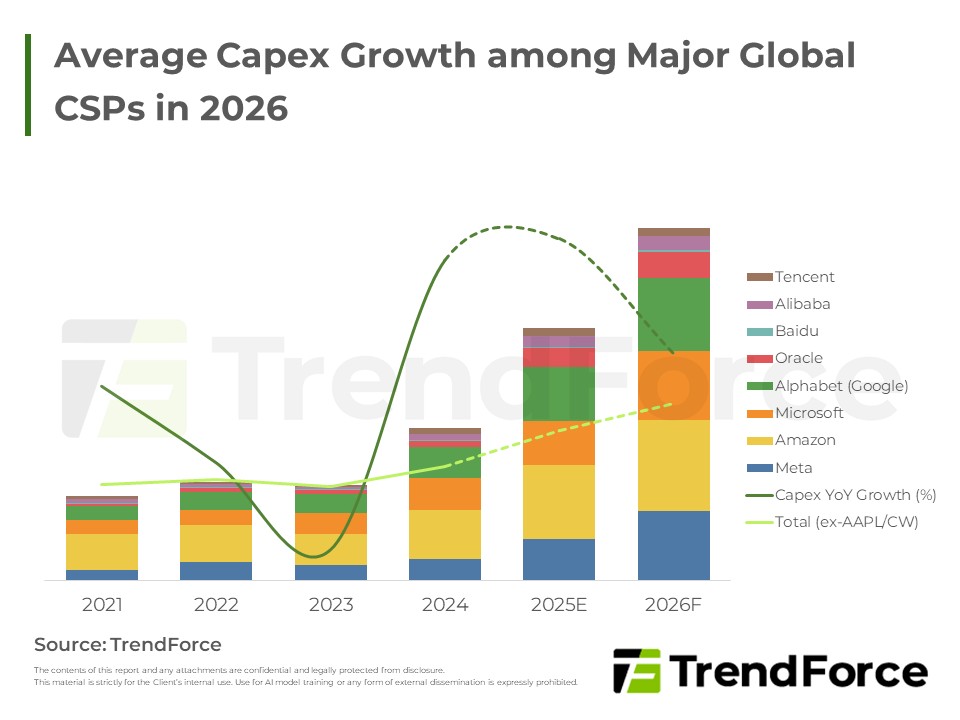
North American cloud giants are substantially increasing Capex, signaling an investment peak in AI infrastructure over the next two years. Shifting to large-scale, long-term strategies, they are focus...

The rise of AI and HPC workloads has significantly increased GPU power consumption, from a few hundred watts to over 2,300W in the Rubin generation. This evolution has elevated cooling from a mere sup...

Strong CSP demand is driving server DRAM prices significantly higher, with 4Q25 increases revised upwards. CSPs are proactively securing 2027 supply, incentivizing manufacturers to boost capacity, sig...
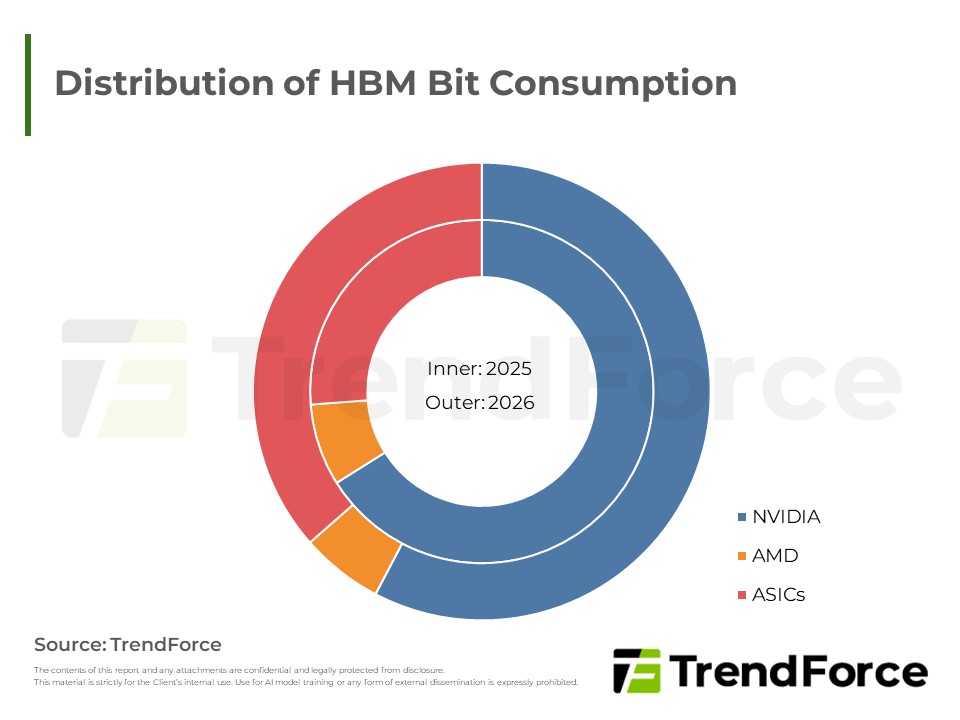
Major suppliers are expanding HBM capacity, with 2025 shipments revised upward. SK hynix leads with 150K TSV capacity, while Micron ramps up its Taiwan facilities. By 2026, all three will begin HBM4 m...
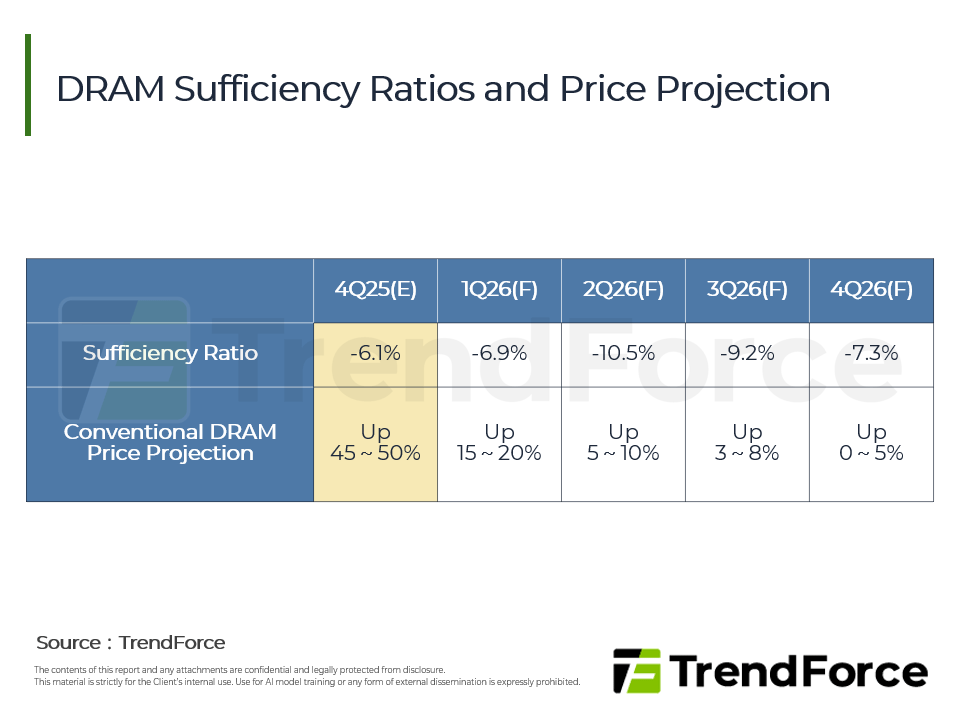
A clear uptrend is taking shape for 2026, with tighter DRAM supply and broad-based price increases now firmly in sight. The primary growth catalyst is CSPs, which are accelerating data center expansio...

AI servers lead growth; cloud build-outs lift ODMs/thermal. AMD ramps; TPU up; shift to L2L cooling. Supply chain heat-up end to end.
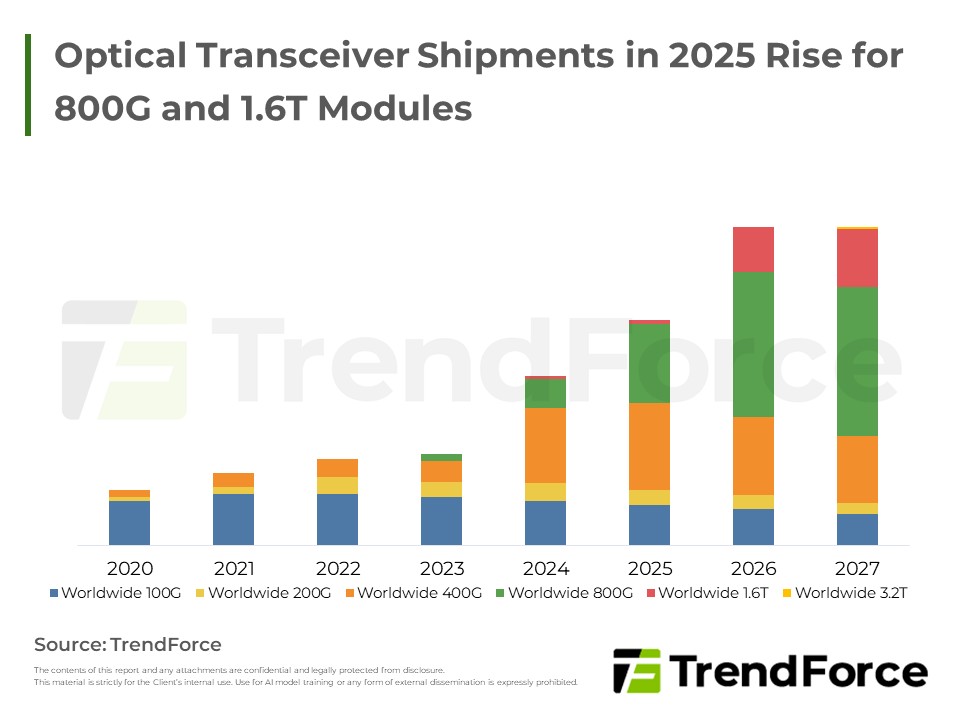
AI-driven data centers evolve from single-chip to heterogeneous multi-GPU architectures. High-speed optical interconnects enable scalability, while silicon photonics and co-packaged optics boost bandw...

This report show Google and AWS driving strong HBM demand, with capacity expanding across generations; META and Huawei join as large buyers.

Global AI server market stays strong as major cloud providers expand infrastructure and platforms; GPU and self-developed ASIC demand rises amid regional dynamics.
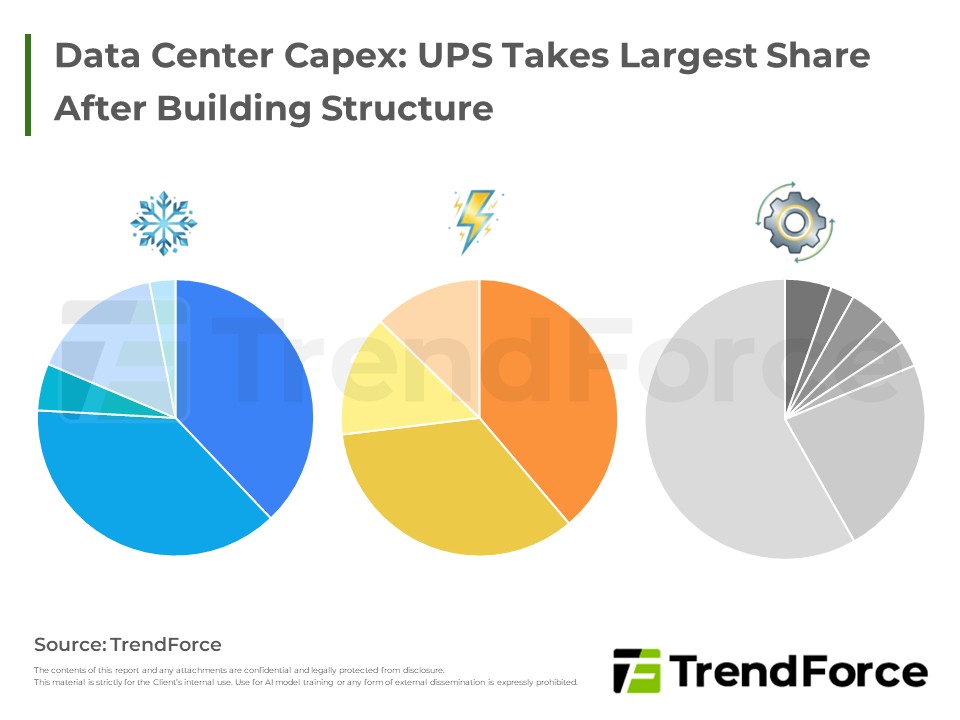
This report analyzes the capital expenditure structure of a typical hyperscale AI data center, breaking down the spending into physical infrastructure, IT computing facilities, and networking equipmen...

2026 NAND Flash: AI drives explosive enterprise SSD demand, offsetting weak consumer markets. HDD shortages compel a shift to high-capacity QLC SSDs. Despite bit growth, supply for these remains struc...

TrendForce forecasts a structural memory price hike by 2026. Strong AI server demand and profit-first supplier strategies lead to capacity shifting towards high-margin applications, driving widespread...


