TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.

The server market notes North American cloud providers as the growth engine, with enterprise OEMs cautious, and AI servers plus efficient cooling as priorities. Key players like Compal and Supermicro...
AI servers and chips up; GPU and in‑house ASIC advance. Liquid cooling grows; storage favors higher capacity.

Sept 2025 server DRAM contract prices surged due to persistent CSP demand, with DDR5/DDR4 increasing. 8000MT/s modules will see accelerated adoption. Strong 2026 demand and tight supply are set to ext...
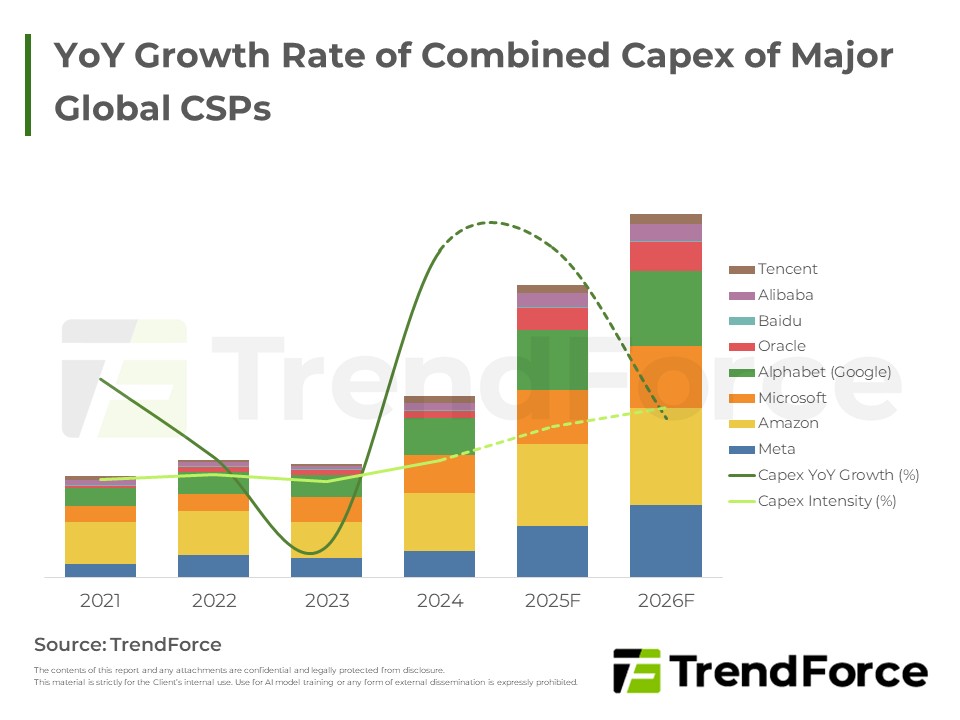
Cloud providers lift AI Capex to new highs; rack-scale GPU and custom ASICs rise, liquid cooling spreads.
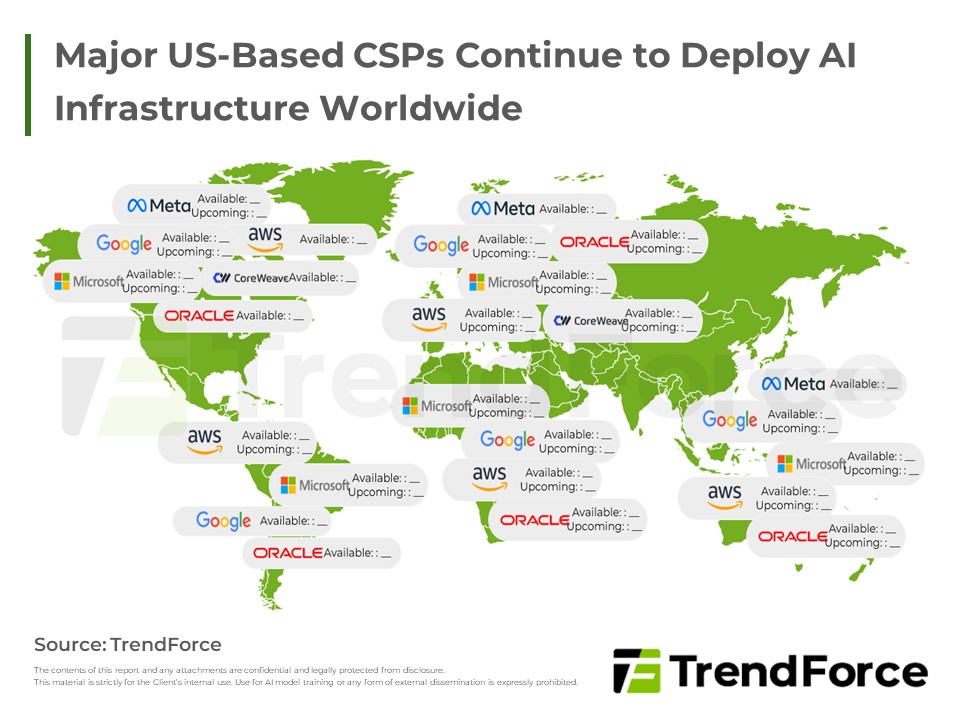
The report highlights AI data center expansion by U.S. and Chinese CSPs. U.S. firms scale globally and invest more at home, while Chinese firms expand with self-developed chips, but both prioritize en...
U.S. inflation pressures and labor market weakness lead to rate cuts; traditional demand drops while AI servers and automotive electronics grow, causing supply chain segmentation.
Robust AI server demand, driven by NVIDIA, AMD, and CSP custom ASICs, propels market growth. DDR5 is mainstream, yet DDR4 sees extended life and price rebound from storage needs. AMD and ARM challenge...

Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...

4Q25 memory prices continue upward. Strong AI demand from US CSPs and HDD shortages boosting enterprise NAND Flash are key. Suppliers prioritize profit, tightening old process supply.

This bulletin covers CSP and OEM trends; North CSPs expand AI buildout, China faces headwinds and uncertain demand.

Geopolitical constraints and import controls curb RTX PRO in China, with a special edition awaiting broader demand; CPX adopts GDDR7 memory with increased capacity, complementing Rubin GPUs that rely...

NVIDIA Rubin platform plans mid-to-late year packaging and server assembly, with HBM4 sampling, certification and mass production have to be completed beforehand. To counter AMD, NVIDIA raises HBM4 sp...
2Q25 server DRAM revenue increased by 11% QoQ, driven by DDR5 shipments and DDR4 price recovery. CSPs shifted from destocking to restocking, and DDR4, due to strong demand for storage server applicati...

AI servers remain higher than general-purpose servers regarding shipment dynamics among ODMs in 2H25, thus triggering growths for liquid-cooling suppliers. Liquid-cooling solutions are likely to penet...

DRAM contract prices are expected to peak by late 2025, then decline as new capacity emerges. DDR4 faces critical long-term shortages. HBM3e prices soften, HBM4 maintains a premium, with Samsung leadi...


