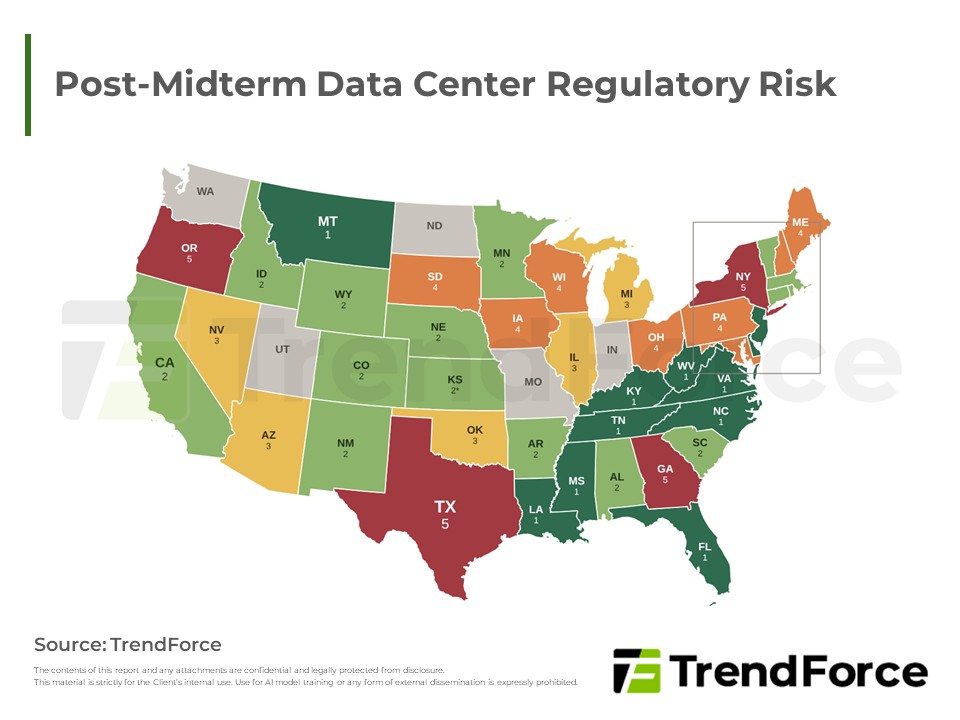
Post-midterm moratorium pledges in key states raise delay risk for 2028+ US data center builds; hyperscalers are best placed to adapt.
TrendForce reports that weak PC and smartphone demand, combined with China’s still-unproven AI business models, has made server SSD procurement cautious. With module makers’ inventories piling up and...
Rising CSP capex, AI inference, agentic AI and custom ASICs lift AI server shipments, tighten CPU supply and speed liquid cooling.
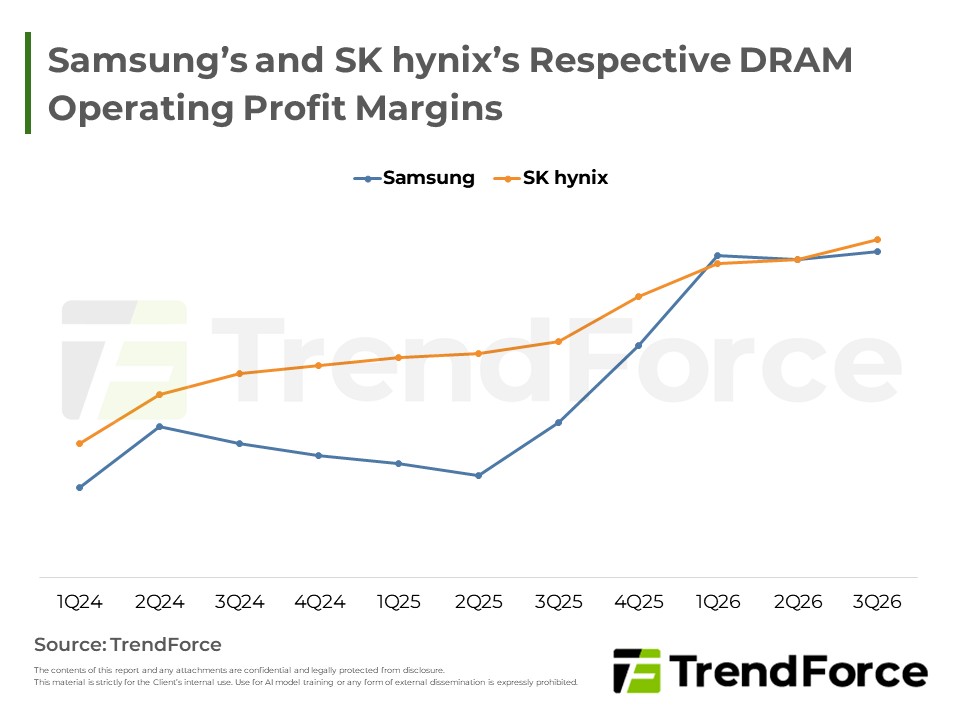
Server DRAM contract prices are rising, with gains varying by RDIMM capacity, while overall spot momentum remains limited. SK hynix and Samsung reported higher DRAM shipments and prices, along with gr...
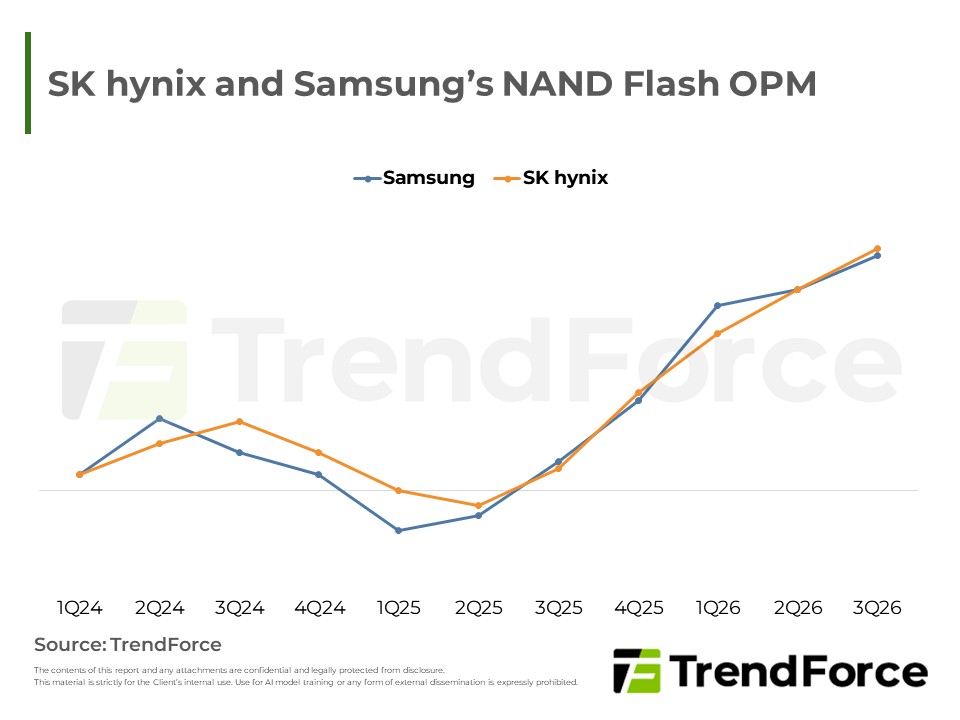
Surging CSP capex has raised doubts about AI monetization. Consumer contract price negotiations remain stalled and spot demand is weak, while enterprise SSDs, supported by AI demand, are leading price...
Besides the mainstream product segments of the DRAM market, TrendForce’s research now encompasses specialty (consumer) DRAM products as well. Analyses in this area pertain to product development plans...
Global Server Market – Trends and Outlook for 4Q26
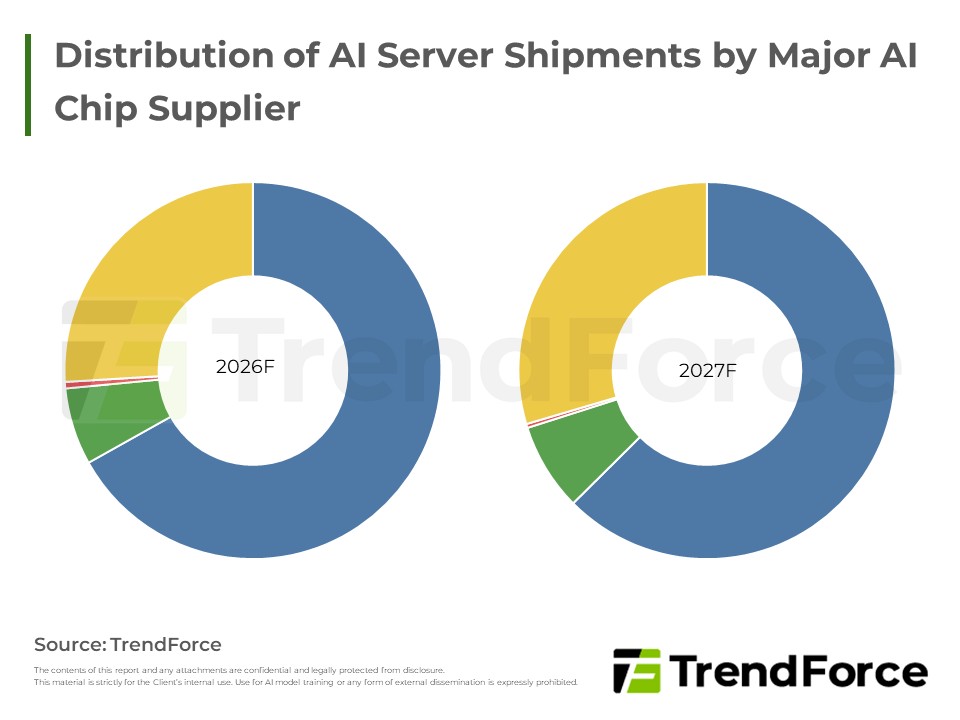
CSP capex fuels AI servers; NVIDIA leads as Rubin follows Blackwell, while ASICs, liquid cooling and HBM4 surge.
Fourth-quarter contract prices for smartphone mobile DRAM are expected to range from flat to slightly higher, consolidating at elevated levels. With brand inventories at target and year-end cash flow...
Server DRAM contract prices continued to climb this month, with suppliers keeping strong bargaining power by adjusting product and customer mix. Buyers are rapidly shifting toward low- to mid-capacity...
PC DRAM contract prices keep rising in the fourth quarter, though gains are narrowing amid tense negotiations. Weak notebook shipments and rising inventory push second-tier OEMs toward white-label mod...
Consumer DRAM supply remains tight, but year-end caution and elevated memory costs have slowed demand, narrowing contract price gains to flat-to-slight increases. Spot prices have retreated from their...
North American buyers continue to raise their order forecasts, and with suppliers unable to adjust capacity in time, enterprise SSD contract prices keep rising this quarter, though Chinese customers a...
For the price chart of global end prices of SSD, TrendForce segments product categories in accordance with capacity (from 120GB to 2048GB and above) and user interface (SATA3, PCIe 3.0/4.0/5.0).
This month, the niche NAND Flash market diverged as capacity kept shifting toward advanced processes. SLC continued to rise on firm demand from automotive, networking, and LEO satellite applications,...


