


 Download Report
 Contact Us
Module Dumping Drags NAND Spot Prices Lower

Last Modified
2026-11-05

Update Frequency
Aperiodically

Format
TrendForce reports that weak PC and smartphone demand, combined with China’s still-unproven AI business models, has made server SSD procurement cautious. With module makers’ inventories piling up and forcing price cuts, NAND Flash spot prices are weakening rapidly. Demand now rests solely on North American CSPs, and spot prices show no sign of bottoming out in the near term.
Key Highlights
- Consumer: PC and smartphone sales remain sluggish, and spec downgrades are curbing bit demand. Meanwhile, Chinese NAND capacity is flooding the market, so supply far exceeds what end demand can absorb.
- China server: Paid AI services have yet to catch on and subscriptions remain hard to monetize. With capital spending kept cautious, Enterprise SSD procurement has turned conservative.
- US server: AI model subscription revenue supports continued deployment expansion by CSPs. Demand is concentrated among a few players, however, which raises structural risk.
- Spot market: Module makers face high inventories and mounting cash-flow pressure, so they keep dumping stock. Spot prices have fallen below their previous lows and lack conditions to stabilize in the near term.
- Outlook: Until suppliers adjust wafer allocation, consumer-grade and spot prices will stay under pressure. The divergence of “US Enterprise SSD strong, everything else weak” will continue to widen.
Table of Contents
- Weak Consumer Demand and Downward Revisions to China’s Enterprise SSD Demand Limit Gains in NAND Flash Contract Prices
- Spot Price Has Dropped to US$15 for 512Gb TLC Wafers as Swelling Inventories Force Module Houses to Drive Sales by Cutting Prices, Leaving US CSPs as the Sole Demand Pillar in the Server Segment
- Due to Tepid PC and Smartphone Sales, OEMs Have Started to Cut Costs and Downgrade Specifications, Leading to a Continuation of Constrained Bit Demand
- In China, Paid AI Services Have Yet to Gain Traction and Cost Savings from Open-Source Models Still Fail to Make Subscriptions Profitable; Investments in Server SSDs Have Turned Conservative
- Commercial Subscriptions of AI Models Support Ongoing Investment among North American CSPs; Only Few Players Would Come Out on Top from Emerging Divergence in Model Strength and Profitability
- Spot Prices Dropping from March 2026 Peak and Now Dipping Below July and August Lows; Module Houses’ Dumping Lacks Short-Term Support
- Comparison of Demand Momentum and Price Impact on NAND Flash among Various Applications
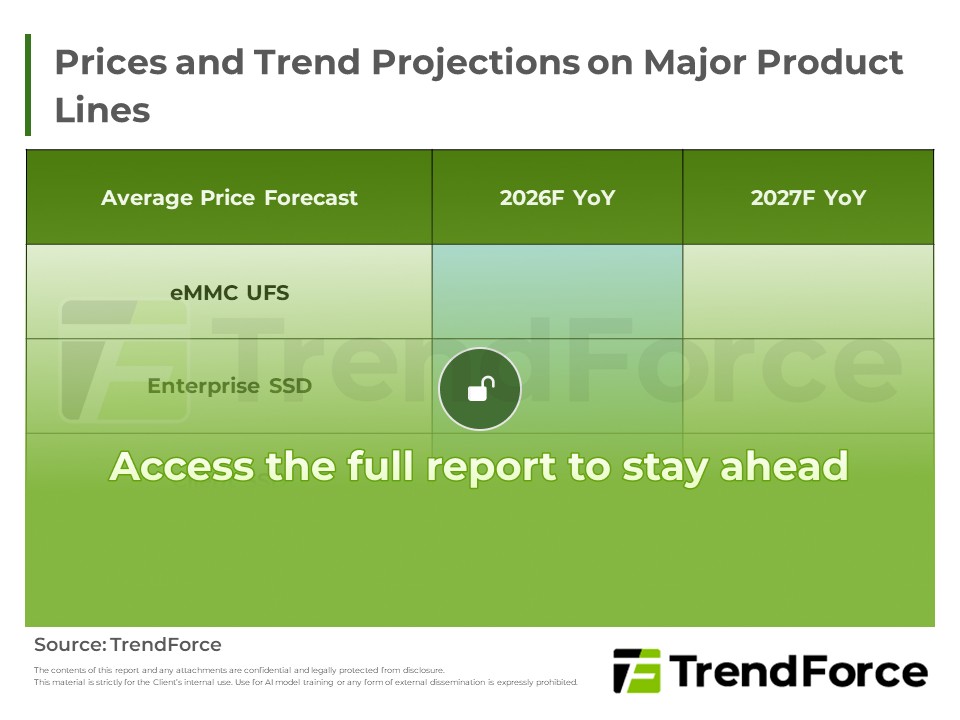
- Prices and Trend Projections on Major Product Lines
<Total Pages: 7>

Spotlight Report
-

DRAM Monthly Datasheet Oct. 2026
2026/10/16
Semiconductors
EXCEL
-

NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-

4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-

Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-

DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-

DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF
NAND Flash PlatinumRelated Reports

Download Report
18,000

Membership
Spotlight Report
-
DRAM Monthly Datasheet Oct. 2026
2026/10/16
Semiconductors
EXCEL
-
NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-
4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-
Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-
DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-
DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF