TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.

Driven by robust AI demand and supply shortages, Korean makers raised quotes, triggering a sharp rise in Server DRAM contract prices. Supply growth lags behind demand despite capacity shifts. Conseque...
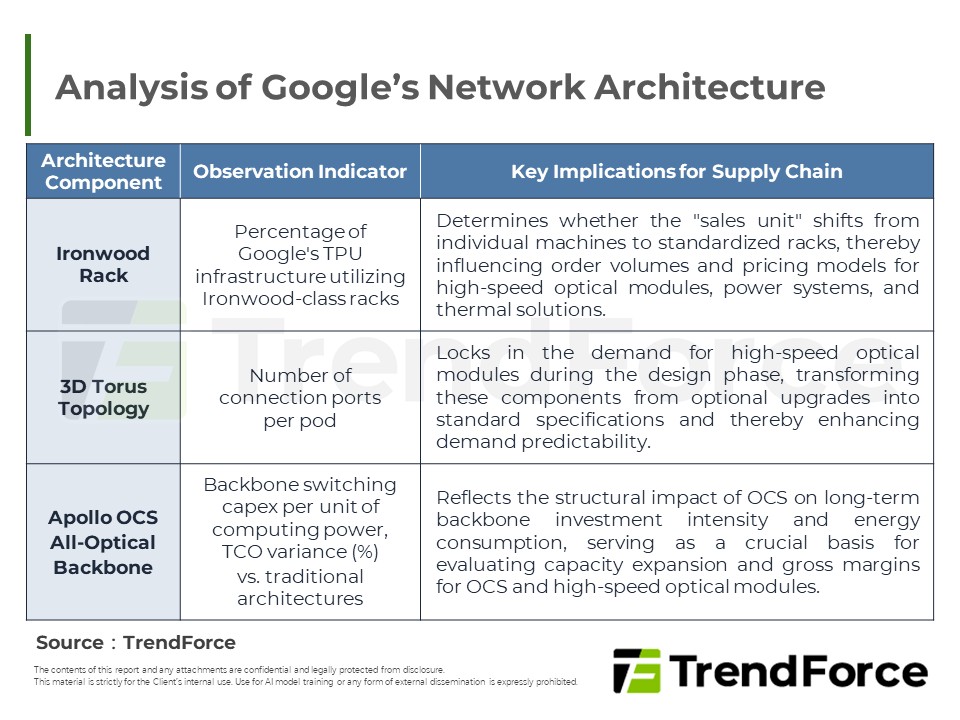
1. Google is consolidating its proprietary TPUs, Ironwood racks, 3D Torus topology, and the Apollo OCS optical backbone into a unified high-speed interconnect architecture. As a result, the focus of c...
As AIDC enters a high-power era, competition shifts to power and cooling infrastructure. Power architectures move toward HVDC, while cooling upgrades to liquid systems. Leading firms are integrating "...

Samsung currently leads HBM4 validation due to process improvements enhancing stability. SK hynix retains volume leadership despite re-sampling, while Micron trails slightly. Given robust AI demand an...
In 1Q26, strong Server and AI demand drove manufacturers to prioritize enterprise products, severely constraining consumer eMMC and UFS supply. Despite the seasonal lull, low inventories and shortage...

DRAM industry will focus on HBM capacity expansion, with Chinese suppliers limited by equipment restrictions; major players like Samsung, SK hynix, and Micron emphasize tech migration and AI applicati...
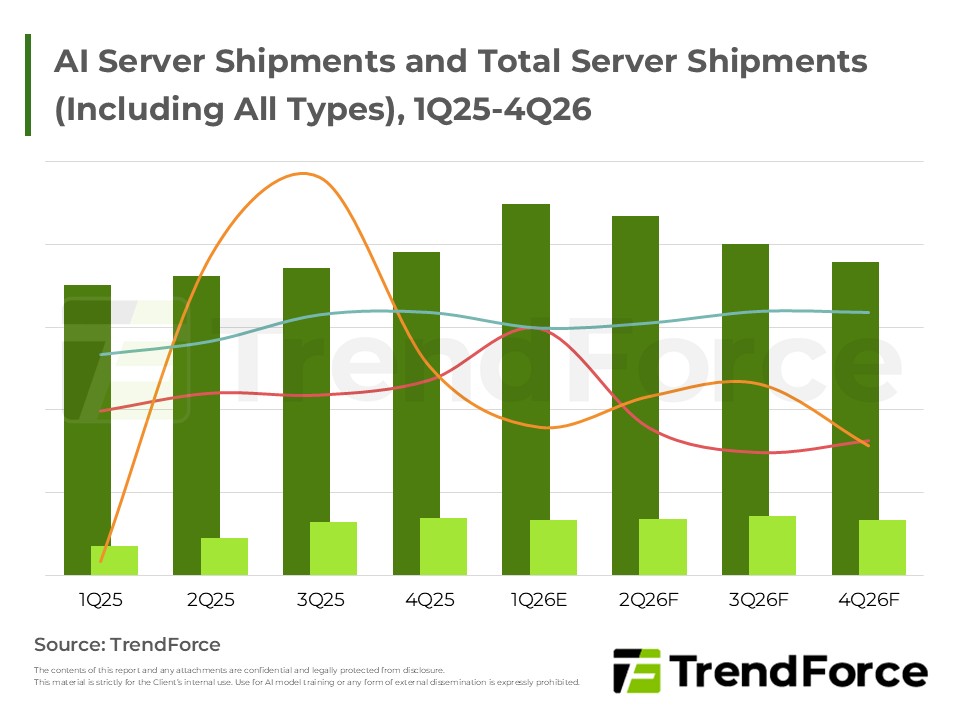
Looking ahead to 2026, major global CSPs are significantly increasing capital expenditures on AI infrastructure, focusing on high-density GPU racks and self-developed ASICs to optimize costs. North Am...
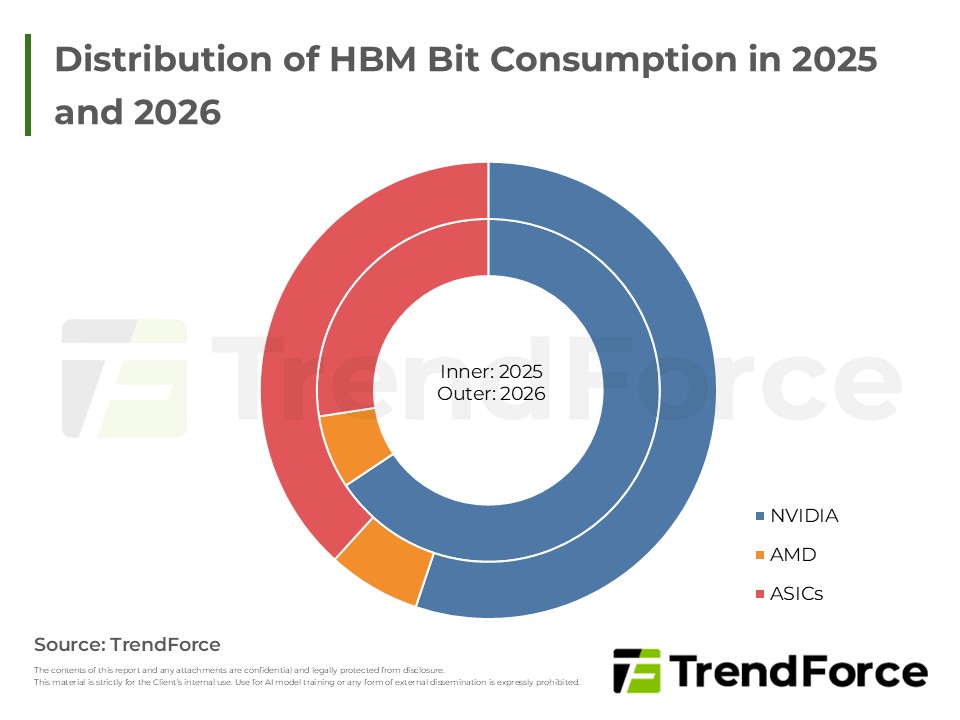
In 2026, the HBM market continues to grow, with SK hynix maintaining its lead and Samsung recovering significantly via HBM3e and HBM4 contributions. Micron also expands aggressively. While HBM3e domin...
Global Server Market – Trends and Outlook for 1Q26
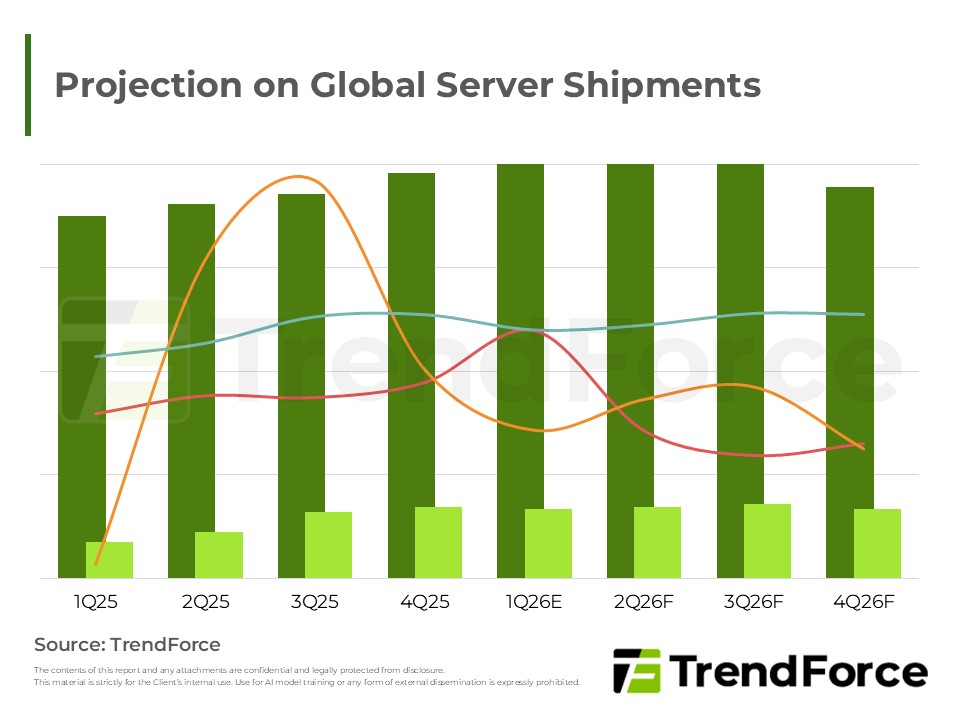
NVIDIA and CSPs drive sustained AI growth through aggressive investment in GPUs, ASICs, and rack-scale infrastructure. Geopolitics reinforce ecosystem trends, benefiting supply chains. Surging AI work...

Server DRAM prices are set for a sharp surge in early 2026 driven by critical shortages. Suppliers retain strong leverage, with Korean makers delaying quotes to maximize hikes. Despite capacity reallo...
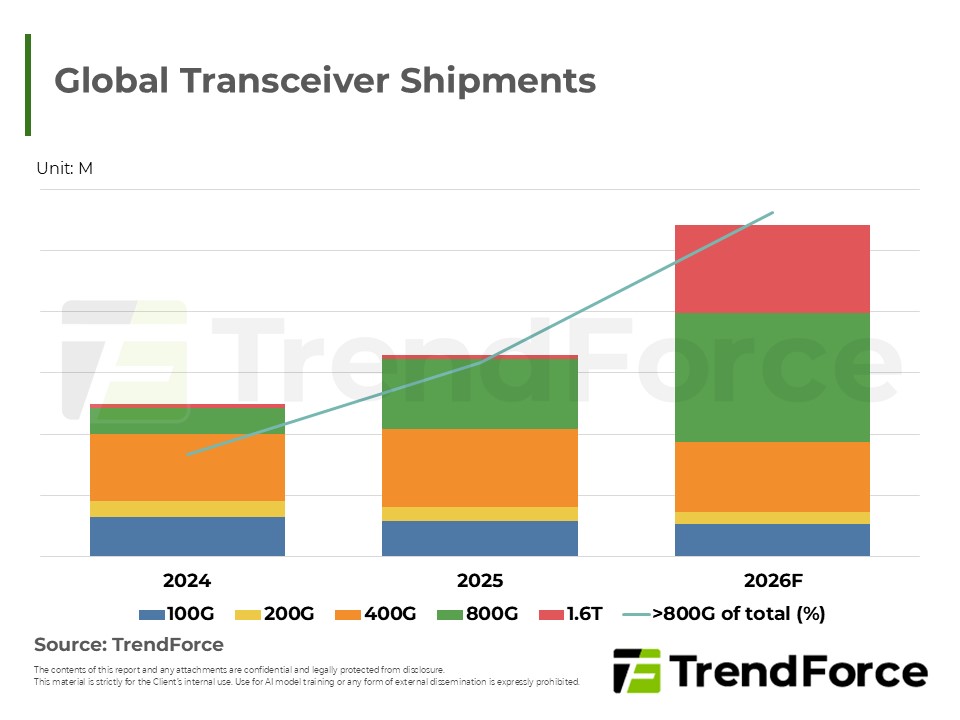
Google integrates TPU v7/v8, Ironwood racks, and Apollo OCS into a unified fabric, shifting the scaling unit from servers to racks. This drives 800G+ optical module penetration above 60% by 2026. Supp...
Persistent DRAM supply shortages have empowered suppliers, driving sharp upward revisions in contract prices. High-margin Server DRAM now leads profitability, prompting capacity shifts. Consequently,...

In 2026, benefiting from strong capital expenditure by North American CSPs, AI server shipments and revenue share are expected to rise significantly, driving supply chain expansion and the development...

Driven by policy, Chinese firms accelerate HBM development to support domestic AI chips. CXMT targets advanced nodes while JHICC focuses on mature processes. Both face technical hurdles and are in ear...


