TrendForce provides industry research reports on AI servers and data centers, covering GPU server shipments, CSP capex trends, and liquid cooling adoption.
Reports cover GPU and ASIC server shipment forecasts, hyperscaler capex, and data center build-out dynamics; in-depth tracking of HBM (HBM3e, HBM4) supply-demand balance, market pricing, and vendor competition; alongside analysis of liquid cooling penetration, co-packaged optics (CPO) mass production progress, server CPU demand shifts, and monthly Server DRAM and DIMM contract price updates.
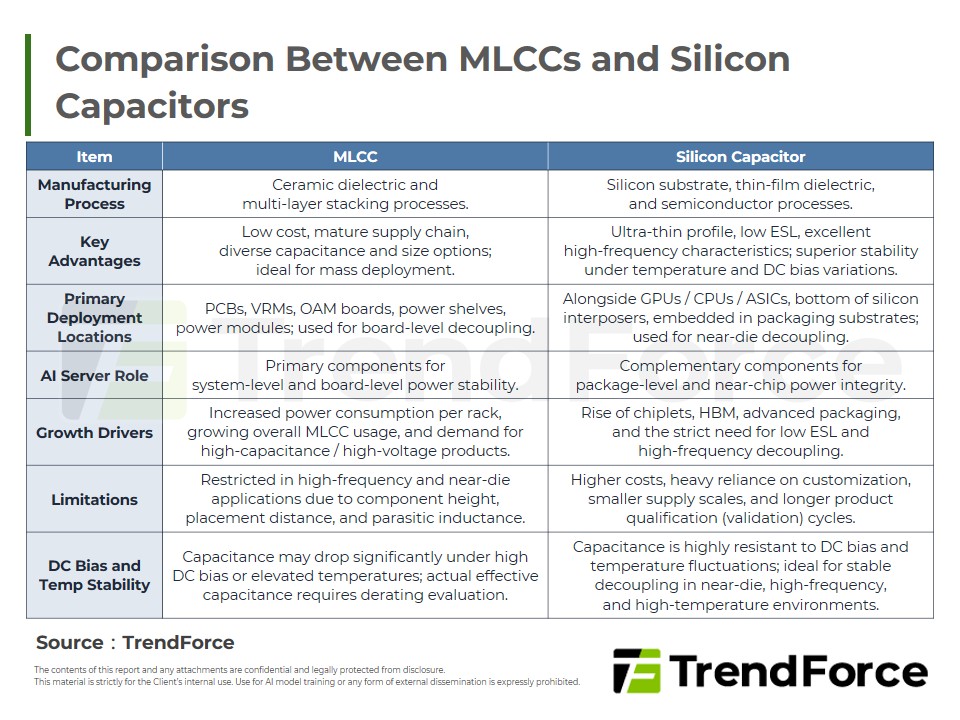
The need for power integrity in AI servers is extending from the board level directly into the package. This shift is driving a transition in capacitor technology, moving beyond a sole reliance on tra...
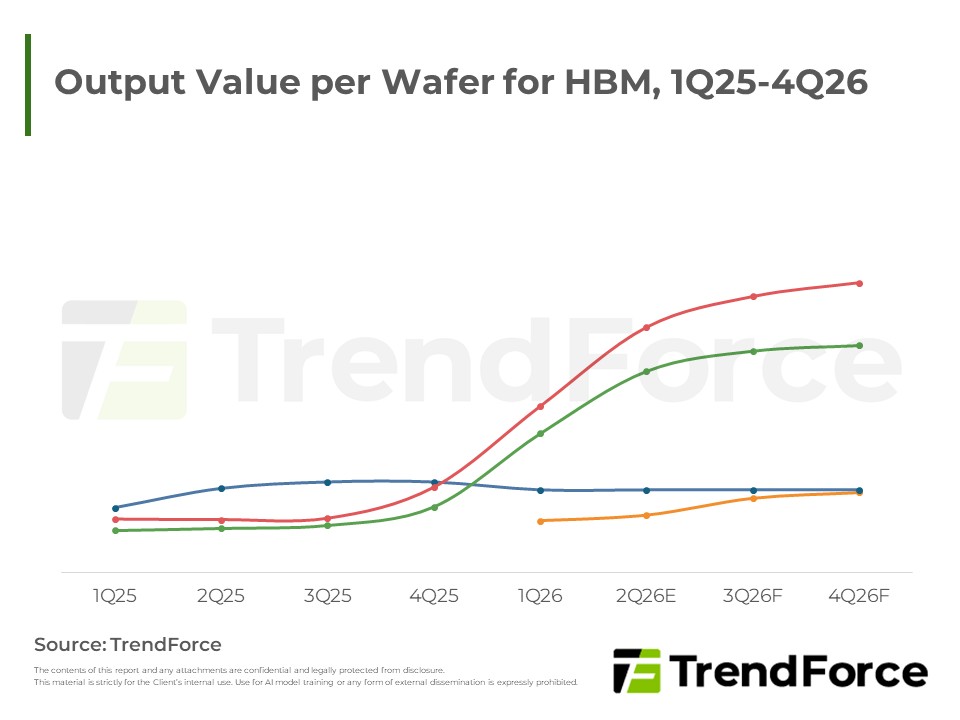
HBM 2027 supply talks remain unresolved as suppliers push for steep price hikes; NVIDIA's SOCAMM adjustment reflects supply constraints, not demand reduction.
AI demand and proprietary chip adoption drive upward revisions in global server shipments. Despite supply bottlenecks, memory face severe shortages and soaring prices. AMD and alternative architecture...
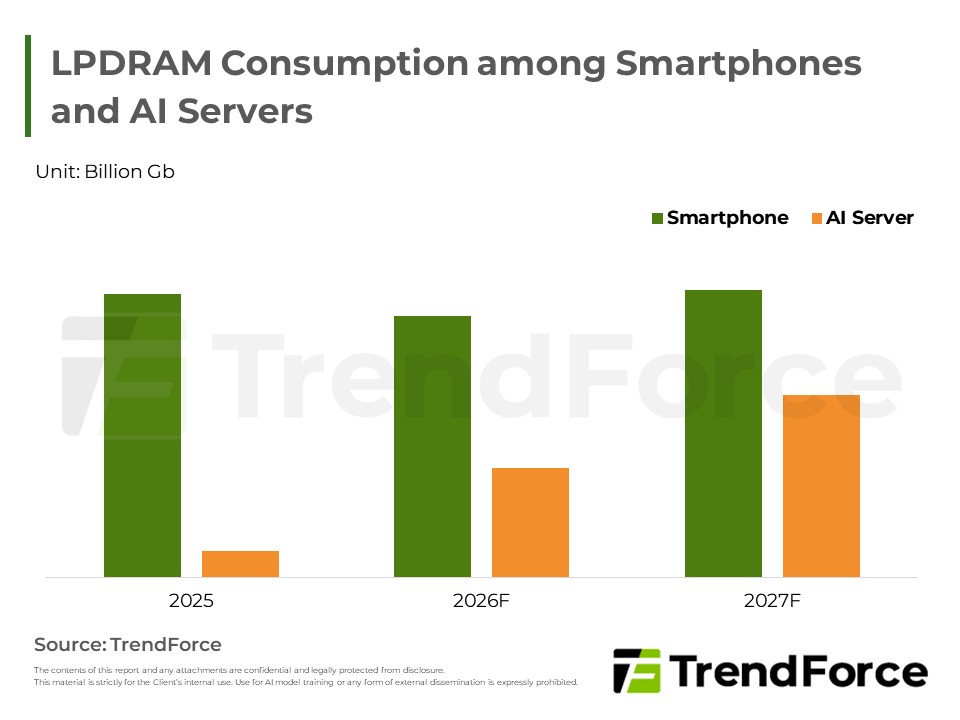
Beyond full-rack solutions, NVIDIA is also actively promoting its standalone Vera CPU to capture the AI inference market. However, given the LPDRAM supply bottleneck, NVIDIA has decided to reduce the...
Driven by agentic AI applications, the server DRAM market experienced explosive growth. The need for models to handle complex computations and offload long contexts has led to a severe shortage of key...
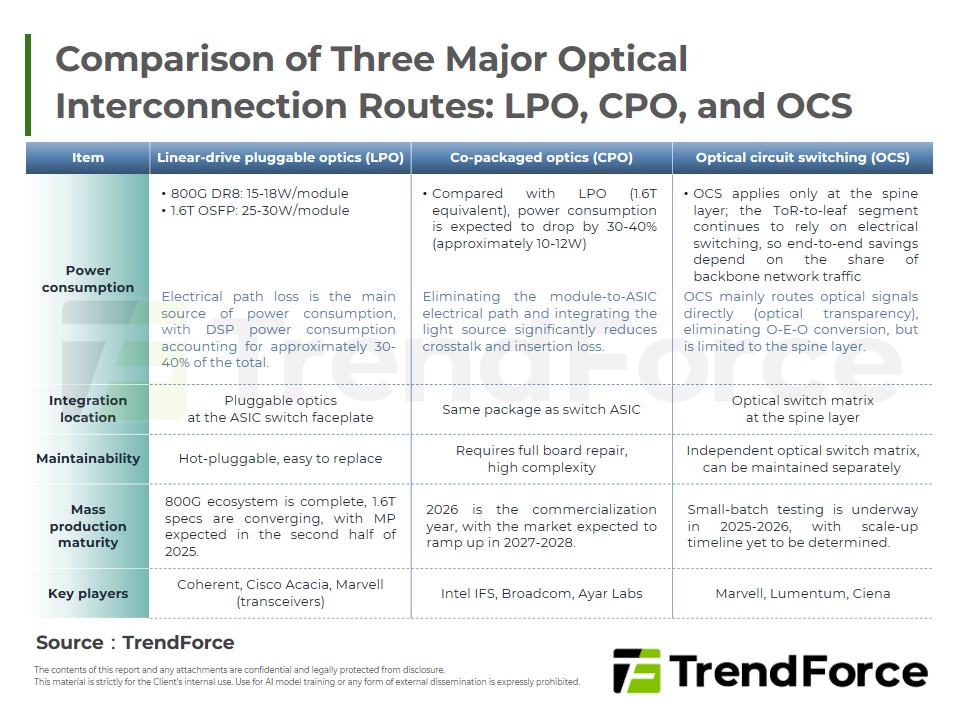
Co-packaged optical (CPO) technology is entering the commercialization stage, driven by AI data center demand for higher bandwidth and lower power consumption. Volume production begins in 2026, with l...
TrendForce raised its 2026 global server shipment forecast, driven by surging AI server demand from CSPs and enterprises, with momentum expected through 2027.

HBM remains irreplaceable in AI accelerators. HBM4 ramps, tight supply lifts prices, and ASIC demand diversifies the supplier base.

Server DRAM contract prices continue to rise due to supply deficits and depleted manufacturer inventories. Although premium pricing on high-capacity modules and shifts in processor configurations have...
AI demand tightens high-end MLCC supply, prompting agents to raise prices and strengthening supplier bargaining power. Geopolitical risks and inflation raise costs, curbing ODM leverage, with high-end...
As AI server platforms advance, power architectures evolve into multi-track systems, and cooling accelerates toward full liquid solutions. Delta and LiteOn capture cloud service provider and new platf...

Since 2H25, accelerated AI infrastructure buildouts by CSPs have surged HBM demand and crowded out conventional DRAM capacity, pushing the broader DRAM market into shortage. Constrained by annual pric...
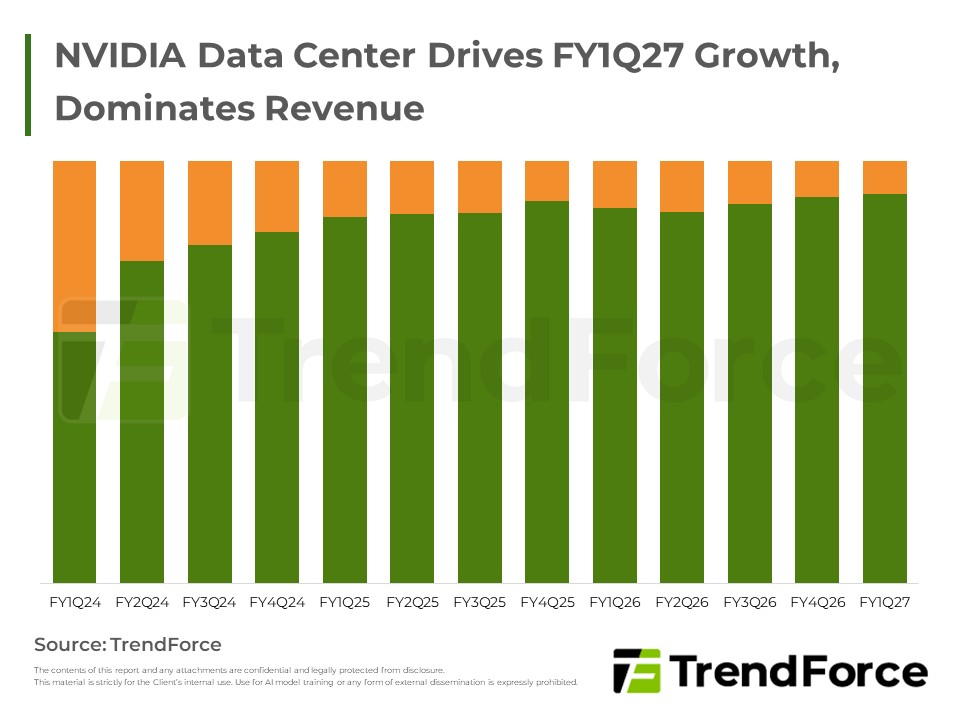
NVIDIA FY1Q27 hit a record high with Data Center share above 92%,with GB/VR Rack rollout boosting liquid cooling and HBM supply chains.
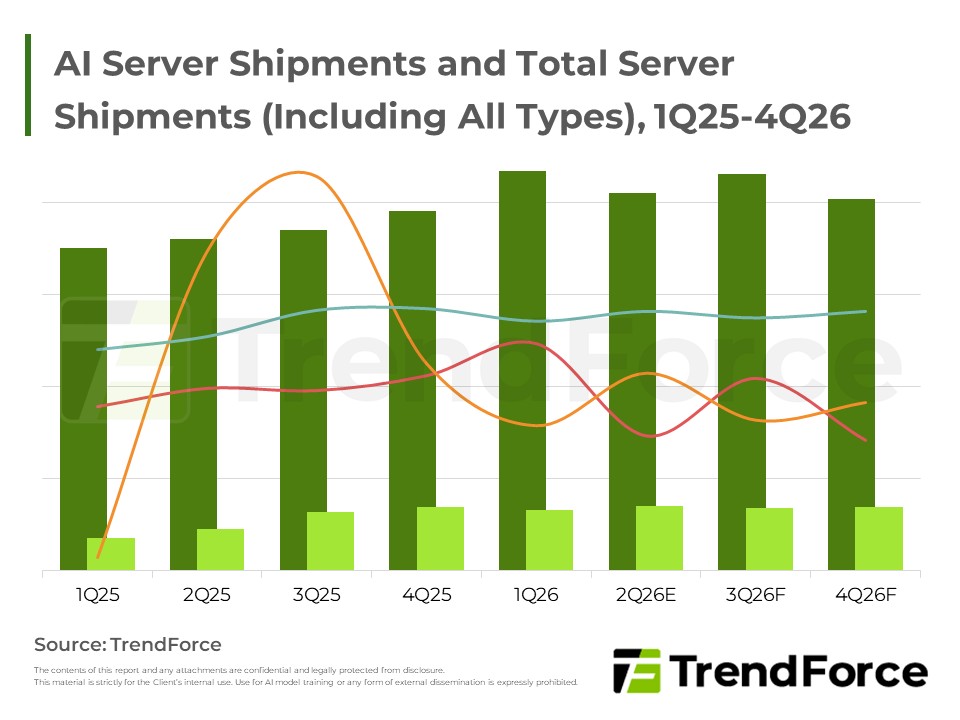
2026 server market accelerates on AI demand; CSPs expand CAPEX while OEMs compete via rack-scale and liquid cooling solutions.

This report first explains why HBM plays a key role in the evolution of LLM and AIGC applications. It then examines the HBM upgrade roadmap and explores how heterogeneous memory integration strategies...


