In 4Q26, buyer pushback at peak costs, high inventory and Chinese vendors’ rising share curb TLC eMMC/UFS gains, while MLC eMMC dips on substitution; 1Q27 off-season prices plateau as MLC faces heavier cuts.
Fourth-quarter contract price hikes are set to narrow as spot prices stay range-bound, while hybrid bonding replaces layer stacking as the key to NAND speed and cost.
TrendForce has raised the capex forecast for major US and Chinese CSPs. With memory contract prices remaining elevated, memory spending is set to exceed half of total capex, while suppliers are prioritizing capacity for server products. CSPs are expected to balance total cost of ownership through architectural adjustments such as memory tiering and pooling.
Toshiba is significantly expanding its HDD capacity in the Philippines, but given the lead time from investment to output, the benefits will materialize later, adding supply to the market without reshaping the competitive landscape. Areal density remains the key to HDD competition: Seagate leads with its fully in-house HAMR technology and is poised to overtake WD as the largest supplier, while Toshiba, still on MAMR, can only compete on volume.
Micron's strong results and upbeat outlook show AI data centers, edge AI and physical AI driving high-capacity storage demand, with data center SSDs as NAND's core profit engine. Disciplined supply and slow capacity expansion keep the market tight and suppliers in control of pricing, while long-term agreements and customer prepayments boost earnings visibility and could reshape the memory cycle.
Robust AI demand has driven profitability in HBM and server products, squeezing consumer memory supply and sparking explosive growth in memory prices and industry revenue. DRAM vendors are substantially boosting capital expenditures for new fabs, with tight supply expected to persist into the year after next. Conversely, NAND Flash investment remains conservative due to space constraints and resource prioritization toward DRAM, relying primarily on node migrations for bit growth.
The memory market is exhibiting a clear two-tier divergence. Strong demand for high-performance storage, driven by cloud and artificial intelligence applications, is keeping supplier inventories at low levels and giving sellers significant pricing power, which continues to drive up enterprise market prices. In contrast, weak end-user consumer demand has fostered a cautious wait-and-see attitude among buyers, leaving spot prices in consolidation, while inventories at brand manufacturers and module houses have risen due to autumn restocking and resource allocation exchanges.
Driven by weak consumer end-market demand, NAND Flash wafer prices have stagnated at high levels. Although enterprise demand remains strong due to AI, inventory continues to pile up on the consumer side, leading suppliers to manage stock through bundled sales. Buyers show extremely low willingness to chase higher prices, with only select specifications seeing slight increases while overall prices consolidate sideways. If consumer inventory digestion continues to fall short of expectations, market prices face a heightened risk of a downward pull-back.
As original manufacturers shift production capacity to high-layer 3D processes, niche NAND Flash prices remain hovering at high levels. Influenced by buyers' cost pressures and supply discrepancies, price growth for low-capacity SLC has slowed significantly, whereas high-capacity SLC maintains its momentum, backed by rigid demand in automotive and networking applications. Meanwhile, due to extremely scarce supply and a hard price ceiling, MLC has entered a flat consolidation phase overall.
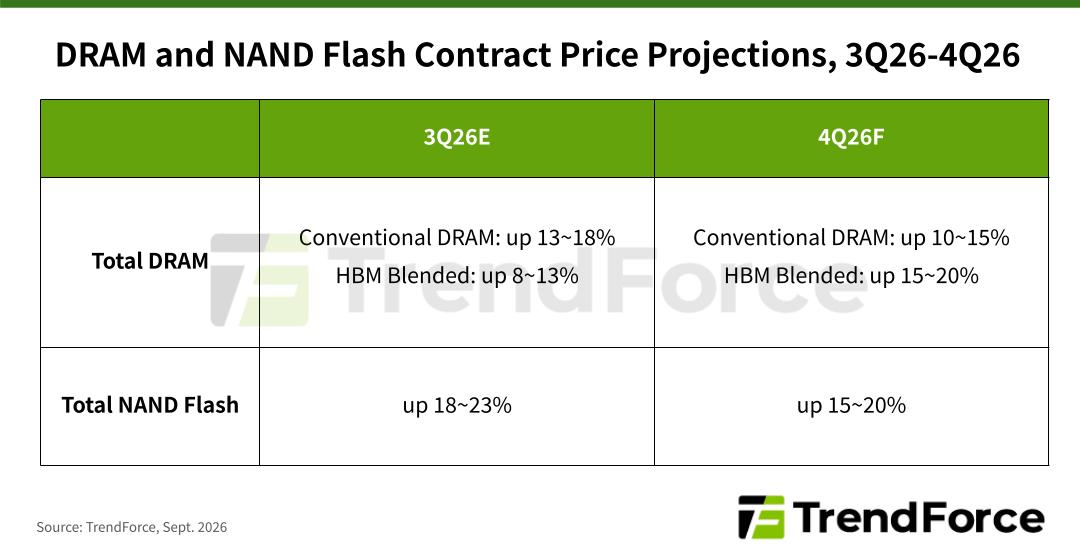
CSP demand keeps 4Q26 DRAM and NAND prices rising, led by AI, while weak consumer demand narrows other gains.
Research Areas:
Industry News