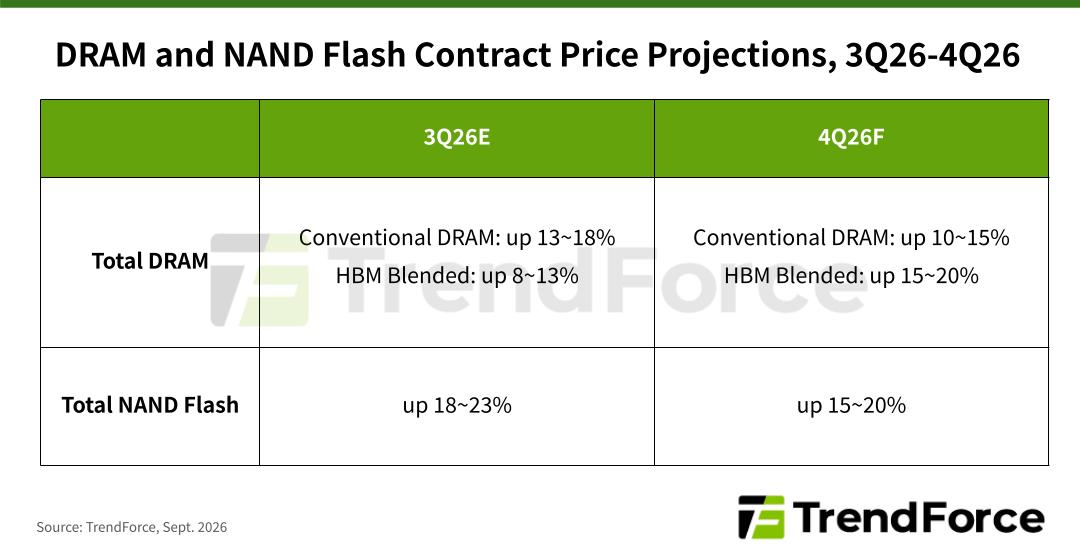
Driven by AGI and Agent AI, North American cloud providers' urgent orders for enterprise SSDs created a structural shortage in high-end storage. Suppliers prioritized capacity for high-margin products, taking strong pricing power and forcing overall contract prices up despite sluggish consumer demand.
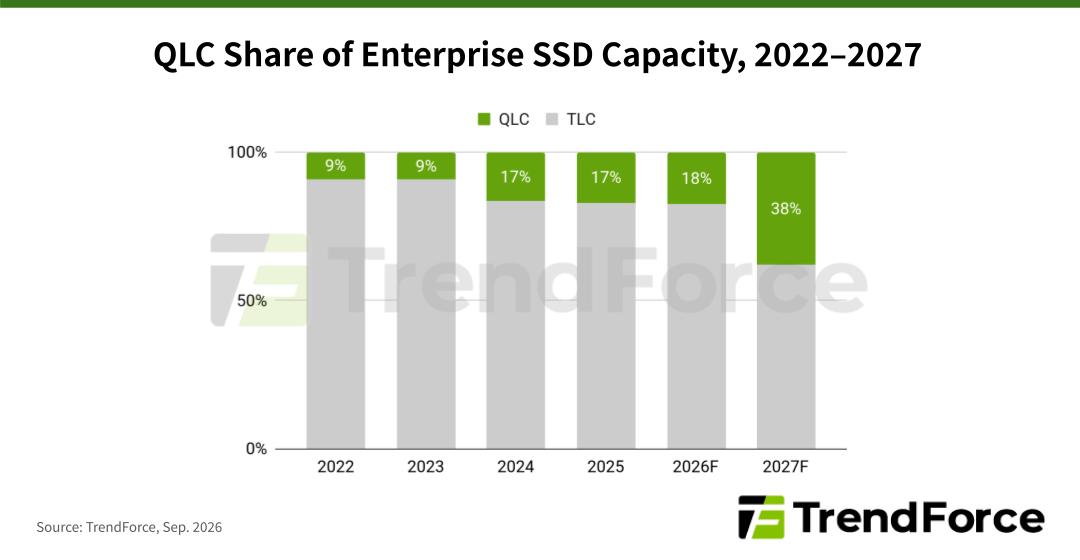
To address the surging KV cache demand driven by the development of agentic AI, cloud service providers are shifting their procurement toward high-performance QLC SSDs. By leveraging their high density and cost efficiency, combined with 'write-once, read-many' operating patterns and advanced attention compression techniques, QLC SSDs effectively overcome capacity bottlenecks while reducing hardware wear, making them the mainstream configuration for advanced storage units.
Winbond has agreed to acquire Infineon's NOR Flash and F-RAM businesses for more than US$1 billion, with closing targeted for 2H27. The deal brings automotive qualifications and high-density products, lifting Winbond's combined share to global No.1 with sharply expanded monthly capacity, turning the industry from a multi-player field into a single leader and strengthening its position in automotive and high-end AI markets.
2027 NAND splits: enterprise SSDs surge on AI demand, while consumer products face price pressure from oversupply.
CSP QLC demand lifts ESSD contract prices; spot stays weak. Memory cost surge delays AI device capacity upgrades.
Driven by demand for artificial intelligence and cloud services, enterprise storage products are in short supply, driving significant growth in average memory selling prices and total industry revenue. In contrast, consumer electronics demand remains sluggish due to persistently high costs and increasingly conservative stocking strategies, creating a structural supply-demand divergence in the market, with future price increases expected to moderate gradually.
NOR Flash memory is facing a structural imbalance as major international manufacturers reallocate capacity to high-end AI products, contracting supply amid surging demand from servers and automotive applications. Delayed capacity expansions and resource diversion among vendors mean high-density supply shortages remain difficult to bridge, driving prices continuously upward. This profitable cycle is expected to persist through next year and beyond.
Price hikes suppress mobile demand, flattening contract prices while spot market stays weak. NAND controllers are evolving into AI compute layers. Driven by CMX architecture, customized NAND will integrate with AI processors across three phases to break memory bottlenecks.
3Q26 memory contract prices were finalized on strong server and AI demand, while the consumer segment reached a pricing compromise; meanwhile, the spot market remained flat due to weak end-user demand. The emerging HBF technology might bridges the gap between high bandwidth memory and solid-state drives, though cost and technical hurdles will limit its smartphone footprint to premium models and delay data center adoption until validation and standardization progress.
AI agents are driving up demand for KV cache and token storage, reshaping memory architecture. Cost considerations are pushing token storage down from expensive HBM and DRAM to SSDs. NAND suppliers are actively promoting next-generation solutions such as HBF, SCM, and SLC to address endurance and latency challenges, while wafer consumption climbs—making advance investment in leading-edge capacity a key competitive factor.
Research Areas:
Industry News