The Enterprise SSD market saw a strong 3Q25 recovery, with prices and volumes rising due to AI inference and server build-out. Cautious supply combined with explosive demand for ultra-large capacity p...
The NAND Flash industry saw Q3 revenue growth driven by strong enterprise SSD demand from AI servers. ASP rose due to production cuts and higher enterprise SSD mix. For Q4, AI applications and HDD sho...
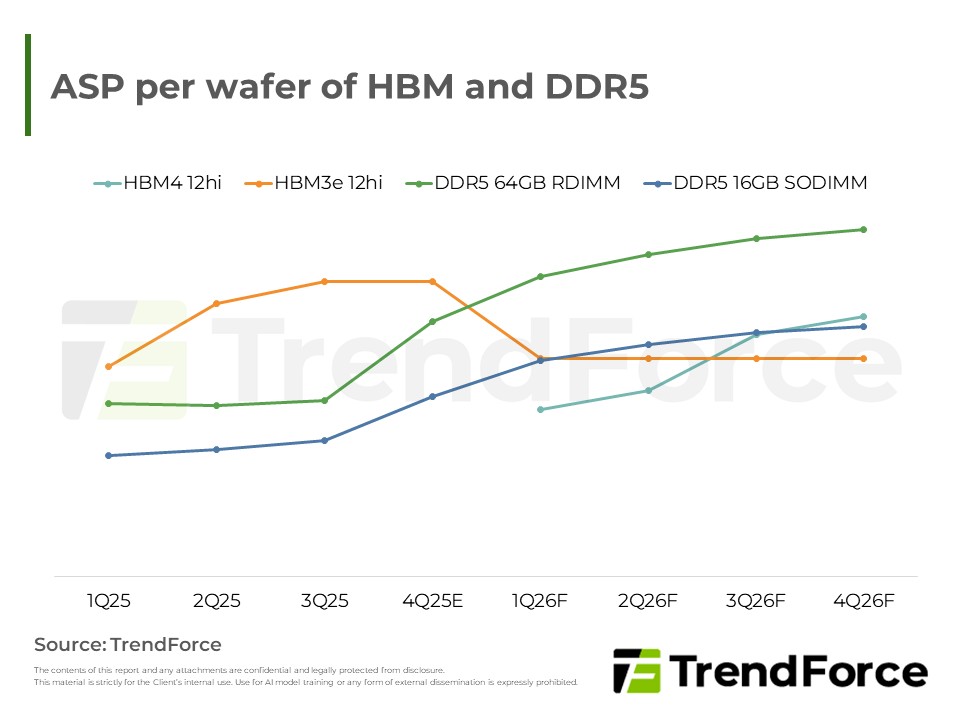
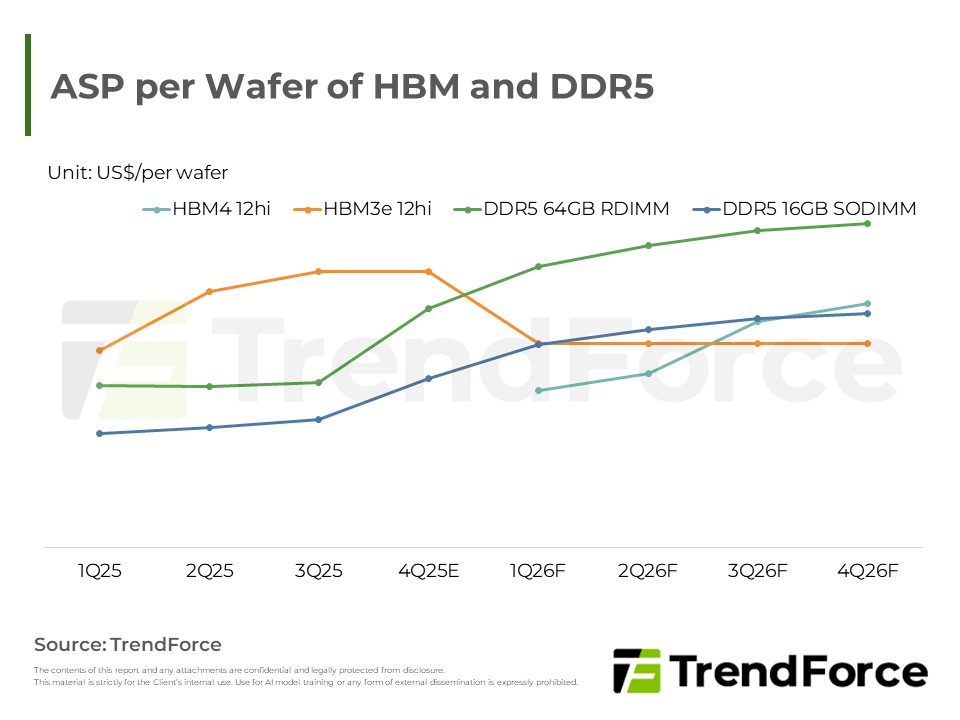
AI demand lifts memory; fab limits push per-wafer pricing. HBM tight; suppliers favor DDR5; extras may rise.
The 4Q25 contract negotiations for mobile DRAM used in smartphones are expected to conclude only after mid-November. Conversely, quotes for NAND Flash products are relatively certain. Due to productio...
Server DRAM prices are projected to surge due driven by tight supply and robust cloud service provider demand. To secure supply, clients are aggressively negotiating long-term agreements, incentivizin...
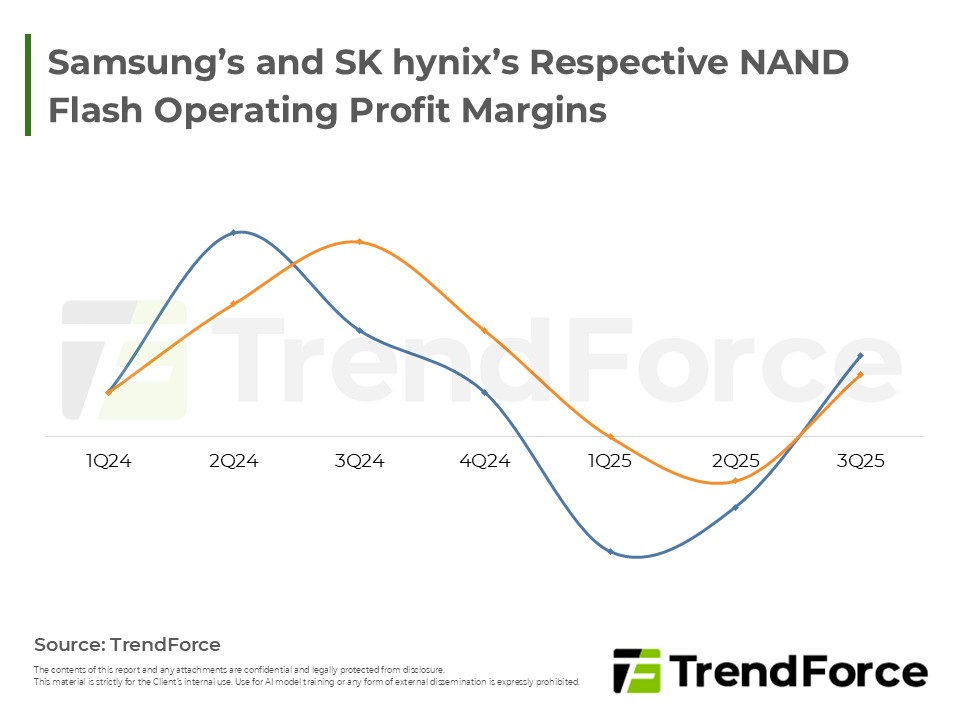
AI is fundamentally transforming the NAND Flash market. Robust enterprise SSD demand is driving up both contract and spot prices. Suppliers control negotiations, market tightness is projected to conti...

AI drives surging memory demand, prompting capex revisions. However, limited cleanroom space and a shift to advanced tech over raw capacity will constrain future bit output growth. Equipment vendors a...
NAND Flash prices surged amid tight supply. Industry investment focuses on advanced tech: hybrid bonding, process upgrades. Overall bit growth limited.
4Q25 mobile DRAM contract prices have risen sharply due to tight supply-demand and competitive bidding among chipmakers, with smartphone applications seeing particularly large increases. This upward t...
Driven by tight original manufacturer supply and aggressive PC OEM procurement, 4Q25 PC DRAM contract prices are projected to rise 25-30%, with spot prices also surging.
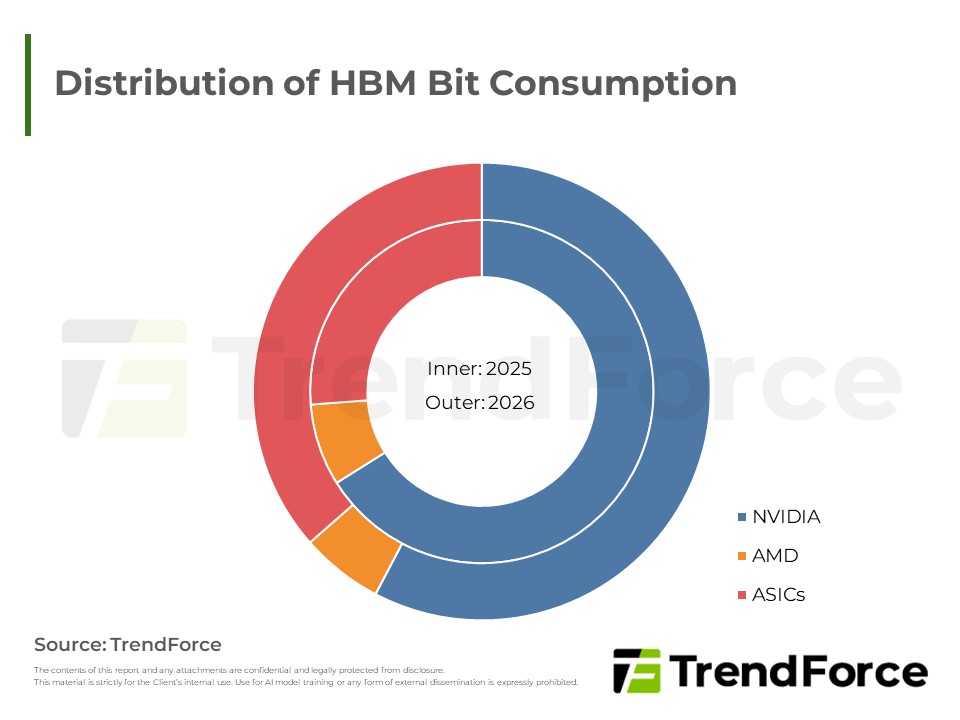
Major suppliers are expanding HBM capacity, with 2025 shipments revised upward. SK hynix leads with 150K TSV capacity, while Micron ramps up its Taiwan facilities. By 2026, all three will begin HBM4 m...

Tariffs and policy changes kept early demand cautious, but cloud expansion and AI investment have lifted memory demand and pricing, tightening DRAM supply. The DDR5 uptrend is established, with profit...
Micron's capacity shift to high-margin products sharply boosted its quotes by limiting standard DRAM supply. SK hynix saw a milder rise. The spot market price increased due to strong demand a...
The 6th to 10th spots of global smartphone ranking for 2025 are occupied by Transsion, Honor, Lenovo, Huawei, and Google in sequential order. Among which, Transsion has slightly dropped in share due t...
Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...






