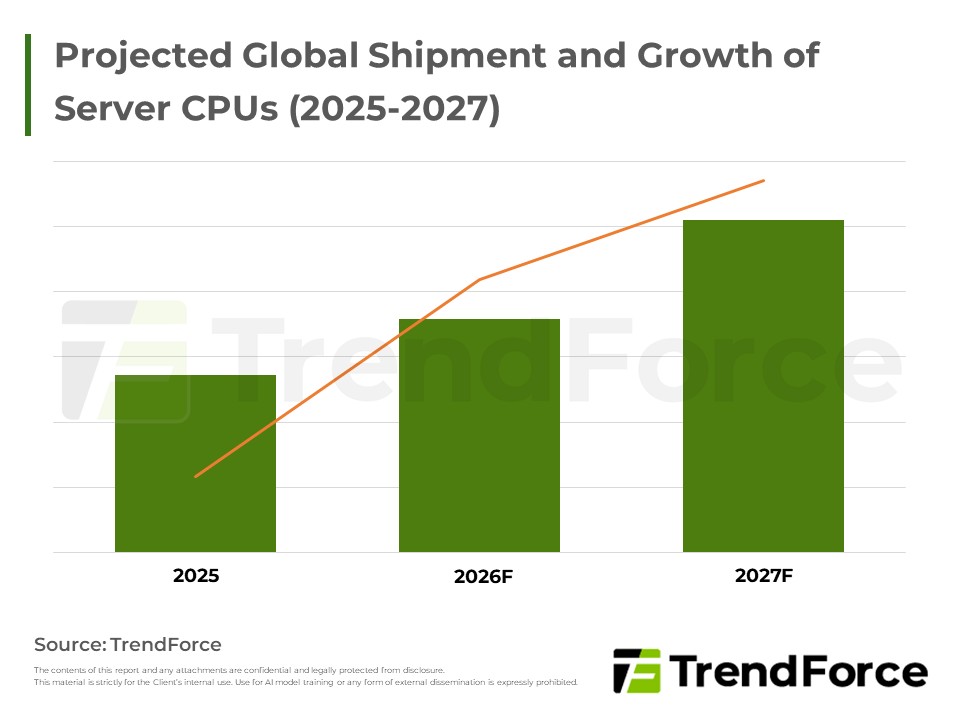
Agentic AI and inference reshape workloads, lifting server CPU demand. Shipments surge as CSP in-house Arm CPUs erode x86 share.
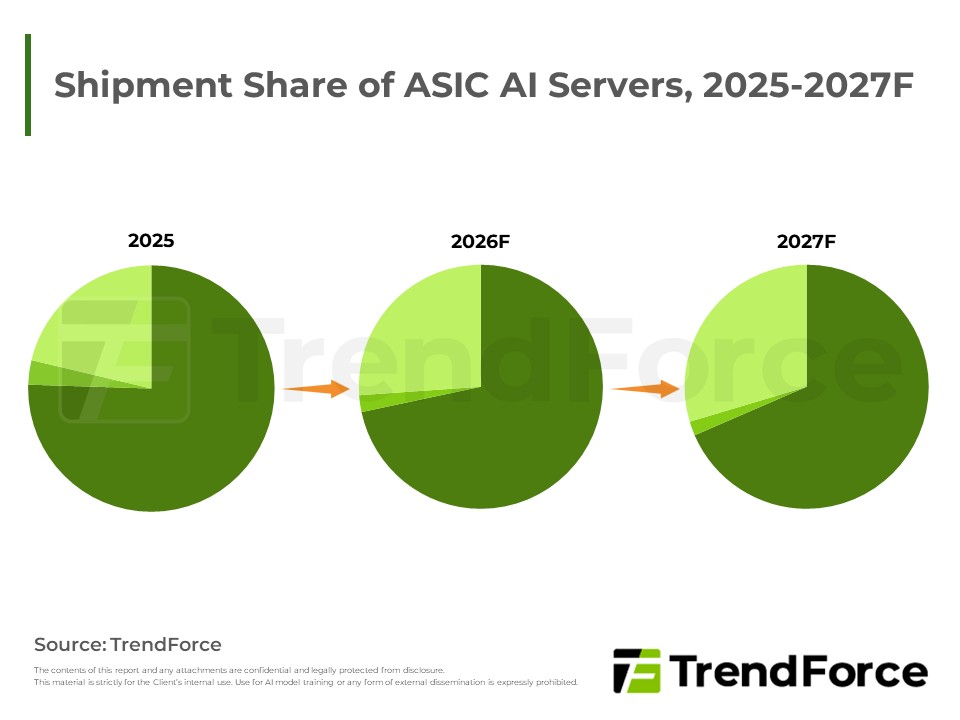
Inference demand drives CSP ASIC growth past GPUs; Google's next TPU adopts EMIB-T, with substrate yield key to cost.
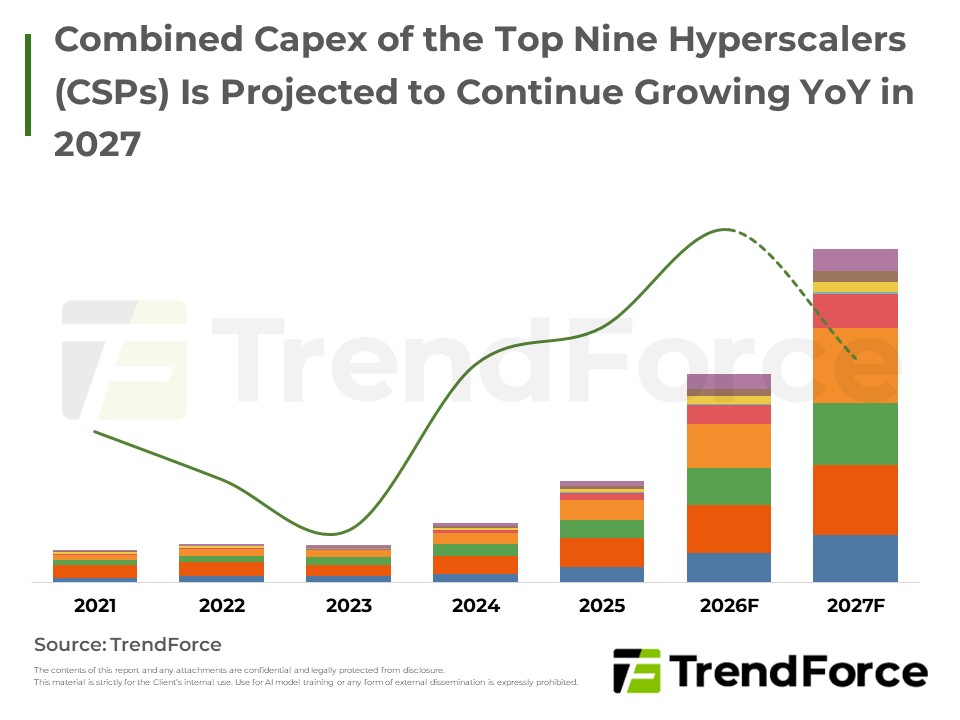
Hyperscaler Capex keeps rising on price hikes and shortages; pricier AI racks drive server value growth over volume.
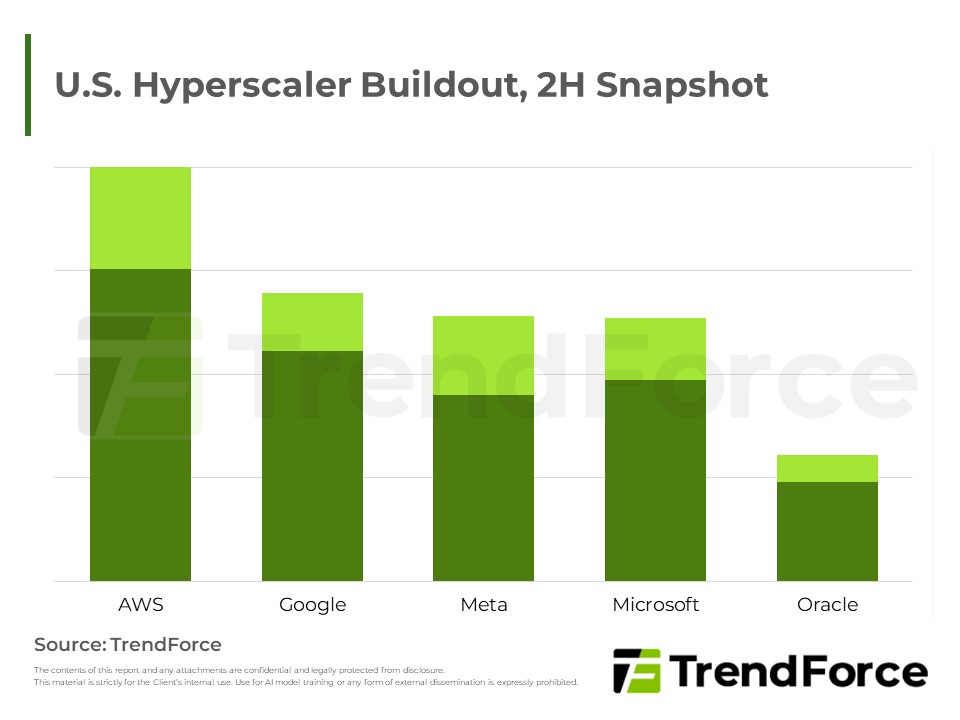
US hyperscalers keep expanding, but midterm-driven backlash may raise costs and delay permits for later-stage projects.
AI chip and server growth accelerates in 2027 on rack-scale systems and ASICs, while HBM and CoWoS supply stays tight.
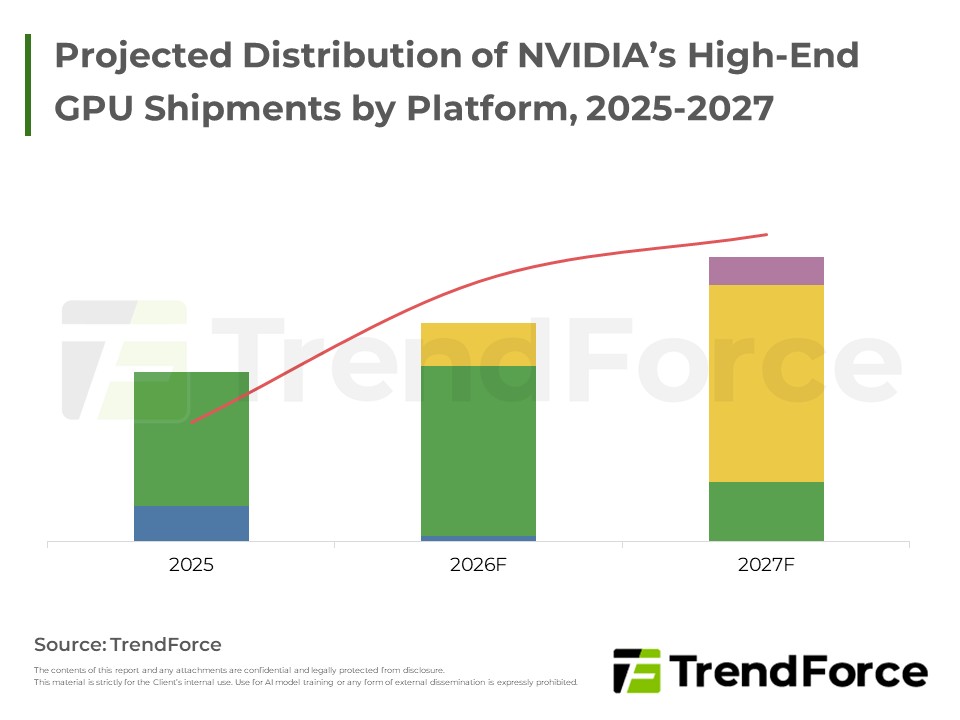
NVIDIA shipments stay Blackwell-led as Rubin's ramp slips into next year on HBM4 snags, keeping HBM the key bottleneck.
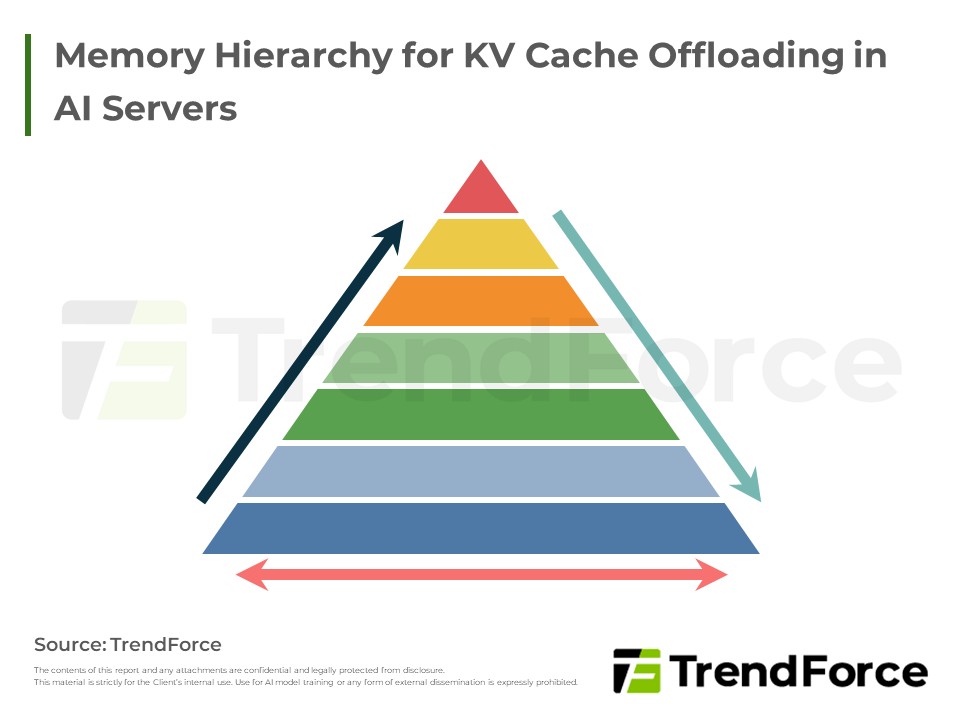
AI chip makers weigh downgrading HBM capacity, hitting capacity for KV cache, lifting offload memory demand, as 8hi stays mainstream.
HBM 4hi samples emerge; low capacity curbs data center use; edge interest stays early, supplier uptake cautious.
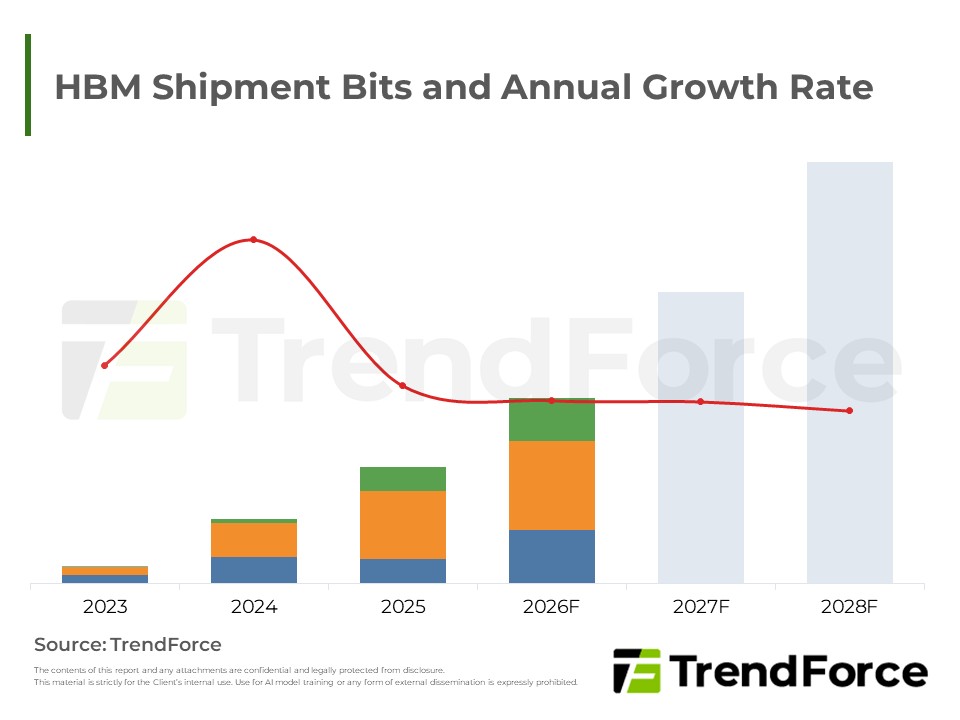
AI demand keeps HBM shipments strong as technology advances and tight supply shifts pricing power toward suppliers.
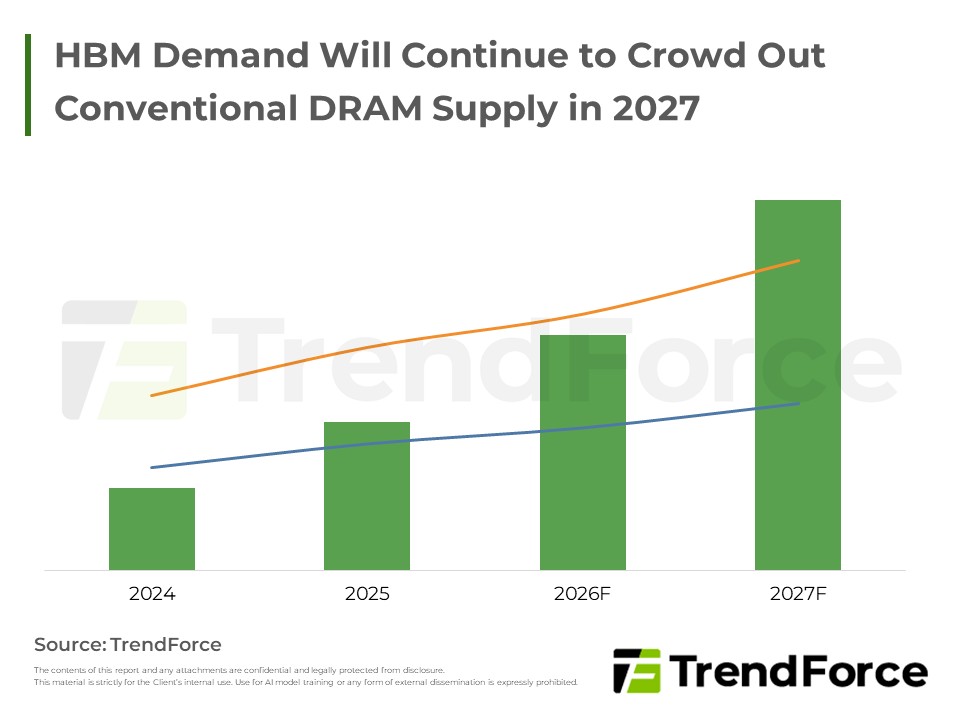
2027 HBM talks remain stalled as suppliers push steep price hikes amid AI-driven DRAM crowd-out and tighter capacity.
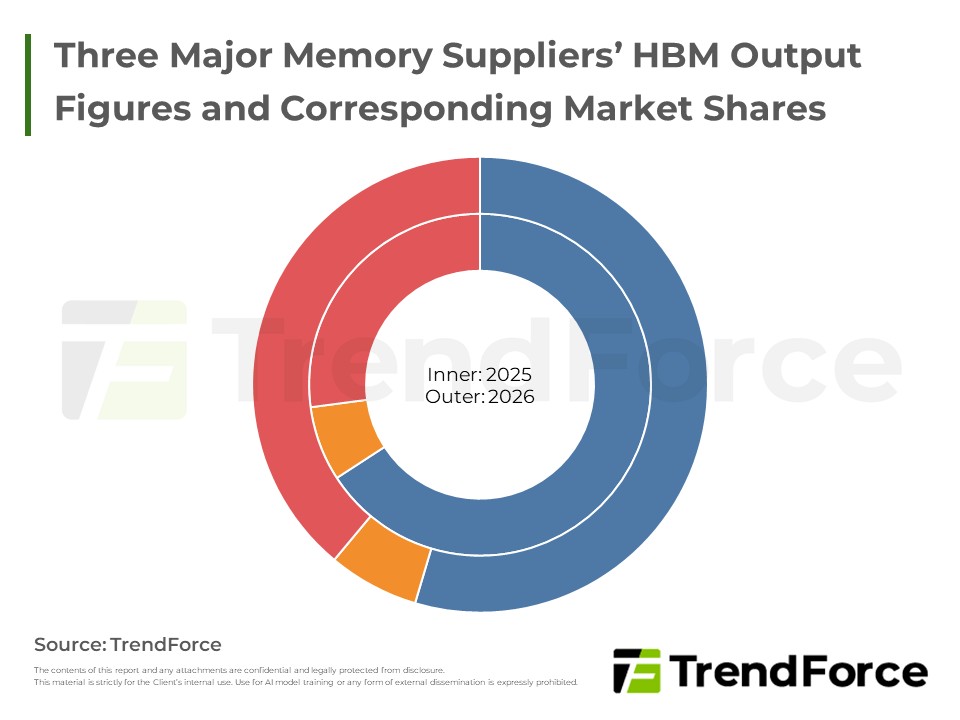
HBM supply expands as shares shift; 2026 is a pricing pause, 2027 brings a sharp ASP surge as HBM4 rises.
TrendForce: NVIDIA still weighs Rubin Ultra HBM options as tight DRAM supply pushes suppliers toward much higher prices.
JEDEC-defined SPHBM4 frees HBM from the interposer, trading latency and power for cost and layout.
AI chip demand surges in 2026, with high-end GPUs dominating. NVIDIA leads, ASICs gain share, liquid cooling expands, and AI server value hits record highs.
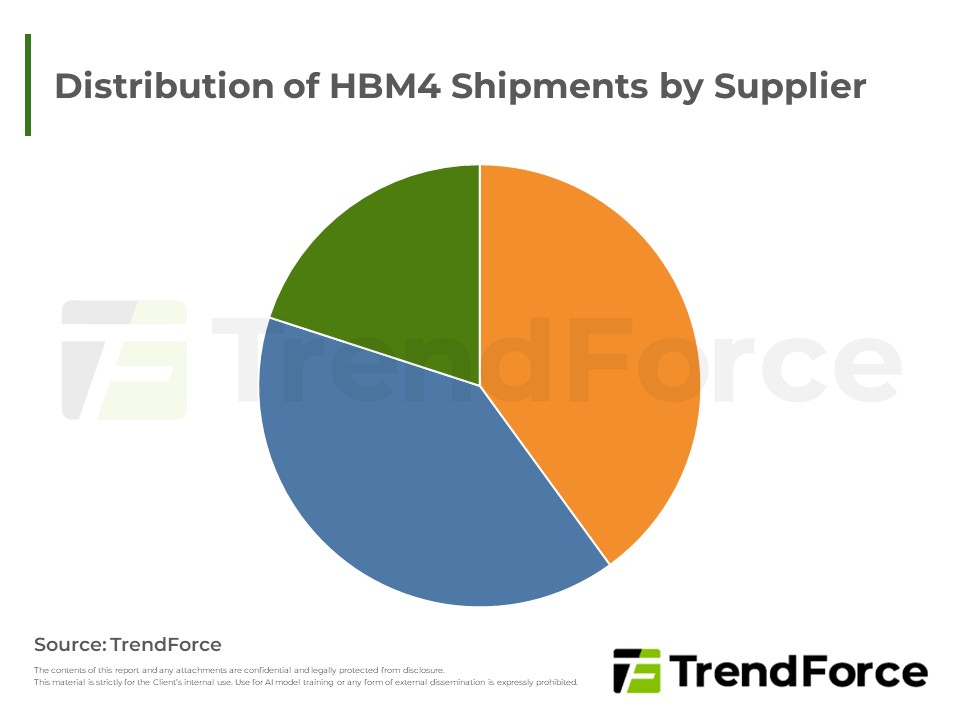
Diverging HBM4 certification timelines are reshaping 2026 market share, with Samsung gaining ground as SK hynix faces delays.






