NOR Flash Price Trends Diverge in 2H26, with High-Capacity Products Poised for 90–110% Increases, Says TrendForce
TrendForce’s latest memory industry research indicates that the NOR Flash market is undergoing its most significant structural shift in supply and demand in nearly a decade. AI-related products are absorbing a substantial share of production capacity, leaving suppliers limited room to increase NOR Flash bit output even as demand for high-end applications continues to grow.
Supply and demand are therefore expected to remain imbalanced in the second half of 2026, keeping overall contract prices elevated. Prices for high-capacity products could even double.
TrendForce notes that although Taiwanese and Chinese suppliers have increased CapEx and are expanding production, new capacity cannot immediately translate into market-ready supply. New output must first undergo process migrations, yield ramp-ups, product qualification, and customer design-in. As a result, supply shortages in the mid- and high-capacity segments are unlikely to ease in the near term.
Among major NOR Flash suppliers, market leader Winbond is expected to post the strongest bit growth in 2026, primarily driven by the full ramp-up of 45nm NOR products and the benefits of process migrations to 25nm and 20nm. Although wafer starts are increasing only modestly, NOR bit output per wafer is rising significantly.
Second-ranked GigaDevice offers a comprehensive portfolio ranging from 512Kb to 2Gb and is actively upgrading process technologies for products of 32Mb and above in 2026. However, transferring some NOR foundry production to overseas fabs created a transition period that constrained effective output in the first half of the year. Capacity is expected to recover gradually in the second half.
MXIC, meanwhile, is prioritizing its additional 12-inch capacity in 2026 for NAND and eMMC, where supply is even tighter. This has limited growth in NOR wafer starts, leaving NOR bit growth significantly below the increase in the company’s overall production capacity.
AI and aerospace communications emerge as major new sources of demand in 2026
TrendForce indicates that NOR Flash demand continues to grow despite limited additional supply. Beyond traditional applications such as advanced driver assistance systems (ADAS), digital cockpits, and industrial control, AI and aerospace communications are emerging as the primary sources of incremental demand in 2026.
An AI server, for example, requires three to five times as much NOR Flash as a conventional server. AI servers also incorporate large numbers of retimer chips, each requiring dedicated NOR Flash to load microcode, further boosting demand for high-capacity and Octal SPI NOR.
Additionally, local inference devices such as edge AI systems, AI PCs, and robots are driving several-fold increases in model firmware size, further increasing demand for high-density NOR Flash.
In LEO satellites and aerospace electronics, core satellite chipsets require highly reliable NOR Flash for fast boot-up and firmware backup. Ground receiving antennas also incorporate NOR Flash to support real-time processing and over-the-air (OTA) firmware updates. Aerospace-grade NOR must also withstand radiation and extreme temperature fluctuations, creating significant technical barriers to entry and strengthening the position of Taiwanese and U.S. suppliers.
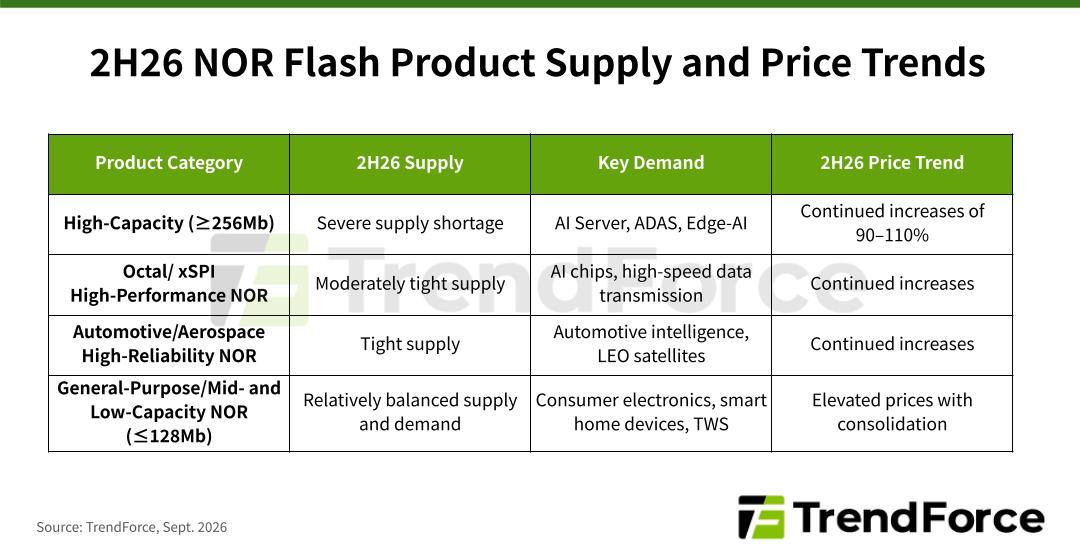
TrendForce notes that NOR Flash contract prices rose by a cumulative average of 100–120% in the first half of 2026. Price trends are expected to diverge across capacity segments in the second half. Products with capacities of 256Mb and above will continue to benefit from strong demand from AI servers and automotive applications. With leading Taiwanese suppliers able to add only limited bit supply, average prices for these products could rise another 90–110% in 2H26.
For mid- and low-capacity products of 128Mb and below, additional capacity from Chinese suppliers is gradually coming online. Price increases for consumer-grade products are therefore expected to moderate, with prices entering a period of consolidation at elevated levels. TrendForce estimates that prices in this segment will rise 10–20% in 4Q26.
For more on the latest technology industry news and trends, please visit News.