[Insights] Memory Spot Price Update: NAND Spot-Contract Price Gap Exceeds 20% amid Weak Demand
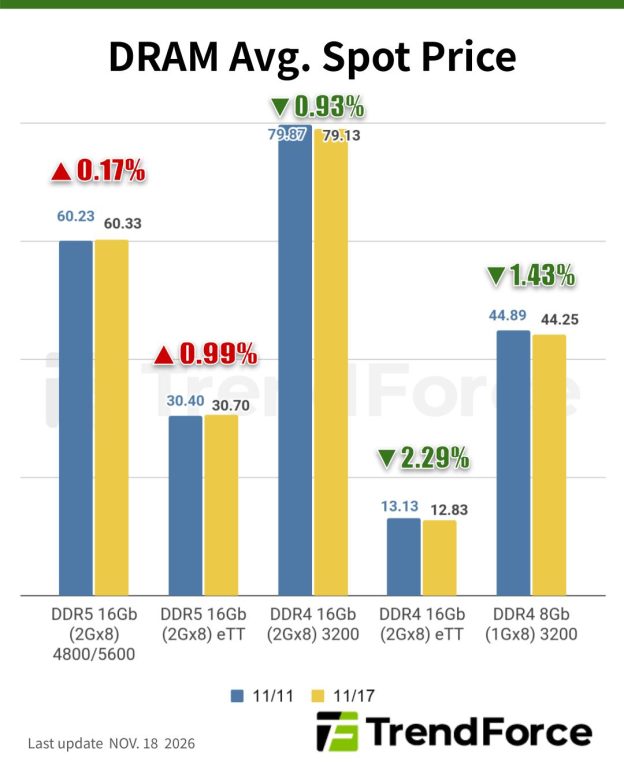
According to TrendForce’s latest memory spot price trend report, DRAM buyers remain on the sidelines despite suppliers’ willingness to offer lower prices amid sluggish demand. While branded DDR5 spot prices held largely steady, DDR4 remained under pressure, with mainstream DDR4 1Gx8 3200MT/s chips slipping 1.43%. In NAND Flash, weak demand is prompting sellers to lower prices to clear inventory, while subdued spot buying has left spot and contract prices more than 20% apart. Details are as follows:
DRAM Spot Price:
The DRAM spot market remains sluggish this week. Due to weak downstream demand and unclear future pricing trends, buyers have adopted an even more cautious stance with respect to procurements. Although some DRAM suppliers are under pressure to ship products and more willing to release inventory at lower prices, buyers’ appetite is still weak, and quote inquiries are largely aimed at testing prices and confirming market conditions. By product category, spot prices of branded DDR5 chips have been mostly stable, while spot prices of DDR4 chips have been relatively weak. The average spot price of the mainstream chips (i.e., DDR4 1Gx8 3200MT/s) slightly decreased by 1.43% from US$44.89 last week to US$44.25 this week (November 17).
NAND Flash Spot Price:
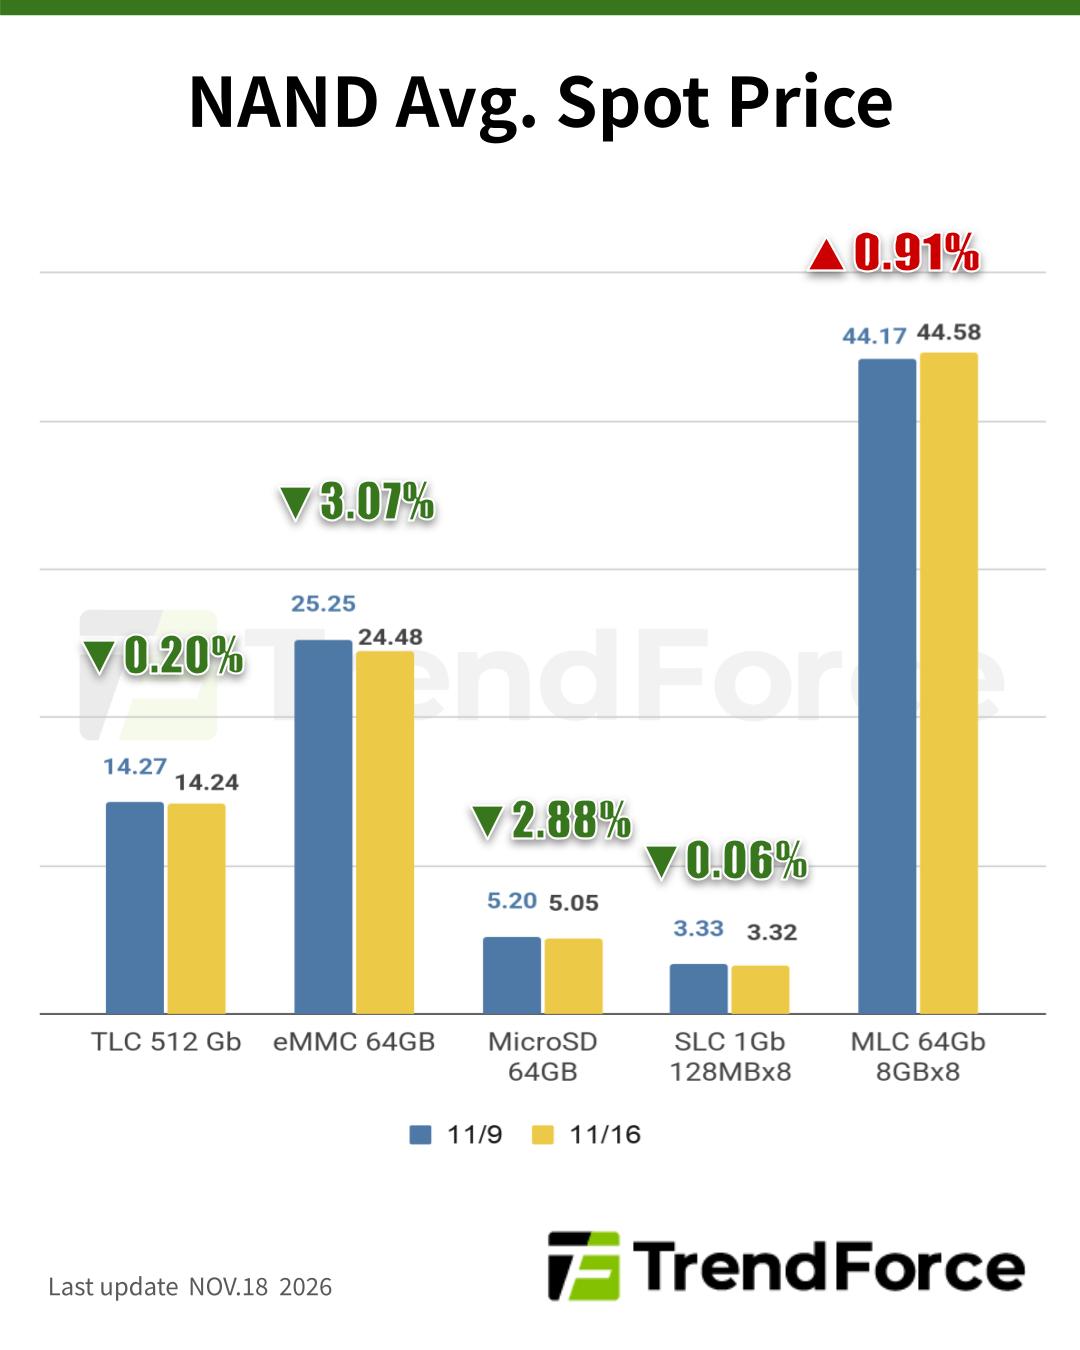
Weak demand has triggered pressure of inventory digestion in the channel. Sellers are inclined to cut prices to move inventory, while weak buyer sentiment in the spot market has widened the gap between spot and contract prices to over 20%, in turn constraining contract price negotiations. 512Gb TLC wafers dropped by 0.20% this week (November 9), with average quotations coming to US$14.238.