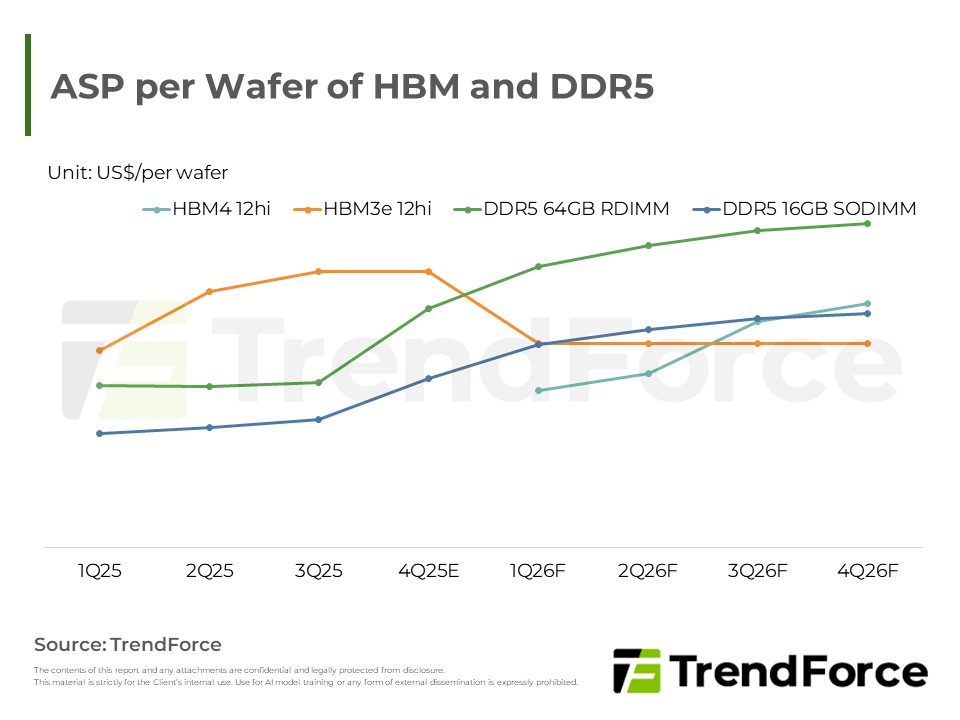
Server DRAM prices are projected to surge due driven by tight supply and robust cloud service provider demand. To secure supply, clients are aggressively negotiating long-term agreements, incentivizin...
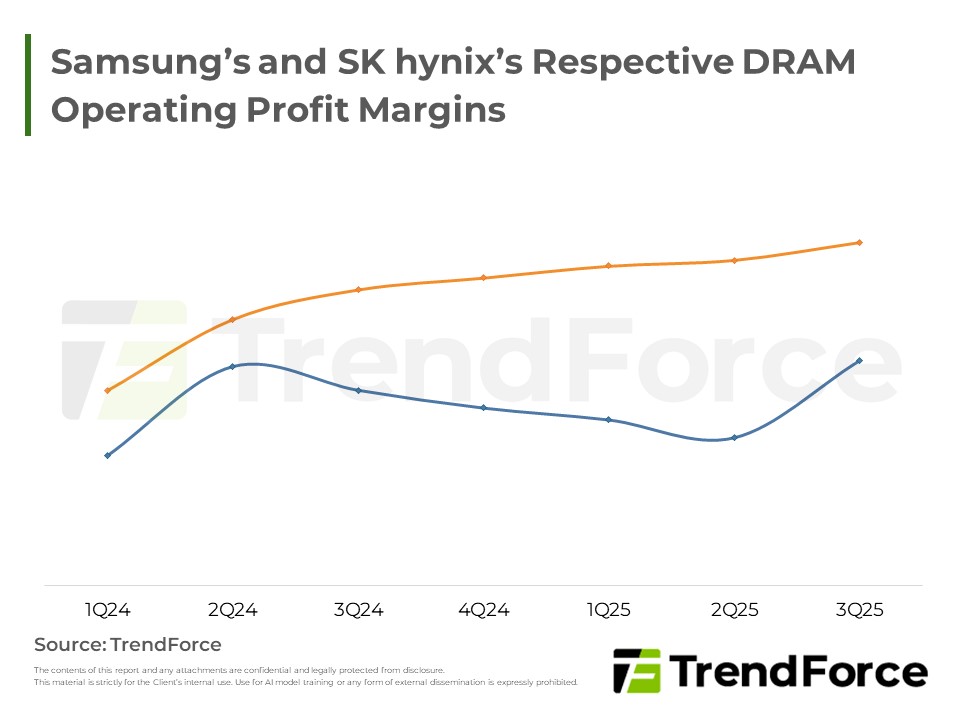
The DRAM market is experiencing a significant price surge driven by robust demand from Cloud Service Providers and AI applications, coupled with tight supply. Both contract and spot prices are rising...
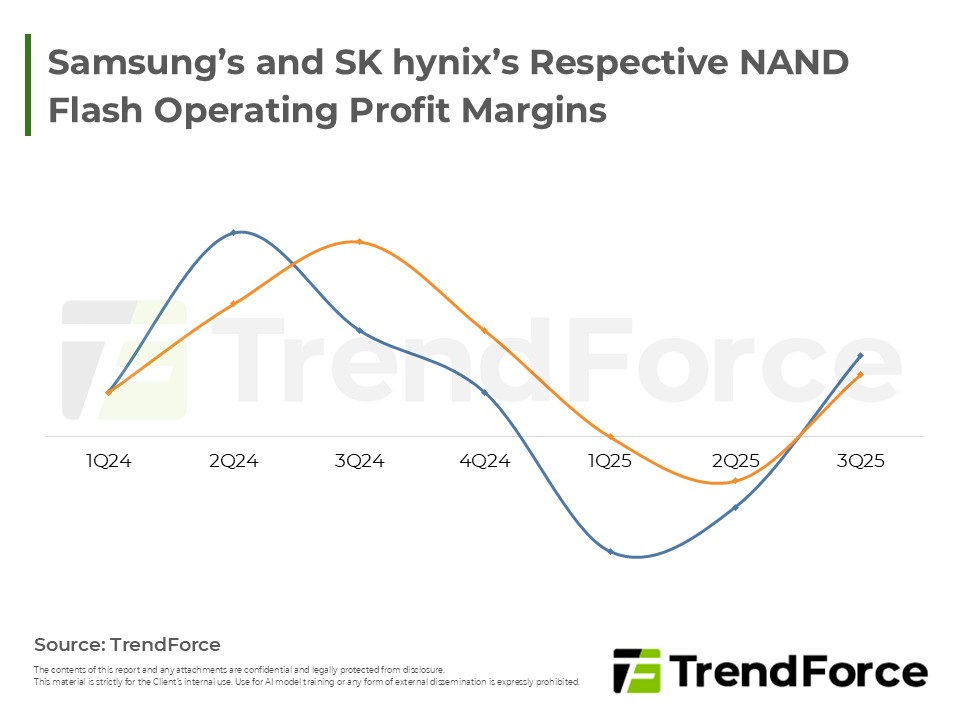
AI is fundamentally transforming the NAND Flash market. Robust enterprise SSD demand is driving up both contract and spot prices. Suppliers control negotiations, market tightness is projected to conti...
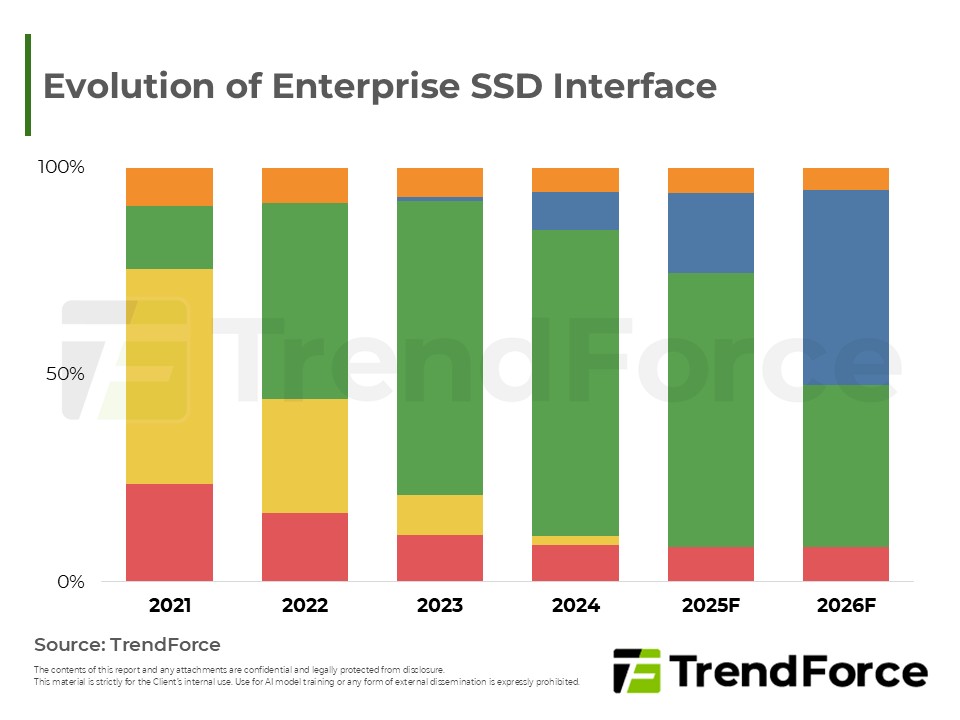
AI's evolving demands shift storage from HDDs (high latency) to SSDs (speed, low latency). SSDs offer superior performance and TCO benefits, accelerating their adoption in AI infrastructure.
Advanced-process expansion and layouts for both Chinese foundries and GlobalFoundries, stressing supply autonomy and cross-border investment amid strategic shifts for long-term needs.

AI drives surging memory demand, prompting capex revisions. However, limited cleanroom space and a shift to advanced tech over raw capacity will constrain future bit output growth. Equipment vendors a...
DRAM prices are surging across contract and spot markets due to severe supply constraints. Capital expenditure shifts to advanced products, limiting traditional bit growth.
NAND Flash prices surged amid tight supply. Industry investment focuses on advanced tech: hybrid bonding, process upgrades. Overall bit growth limited.
2024 SSD market faced conservative demand; Kingston led, Chinese brands rose, intensifying the "big get bigger" trend. Module makers differentiated, targeting new markets, wi...
4Q25 mobile DRAM contract prices have risen sharply due to tight supply-demand and competitive bidding among chipmakers, with smartphone applications seeing particularly large increases. This upward t...
Strong CSP demand is driving server DRAM prices significantly higher, with 4Q25 increases revised upwards. CSPs are proactively securing 2027 supply, incentivizing manufacturers to boost capacity, sig...
Driven by tight original manufacturer supply and aggressive PC OEM procurement, 4Q25 PC DRAM contract prices are projected to rise 25-30%, with spot prices also surging.
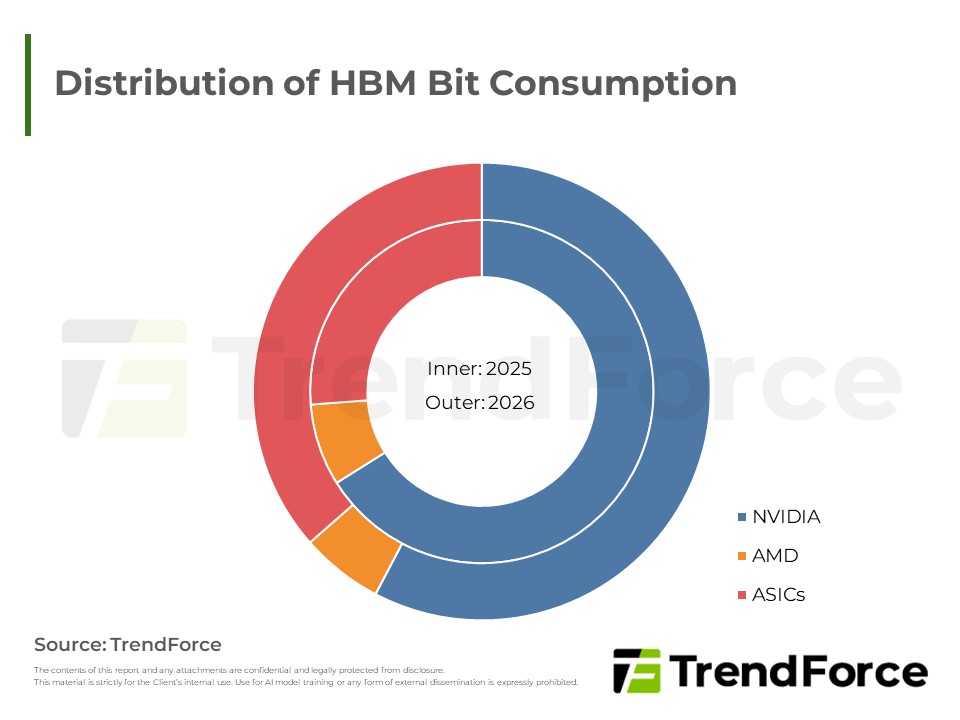
Major suppliers are expanding HBM capacity, with 2025 shipments revised upward. SK hynix leads with 150K TSV capacity, while Micron ramps up its Taiwan facilities. By 2026, all three will begin HBM4 m...
CSP demand and panic buying are propelling DRAM price surges, creating a seller's market. Consumer DRAM supply tightens next year due to major manufacturer exits and capacity shifts, ensuring con...
October NAND Flash wafer prices soared significantly. Robust AI/enterprise SSD demand and manufacturers' supply prioritization caused severe shortages and 'prices without goods.' Furthe...






