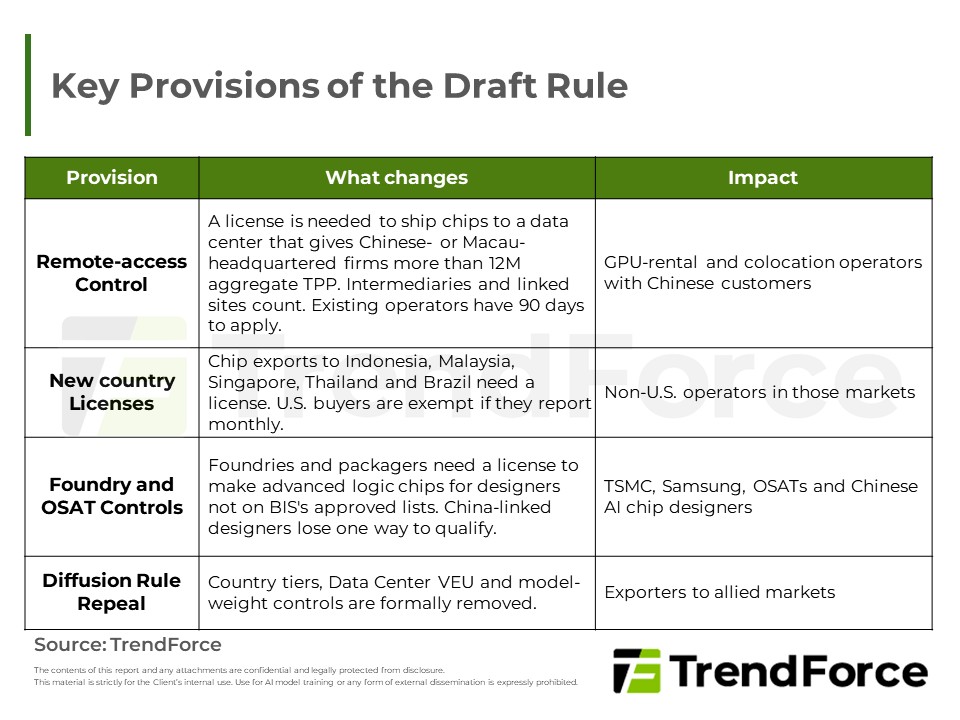
US remote-access rule extends chip controls to compute use, hitting Southeast Asian GPU clouds serving Chinese tenants.
2027 AI server shipments stay solid on locked-in builds; 2028 slows on regulation and NVIDIA changes, ASICs top GPUs.
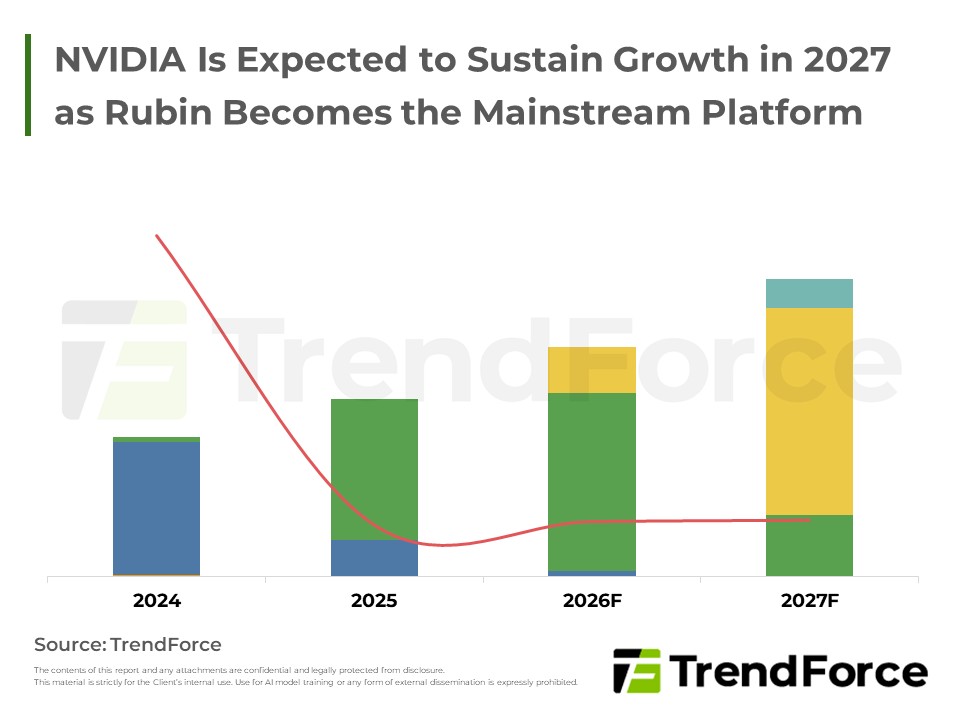
NVIDIA's leadership change spares AI server orders for now; Rubin ramps up, while ASIC and AMD gain share amid geopolitical risks.
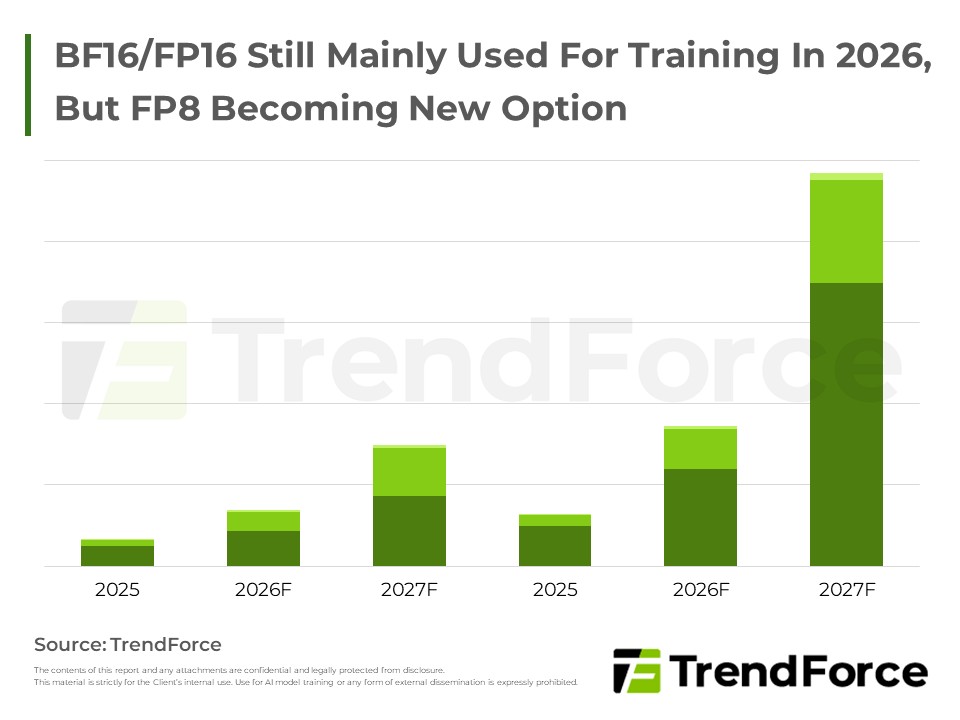
AI chip volumes keep rising in 2027, more than doubling compute; FP4, MoE and model tiering cut costs, but post-2028 oversupply looms.
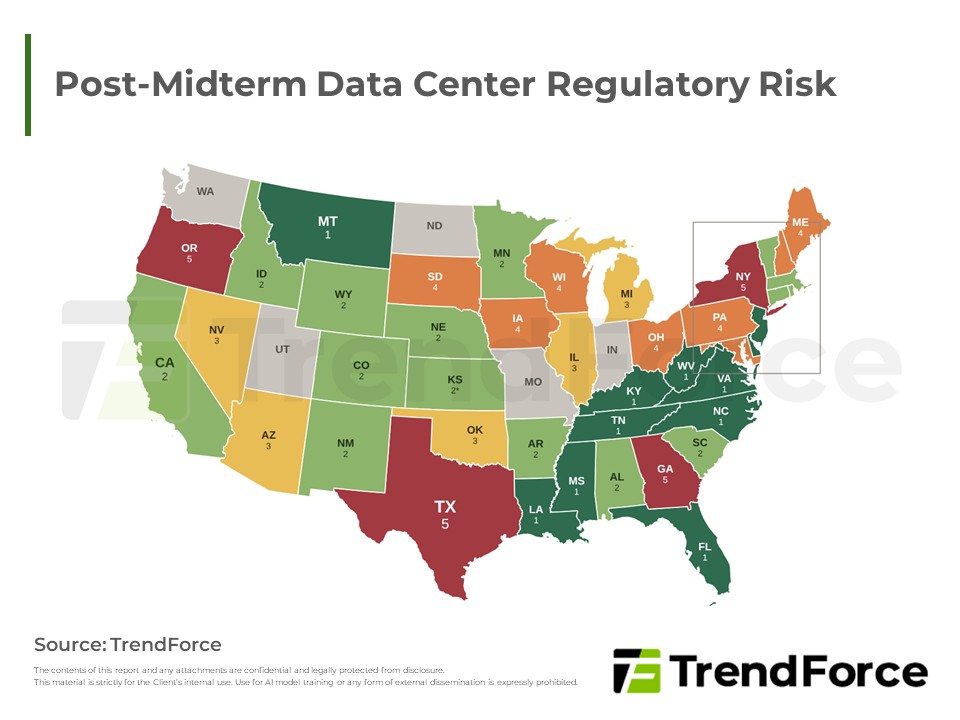
Post-midterm moratorium pledges in key states raise delay risk for 2028+ US data center builds; hyperscalers are best placed to adapt.
Global Server Market – Trends and Outlook for 4Q26
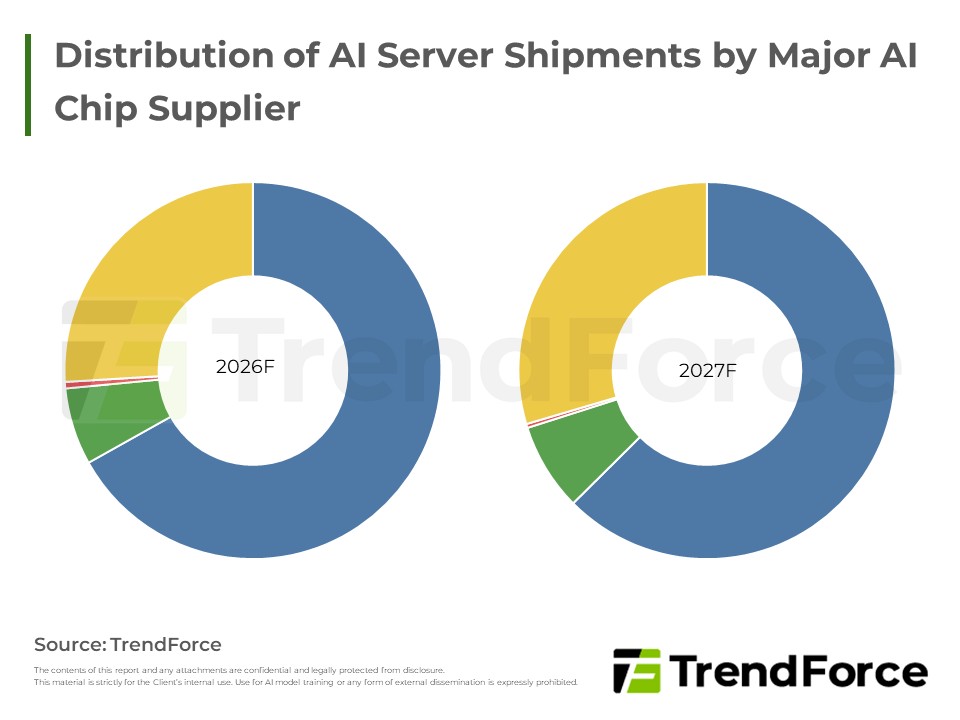
CSP capex fuels AI servers; NVIDIA leads as Rubin follows Blackwell, while ASICs, liquid cooling and HBM4 surge.
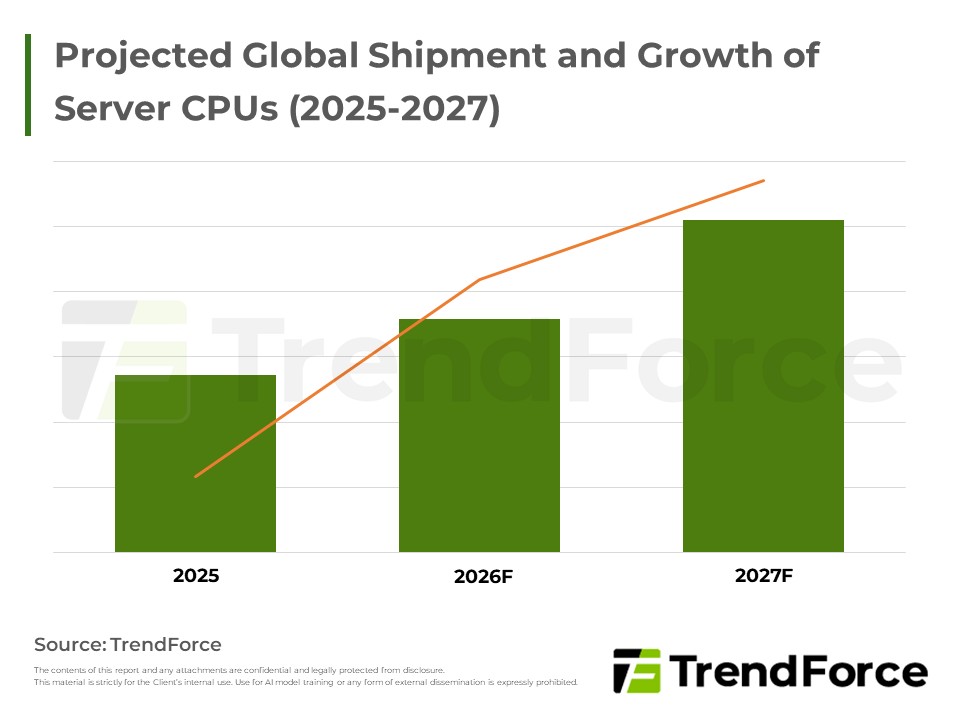
Agentic AI and inference reshape workloads, lifting server CPU demand. Shipments surge as CSP in-house Arm CPUs erode x86 share.
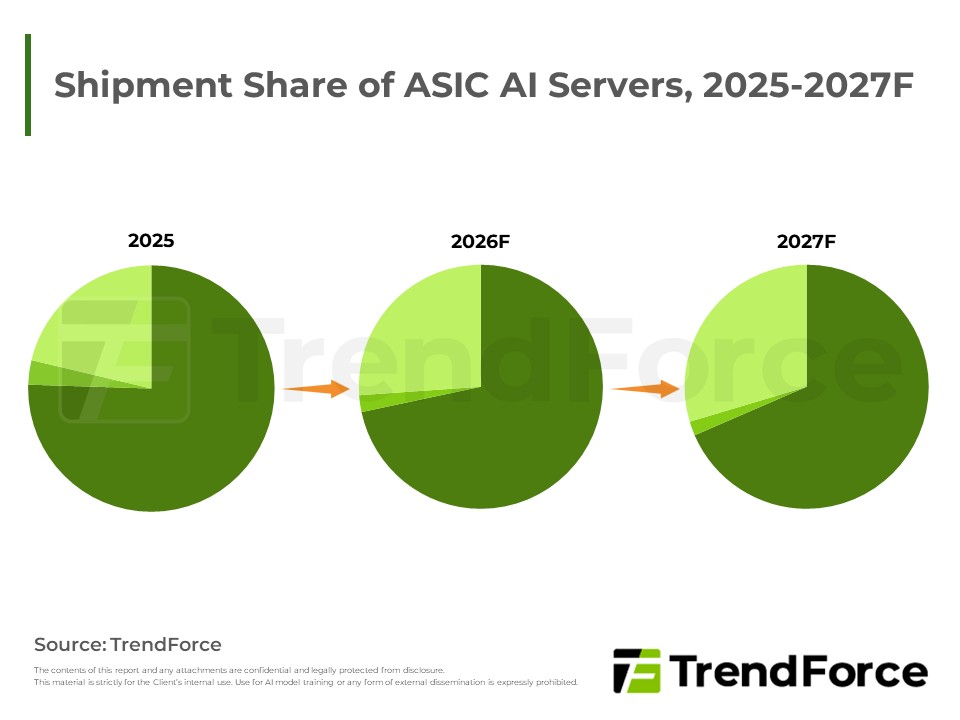
Inference demand drives CSP ASIC growth past GPUs; Google's next TPU adopts EMIB-T, with substrate yield key to cost.
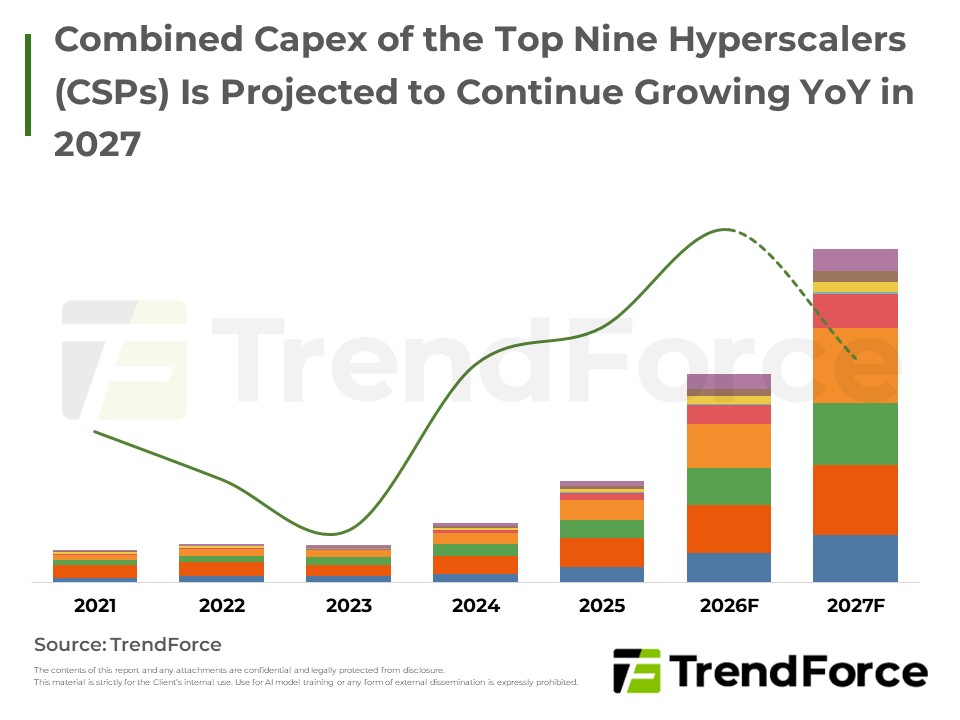
Hyperscaler Capex keeps rising on price hikes and shortages; pricier AI racks drive server value growth over volume.
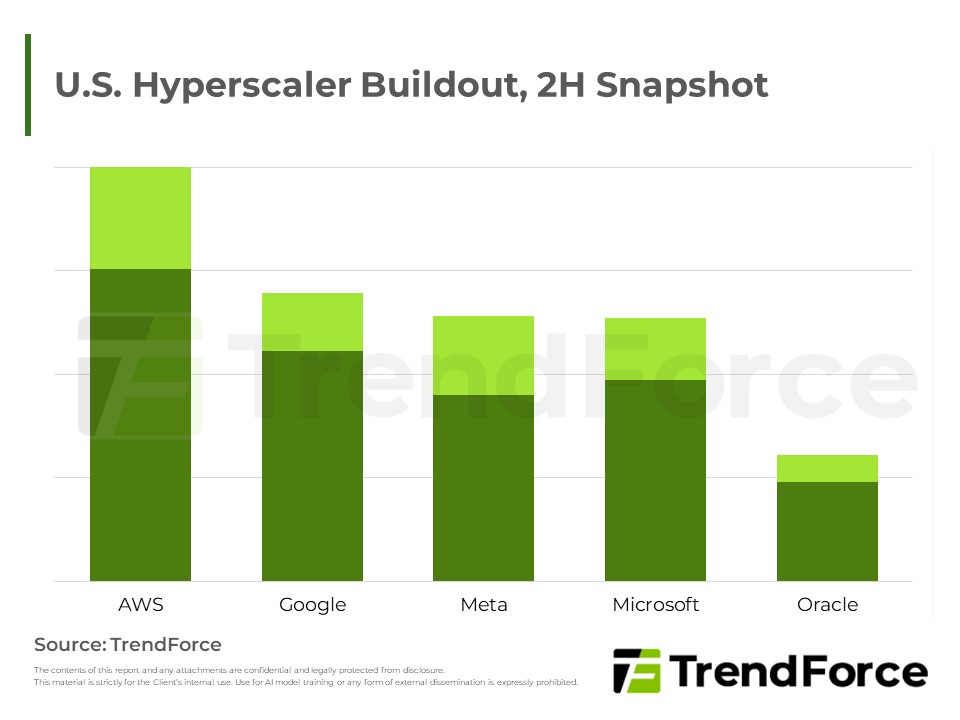
US hyperscalers keep expanding, but midterm-driven backlash may raise costs and delay permits for later-stage projects.
AI chip and server growth accelerates in 2027 on rack-scale systems and ASICs, while HBM and CoWoS supply stays tight.
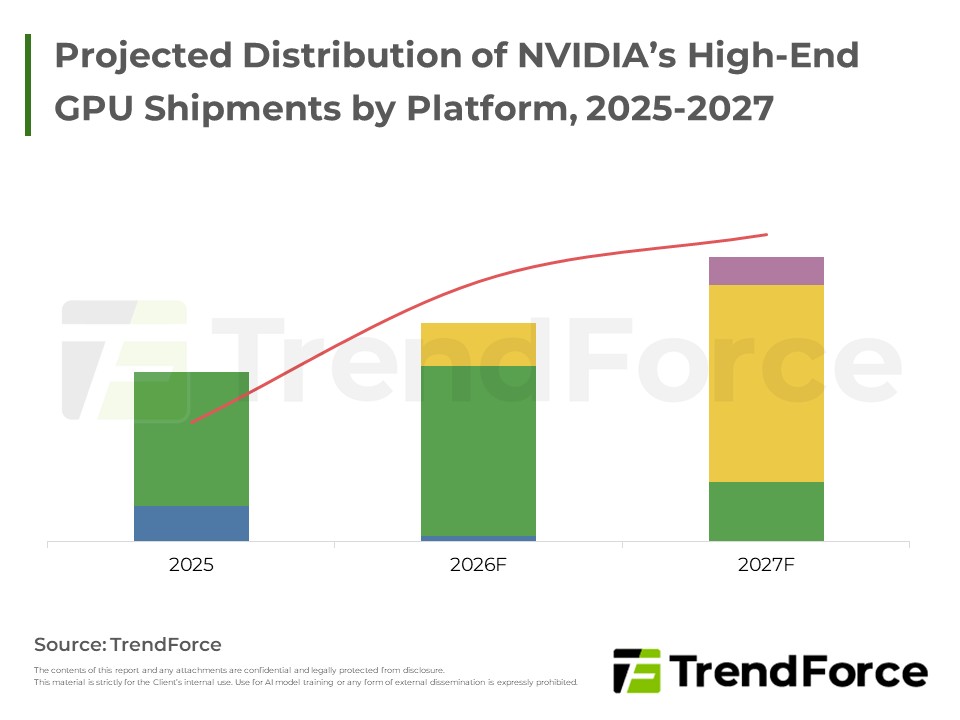
NVIDIA shipments stay Blackwell-led as Rubin's ramp slips into next year on HBM4 snags, keeping HBM the key bottleneck.
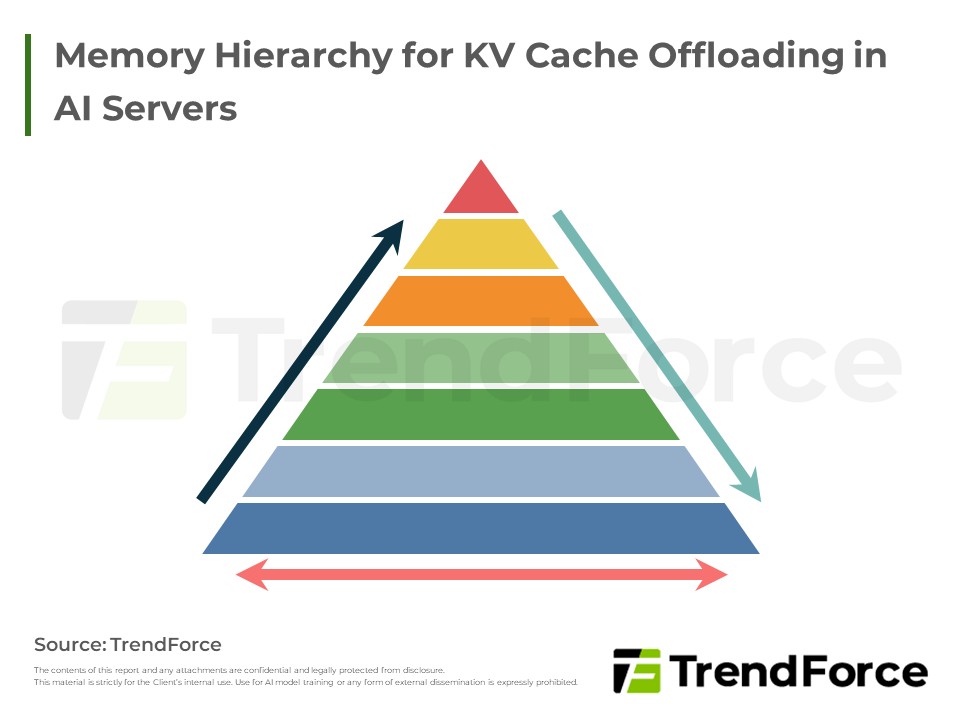
AI chip makers weigh downgrading HBM capacity, hitting capacity for KV cache, lifting offload memory demand, as 8hi stays mainstream.
Driven by AI Agent computing expansion and third-party outsourcing demand, server shipments and CPU requirements have been revised upward. Memory suppliers face severe capacity constraints due to shif...


