[News] Samsung May End UMC’s Galaxy DDI Exclusivity by Adding GlobalFoundries as Mature-Node Capacity Tightens
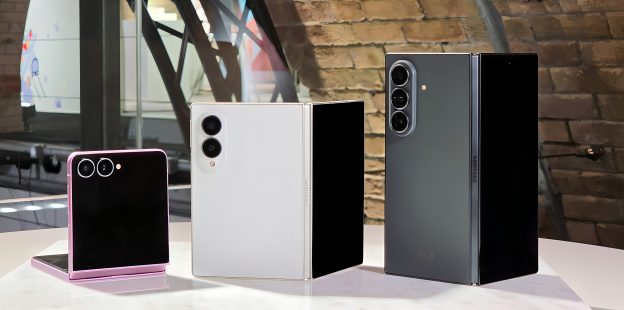
Tightening mature-node foundry capacity could be prompting Samsung Electronics to explore additional suppliers for its smartphone display chips. According to ZDNet, citing industry sources, Samsung is considering adding GlobalFoundries as a second foundry partner for display driver ICs (DDIs) used in its OLED Galaxy smartphones, potentially ending UMC’s exclusive role in manufacturing the chips. GlobalFoundries-produced DDIs could appear in Galaxy smartphones as early as late 2027.
Some lower- and mid-range Galaxy A series models could be the first to adopt the chips. Samsung is reportedly evaluating GlobalFoundries’ 22nm or 28nm nodes for DDI production, with compatible manufacturing facilities in Singapore and Germany, the report notes.
The potential shift comes as mature-node demand has outpaced supply since the second half of 2025, limiting UMC’s ability to accommodate additional orders. According to ZDNet, Samsung reportedly requested expedited DDI production for its Galaxy Z Fold8 after demand for the foldable smartphone exceeded expectations following its July unveiling. However, UMC was unable to fulfill the request because its 22nm DDI production capacity had already reached its limit.
Accommodating Samsung’s request would have required UMC to adjust production schedules for other customers. As a result, Samsung cut its planned Galaxy Z Fold8 component production volume for September by 10%, shifting the deferred volume to October, the report notes.
UMC Capacity Tightens as Mature-Node Pricing Pressure Builds
UMC’s broader capacity outlook also points to tightening supply. According to Economic Daily News, institutional investors expect the foundry’s 12-inch capacity utilization to reach 93% by the end of 2026, supported by rising 22/28nm DDI orders from Samsung System LSI and Novatek, alongside demand for Apple Mac-related chips manufactured on 55/65nm nodes.
The tightening supply reflects a broader shift in mature-node manufacturing. TrendForce notes that foundries are increasingly allocating capacity to higher-margin AI-related applications, including power management ICs, power devices, interposers, and optical communication components, while reducing capacity allocated to lower-margin products such as display driver ICs and CMOS image sensors.
The shift is also adding pressure to foundry pricing. According to TrendForce, some capacity-constrained 12-inch mature nodes have shown signs of 5–10% price increases between the second and third quarters of 2026, with broader price hikes expected in 2027.
Read more
- [News] TSMC’s $2B Silicon Interposer Deal with GF Could Fast-Track U.S. Packaging to 1H28, Free Up Fab Capacity
- [News] PSMC Reportedly Becomes Intel’s Exclusive EMIB Silicon Capacitor Supplier; UMC May See Order Boost
(Photo credit: Samsung)