
The iPhone 17 lineup officially welcomes a new ultra-thin flagship model. Apart from the base variant, all models in the series feature notable upgrades in design and hardware specifications. Although...

Server DRAM prices (DDR4 & DDR5) saw further gains in August 2025, propelled by robust CSP demand and supply issues. Order visibility now extends to Q4, anticipating continued price increases...

3Q25 PC DRAM contract prices surged 8-13% quarterly, continuing upward in August. Cloud demand squeezed PC manufacturers'; supply, driving increases. However, a projected 4Q25 PC market slowdown may t...
2Q25 DRAM revenue surged from rising contract prices and robust shipments, especially DDR4. This positive trend is expected to continue into 3Q25, with further price and profit increases.

After sharp increases, DDR4 buyers resisted, slowing its rise and causing spot prices to fall. DDR3, due to capacity shifts and rising demand, became a new price focus. Panic buying eased, suggesting...

Supply strong, demand weak, August NAND Flash Wafer prices continue rising but with smaller increases. Demand focuses on depleting inventory, September market predicted stagnant, 3Q25-end prices expec...

In August 2025, SLC and MLC NAND Flash contract prices increased due to niche application demand and supply-side strategies. Telecom and industrial control markets boosted SLC prices, with Samsung&...

Amid rising geopolitical awareness, smartphone brands have gradually diversified production to countries like India and Vietnam in recent years; however, China remains the primary manufacturing hub in...
The 2Q25 Enterprise SSD market experienced significant growth, driven by robust AI applications and expanding general server deployments. However, severe supply chain challenges, including DDR4 memory...

Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...

Global Server Market Trends and Outlook for 2H25
In 2Q25, China's subsidies and US tariff stocking drove NAND Flash shipments and revenue. Growth will moderate in 3Q25 as demand normalizes.

DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.

NAND Flash contract prices remain stable with weak spot demand. Suppliers keep healthy inventory; PC and smartphone brands hold low stocks. Module house inventory steady, while hyperscalers increased...
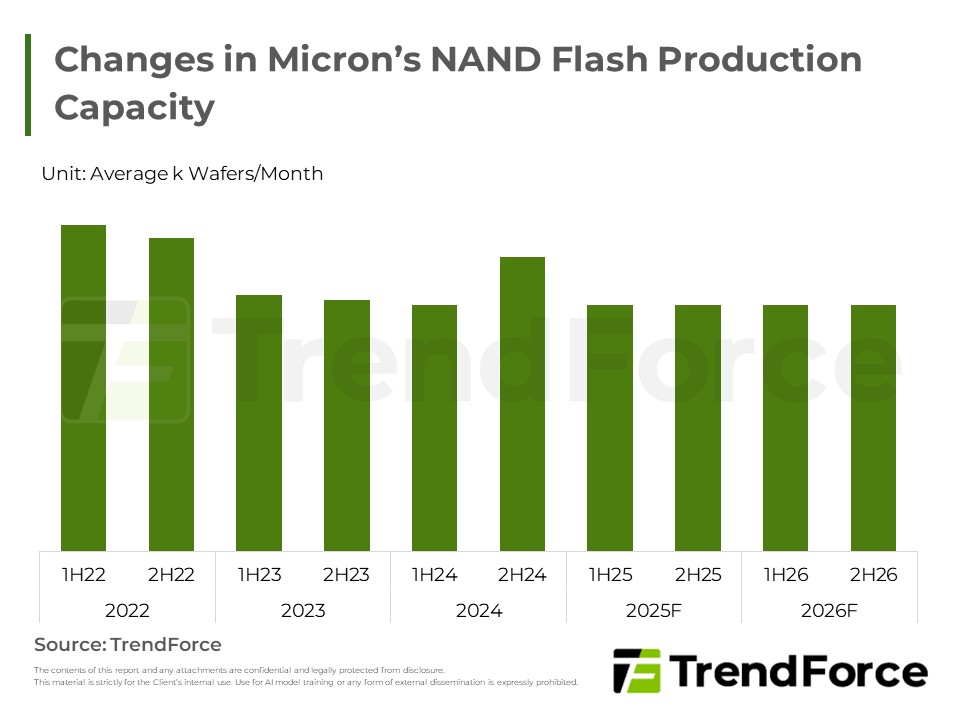
Micron has announced the halt of future mobile NAND Flash development, shifting focus to higher-margin areas like SSDs and HBM. This move addresses market competition and sluggish demand, reallocating...


