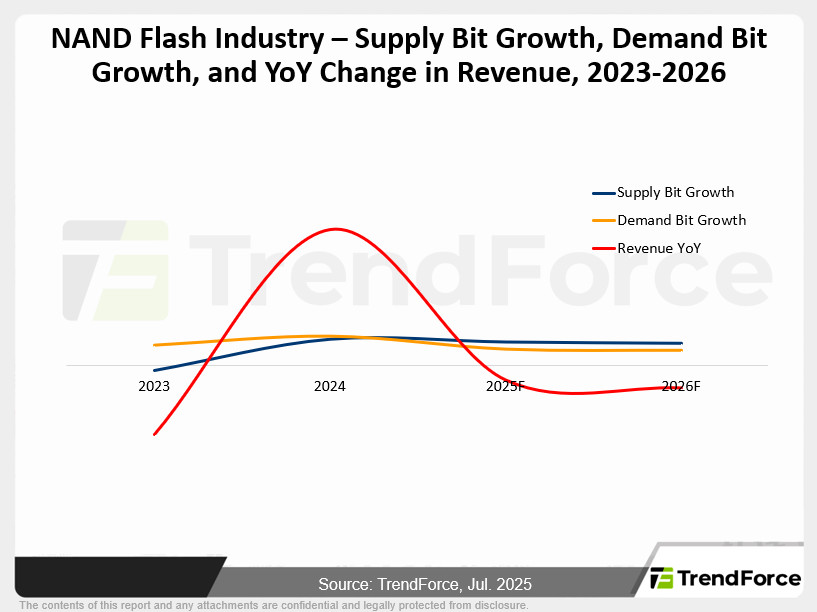
The 3Q25 contract market is stalled, with spot demand weak. For 2026, NAND Flash supply and demand are set to soften, driven by economic uncertainty and tariffs, indicating persistent price pressure.

Recent DRAM contract talks stalled; DDR5 gains moderating, DDR4 spot stabilizing. Looking ahead, supply and demand growth will significantly slow. Elevated inventory and weak end-demand point to contr...
eMMC/UFS contract prices for the third quarter of 2025 are projected to remain flat. Fading policy benefits, tariff impacts, and weak consumer demand limit upward movement. Suppliers are shifting focu...

The three main HBM suppliers are enhancing technology and customization to meet AI-driven demands, with growth in collaboration expected.

Contract price rises are slowing, and spot market gains are limited. Suppliers are reducing LPDDR4X supply while mid-range smartphone demand remains strong, leading to panic buying. Although some prod...

US tariff hikes add industry uncertainty, making contract talks cautious. NAND Flash spot prices pressured by weak demand and competition; smartphone market prices are hard to increase. Unless sudden...

NVIDIA H20 may resume sales to China, boosting AI GPU supply and demand for HBM and GDDR. US policy shift favors Chinese adoption of high-end AI chips. New products like RTX PRO 6000 will further supp...

MRDIMM addresses high-core CPU and AI needs, enhancing memory efficiency, but standards, cost, and support limit adoption.

The contract market focus shifts to the next quarter, with legacy products seeing clear price increases. Spot market transactions center on DDR4, with prices under pressure but no obvious oversupply....

Contract prices for NAND Flash rise on strong enterprise SSD demand; most segments see significant inventory reduction. Spot market remains sluggish as buyers await US-China policy direction.

LPDDR4X supply has tightened rapidly due to reduced production and EOL plans by major suppliers, driving prices sharply higher. Under dual pressure from supply constraints and price surges, smartphone...

DRAM contract prices steadily rise, DDR4 tight supply drives migration to new-gen products. Micron outperforms, shifts to value-added focus.

Tariff changes, production cuts, and weaker subsidies improve NAND Flash supply-demand. Contract prices rise, spot market cools; Micron's focus on value products boosts shipments, market share, a...

In 2025, global AI chips focus on high-end HBM memory; NVIDIA’s new Blackwell platform drives growth, amid geopolitical limits and steady AI server demand, with rapid HBM technology evolution toward H...

PC DRAM contract prices in Q2 2025 continue to rise, with DDR4 outpacing DDR5 due to changing supply-demand dynamics. Reduced supply, early procurement, and increased Nanya participation all contribut...


