
Supply strong, demand weak, August NAND Flash Wafer prices continue rising but with smaller increases. Demand focuses on depleting inventory, September market predicted stagnant, 3Q25-end prices expec...

In August 2025, SLC and MLC NAND Flash contract prices increased due to niche application demand and supply-side strategies. Telecom and industrial control markets boosted SLC prices, with Samsung&...

Amid rising geopolitical awareness, smartphone brands have gradually diversified production to countries like India and Vietnam in recent years; however, China remains the primary manufacturing hub in...
The 2Q25 Enterprise SSD market experienced significant growth, driven by robust AI applications and expanding general server deployments. However, severe supply chain challenges, including DDR4 memory...

Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...

Global Server Market Trends and Outlook for 2H25
In 2Q25, China's subsidies and US tariff stocking drove NAND Flash shipments and revenue. Growth will moderate in 3Q25 as demand normalizes.

DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.

NAND Flash contract prices remain stable with weak spot demand. Suppliers keep healthy inventory; PC and smartphone brands hold low stocks. Module house inventory steady, while hyperscalers increased...
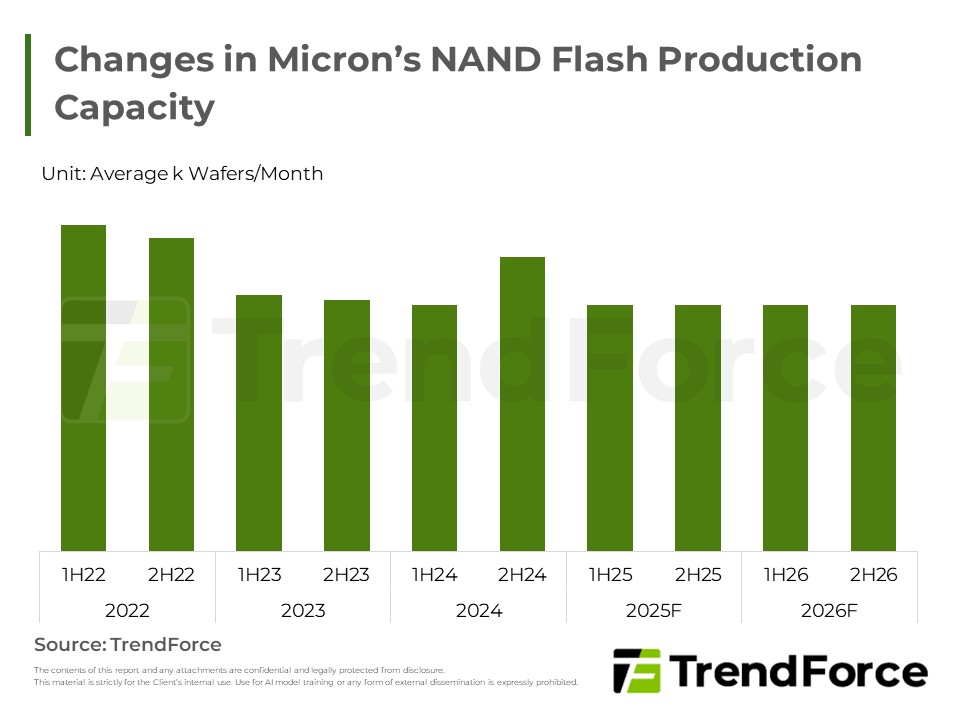
Micron has announced the halt of future mobile NAND Flash development, shifting focus to higher-margin areas like SSDs and HBM. This move addresses market competition and sluggish demand, reallocating...

The 2026 HBM3e market faces oversupply with Samsung likely ramping up HBM3e capacity causing price declines; HBM4 sees premium pricing amid fierce competition and concentrated NVIDIA supply.

In 2Q25, global smartphone production reached approximately 300 million units, up 4% quarter-over-quarter and 4.8% year-over-year. In terms of market share, Samsung maintained its leading position, be...

In the third quarter, enterprise SSD demand is strong, supporting NAND Flash capacity, while the smartphone and PC markets are weak. YMTC expands capacity and improves yield rates, increasing market s...

3Q25 DRAM contract prices has been set in Aug., DDR5 rising modestly while the shipments increasing. Spot market stays calm, DDR4 is influenced by potential Samsung EOL delay. TrendForce update on CXM...

Samsung advances high-value NAND Flash technology amid rising AI and data center demand. Enterprise SSD growth boosts inventory digestion, yet overall NAND market recovery remains limited due to econo...


