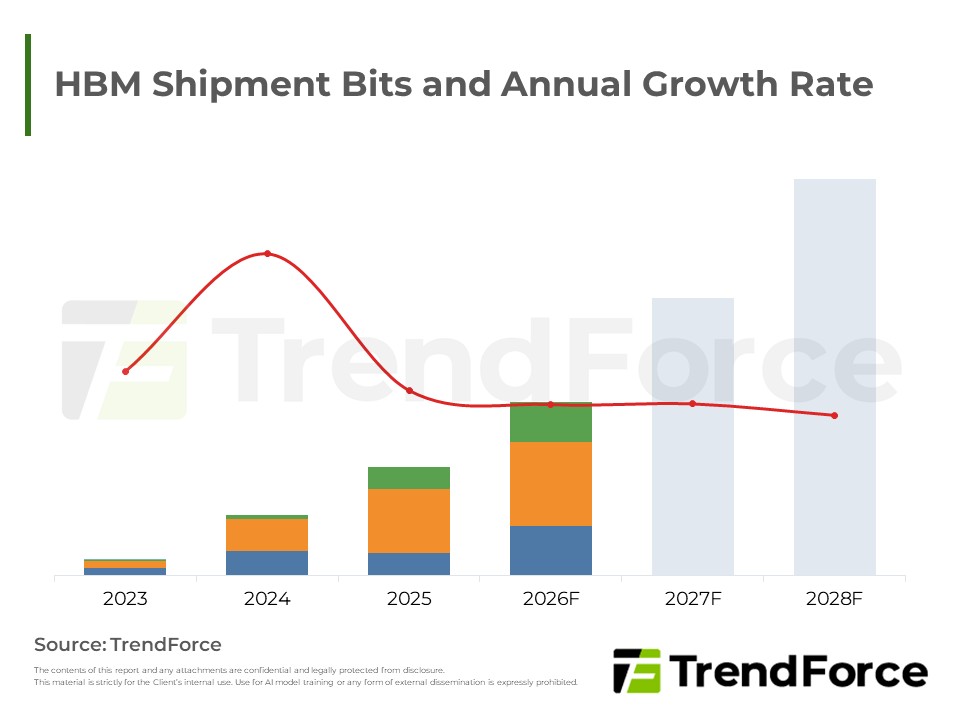
HBM remains irreplaceable in AI accelerators. HBM4 ramps, tight supply lifts prices, and ASIC demand diversifies the supplier base.
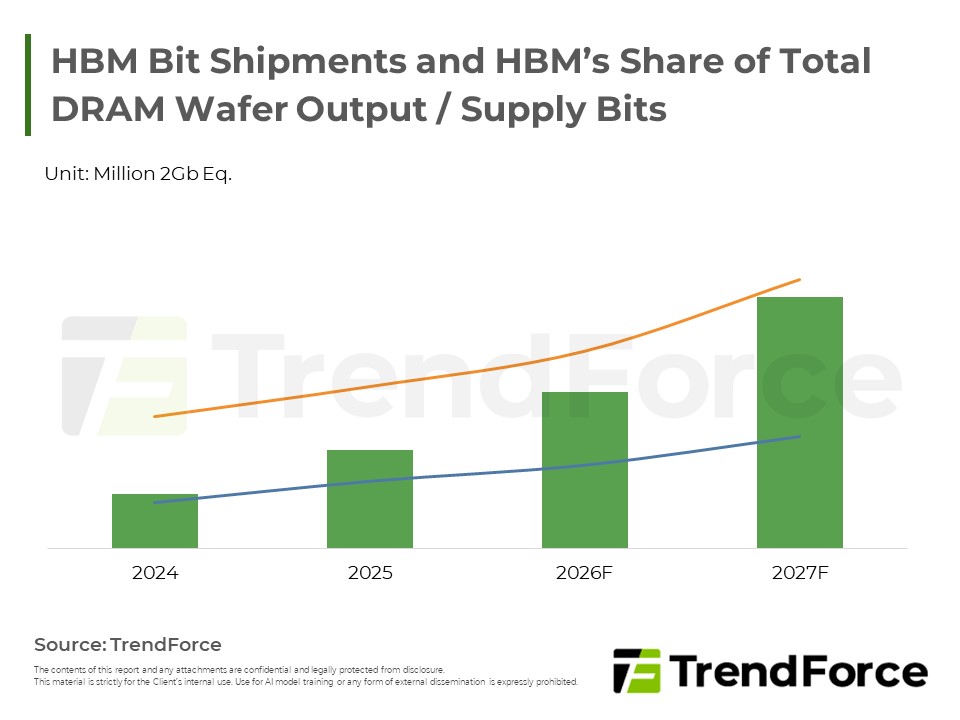
Since 2H25, accelerated AI infrastructure buildouts by CSPs have surged HBM demand and crowded out conventional DRAM capacity, pushing the broader DRAM market into shortage. Constrained by annual pric...
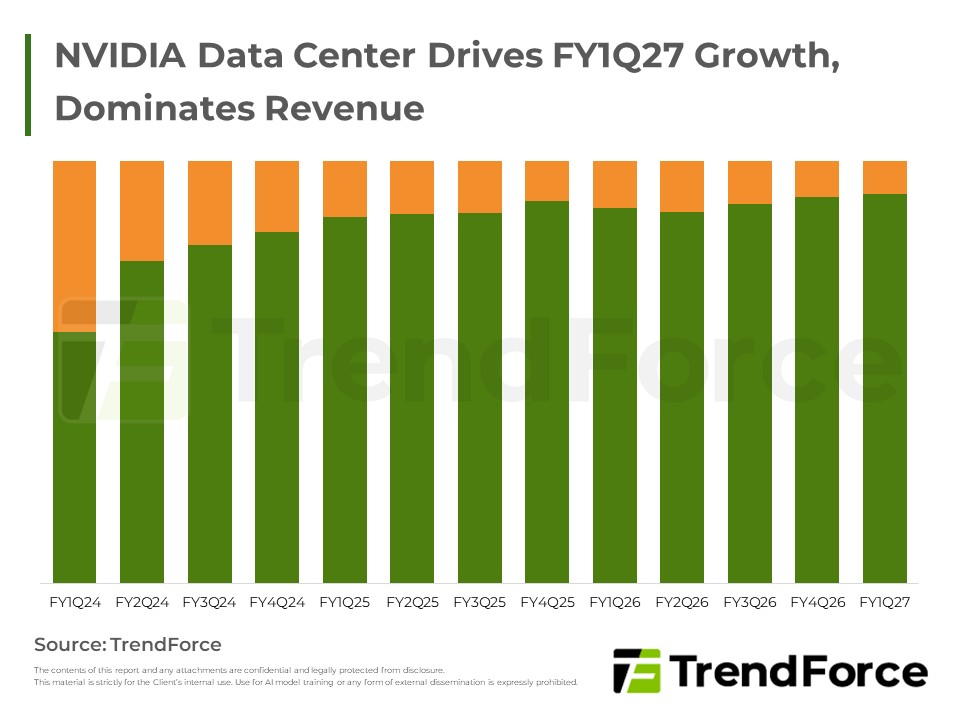
NVIDIA FY1Q27 hit a record high with Data Center share above 92%,with GB/VR Rack rollout boosting liquid cooling and HBM supply chains.
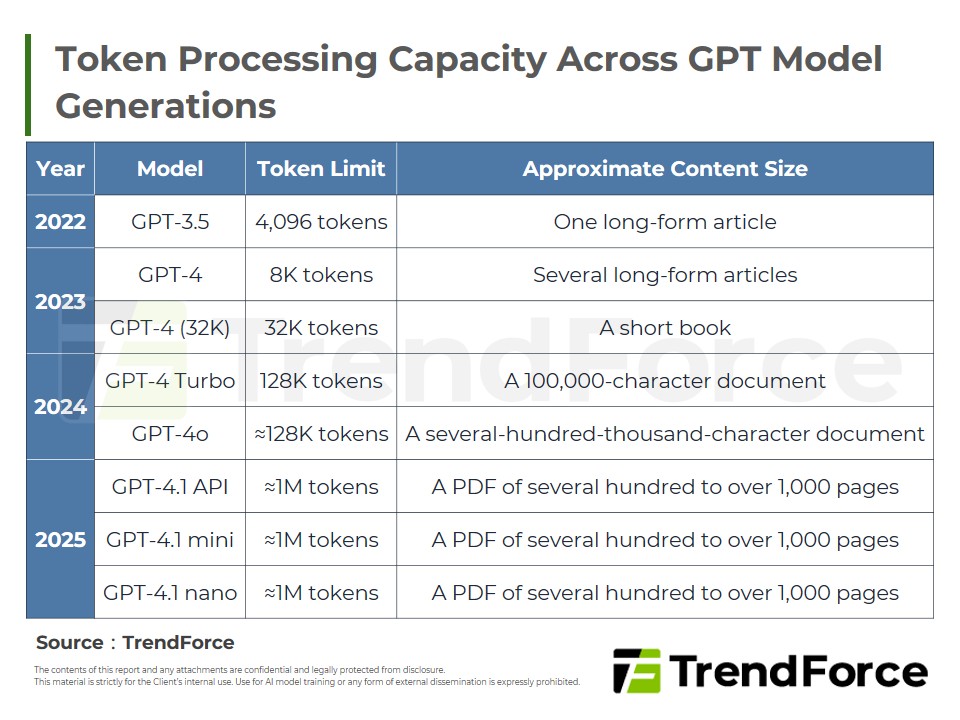
This report first explains why HBM plays a key role in the evolution of LLM and AIGC applications. It then examines the HBM upgrade roadmap and explores how heterogeneous memory integration strategies...
The three major HBM suppliers highlighted HBM4 mass production and HBM4e development, as competition shifts toward pricing power and next-generation specs. Suppliers also remain positive on long-term...
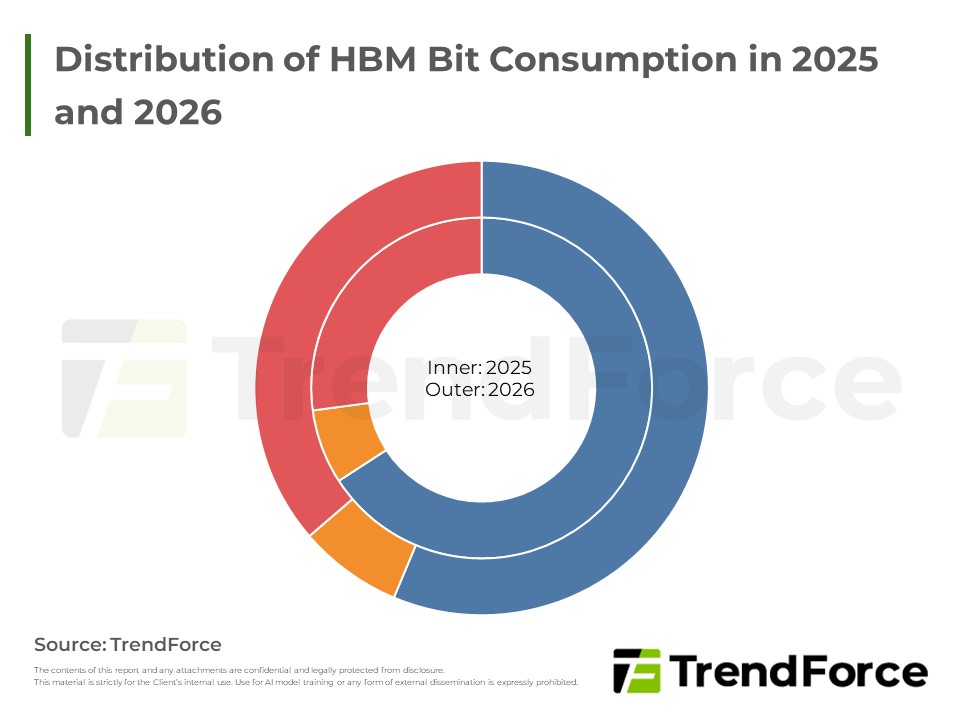
HBM grows strongly in 2026 as CSP/ASIC demand lifts HBM3e prices; SK hynix leads, Samsung rebounds, Micron expands TSV.
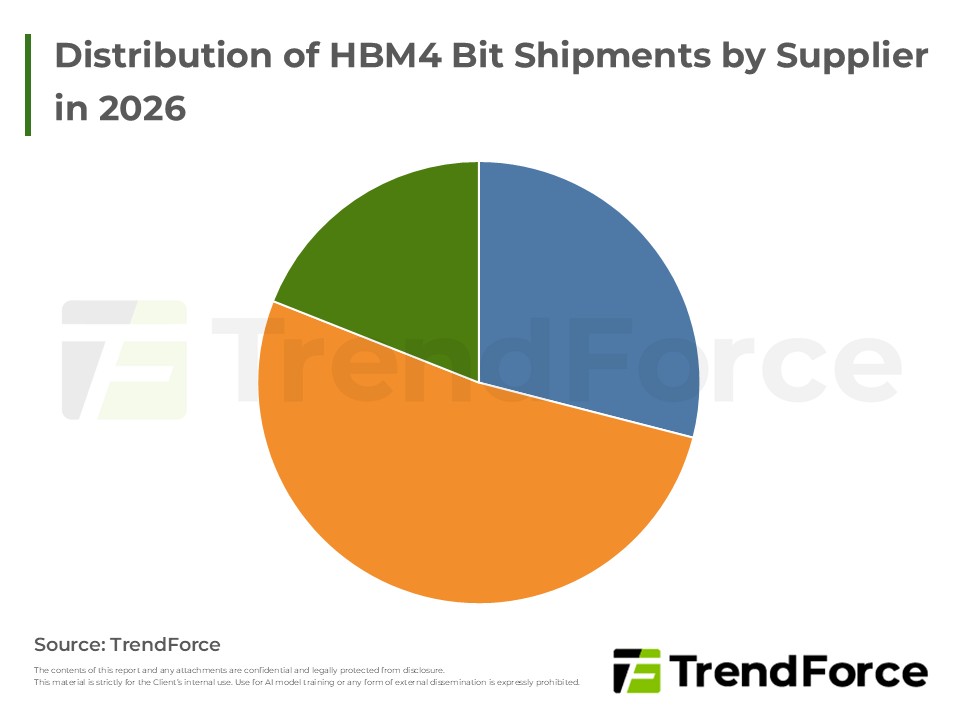
NVIDIA's upgraded HBM4 specifications have delayed supplier validations. Samsung, leading in chip performance, is poised to complete certification first and increase market share, while competitors re...
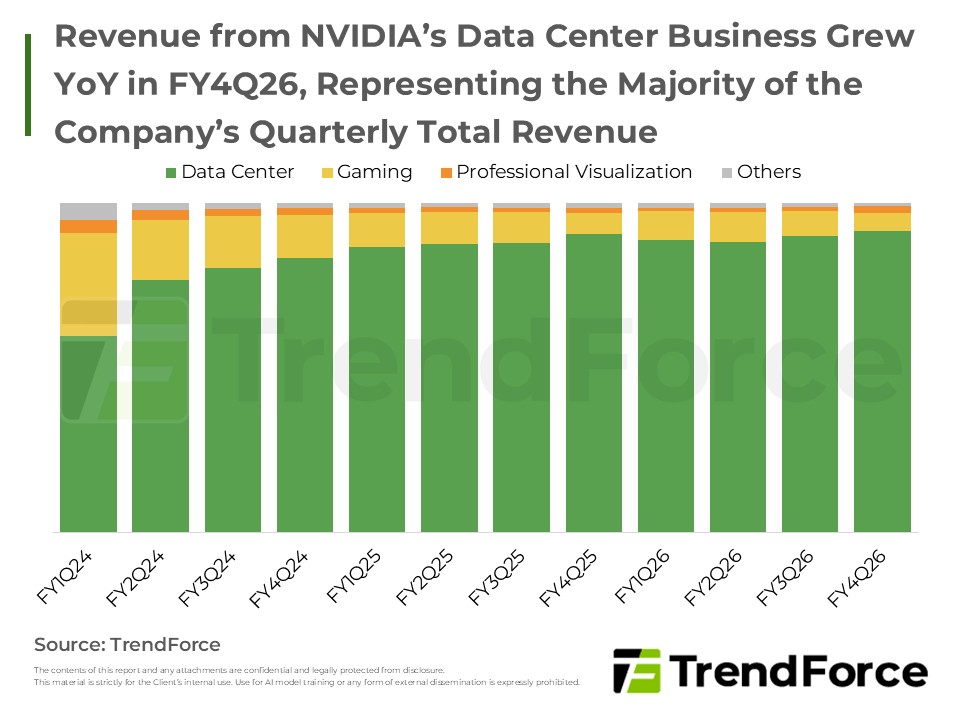
NVIDIA achieved record revenue driven by cloud AI and data center dominance. North American CSPs lead demand, establishing the GB series as mainstream and accelerating liquid cooling. However, HBM4 de...
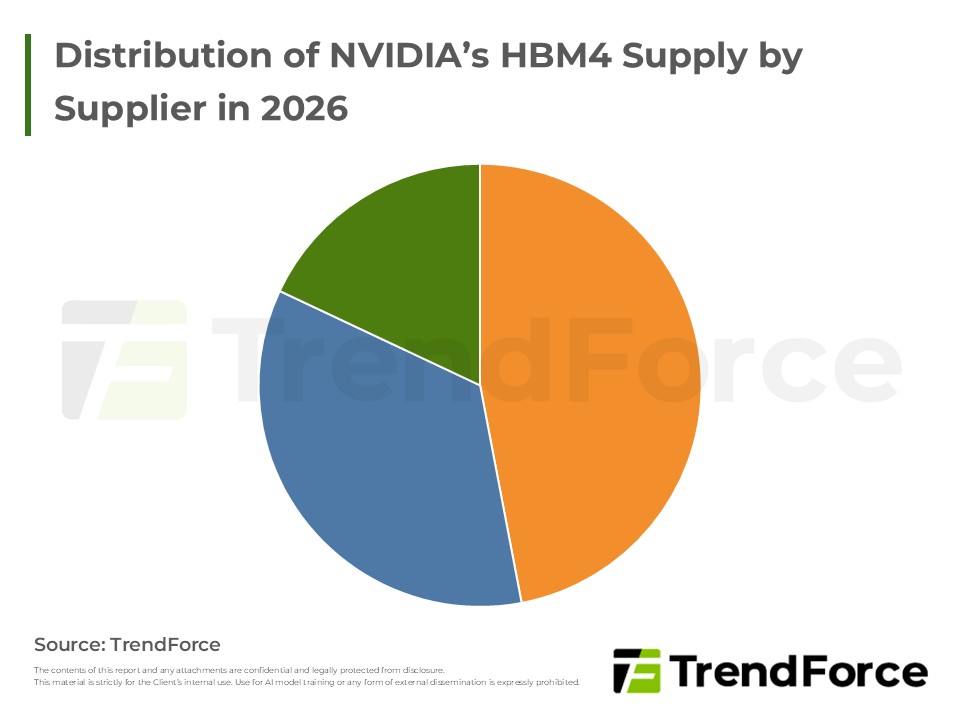
Samsung currently leads HBM4 validation due to process improvements enhancing stability. SK hynix retains volume leadership despite re-sampling, while Micron trails slightly. Given robust AI demand an...
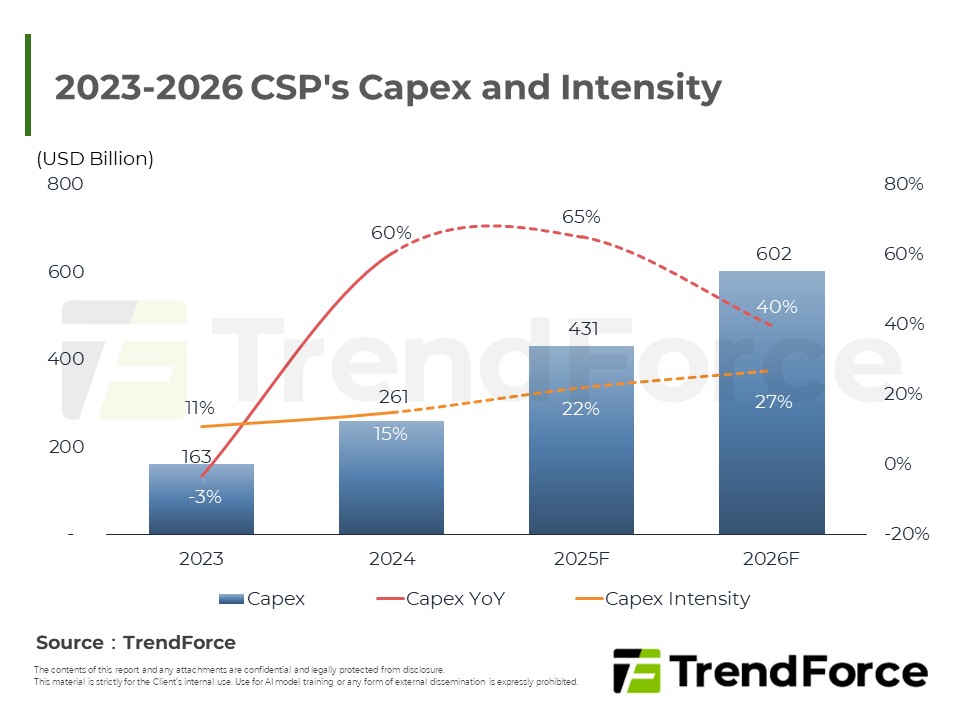
DRAM industry will focus on HBM capacity expansion, with Chinese suppliers limited by equipment restrictions; major players like Samsung, SK hynix, and Micron emphasize tech migration and AI applicati...
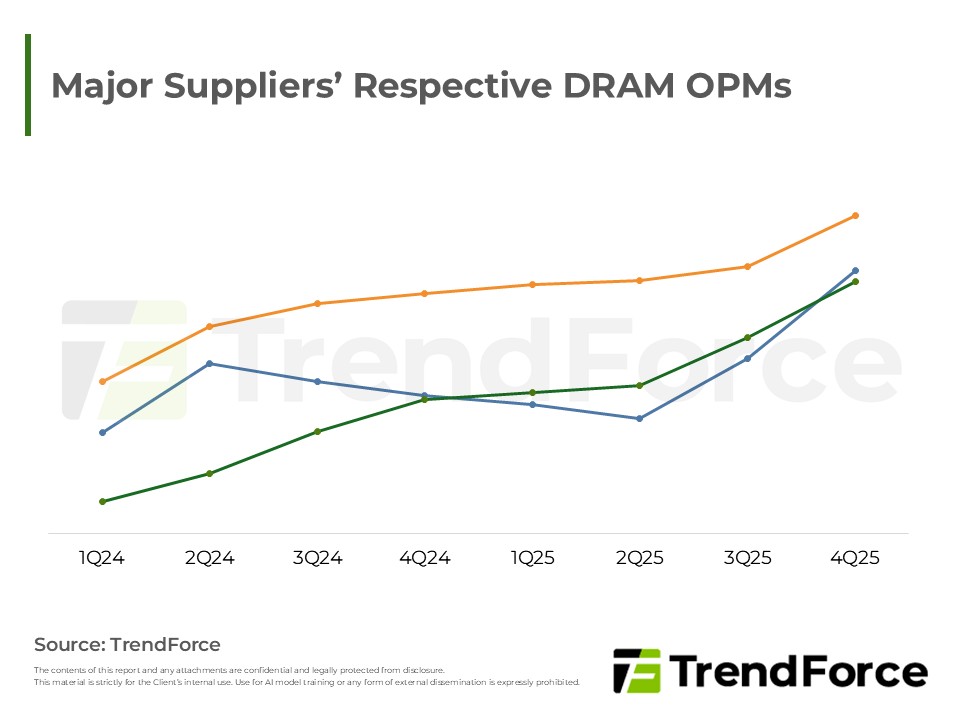
The industry enters a 2026 Super Cycle driven by DRAM and Enterprise SSDs. Despite a slowdown in consumer electronics, AI remains the primary growth engine. Low inventory levels and the transition to...
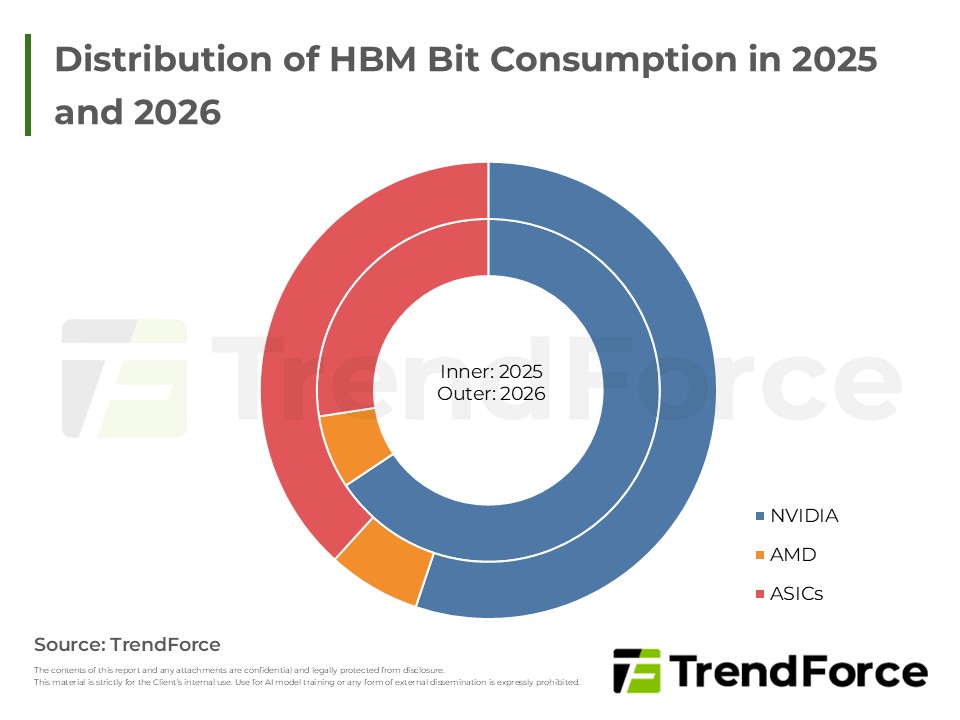
In 2026, the HBM market continues to grow, with SK hynix maintaining its lead and Samsung recovering significantly via HBM3e and HBM4 contributions. Micron also expands aggressively. While HBM3e domin...
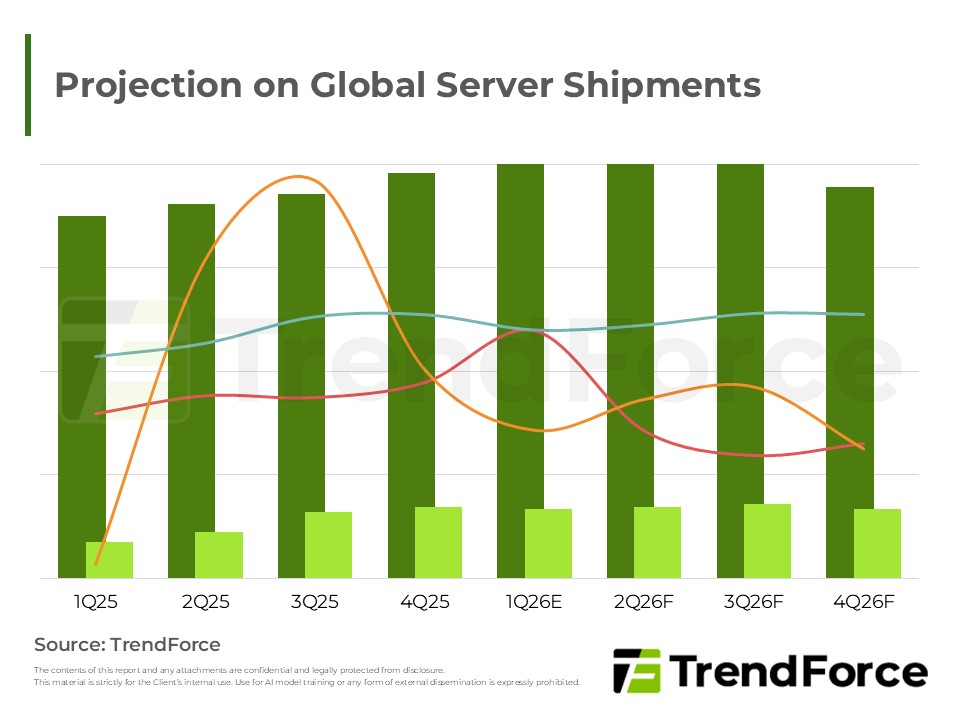
NVIDIA and CSPs drive sustained AI growth through aggressive investment in GPUs, ASICs, and rack-scale infrastructure. Geopolitics reinforce ecosystem trends, benefiting supply chains. Surging AI work...
Raised specs delayed HBM4 production, keeping HBM3e dominant. Samsung leads verification with advanced tech, while SK hynix retains the top share.
Driven by expanding CSP capital expenditures, AI server demand remains robust. Liquid cooling adoption accelerates as the high-end standard. Strong demand pushes HBM3e prices up amid tight supply, whi...






