The 6th to 10th spots of global smartphone ranking for 2025 are occupied by Transsion, Honor, Lenovo, Huawei, and Google in sequential order. Among which, Transsion has slightly dropped in share due t...
Contract DRAM prices are expected to surge significantly, with Micron leading. Spot market sellers are holding back due to strong outlook, causing DDR4 scarcity and DDR5 price hikes. AI's evo...
TrendForce forecasts a structural memory price hike by 2026. Strong AI server demand and profit-first supplier strategies lead to capacity shifting towards high-margin applications, driving widespread...
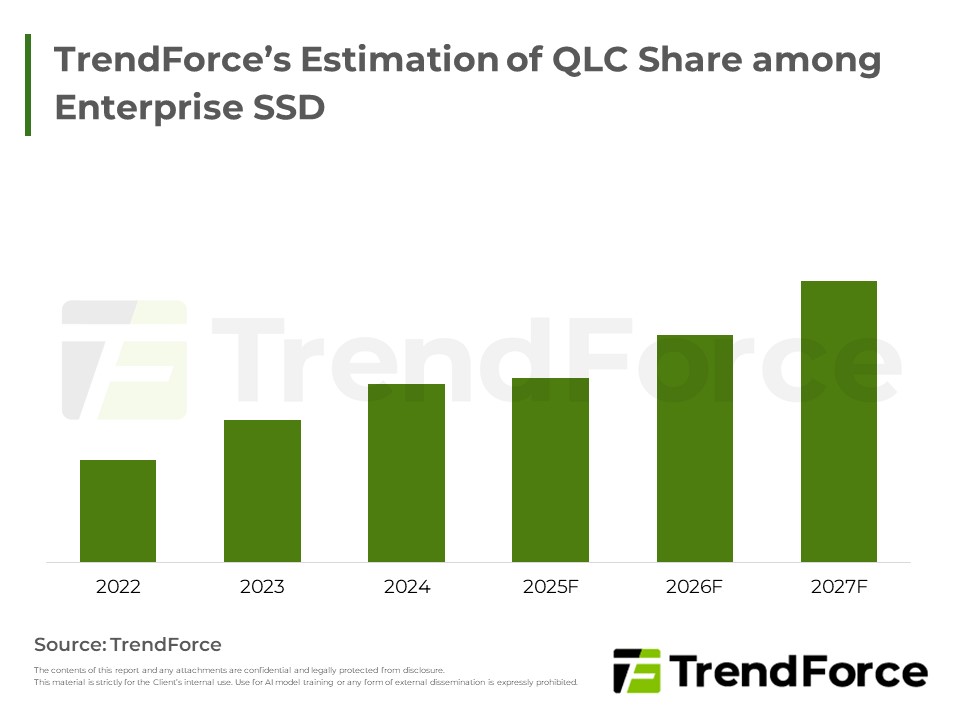
The NAND Flash market is robust, driven by enterprise SSD and AI demand, pushing up contract and spot prices. Micron, leveraging QLC technology and data center SSDs, has successfully transformed and a...
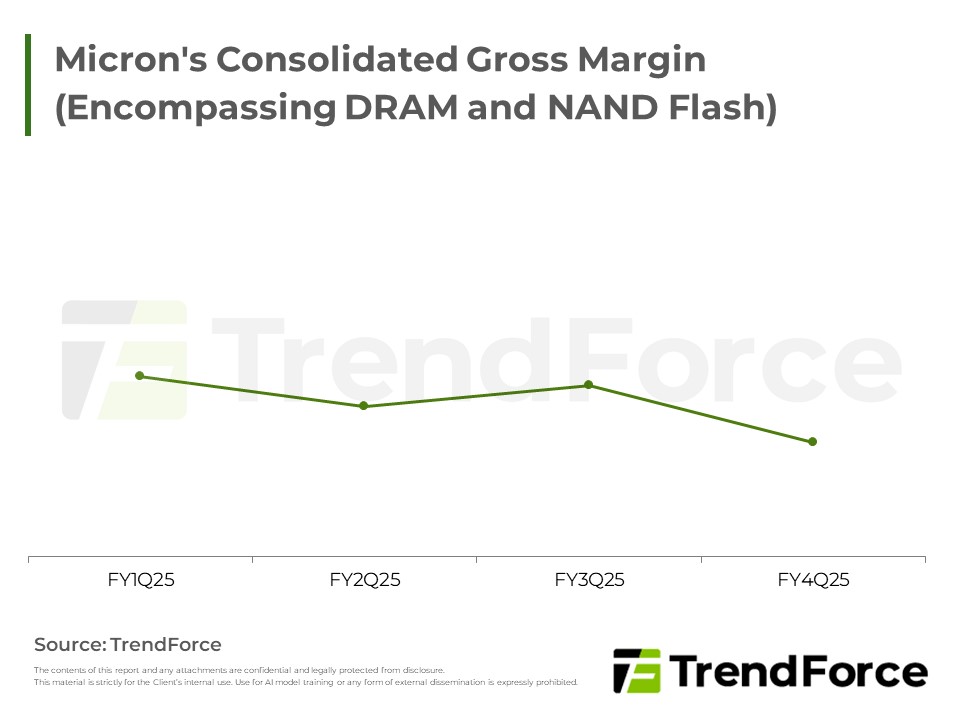
The DRAM market is robust, with prices surging across contract and spot sectors, firmly establishing a seller-driven environment due to tightening supply. Micron's AI-driven performance and HBM l...
Sep consumer DRAM contract price growth slowed. Looking ahead, strong CSP server demand displaces capacity, pushing 4Q25 consumer DRAM to double-digit hikes, with the rally extending into 1H26.
2025 DRAM contract prices are rising. Manufacturers prioritize strong server demand, tightening PC DRAM supply. OEMs may adjust procurement strategies to counter future price hikes.
Sept 2025 server DRAM contract prices surged due to persistent CSP demand, with DDR5/DDR4 increasing. 8000MT/s modules will see accelerated adoption. Strong 2026 demand and tight supply are set to ext...
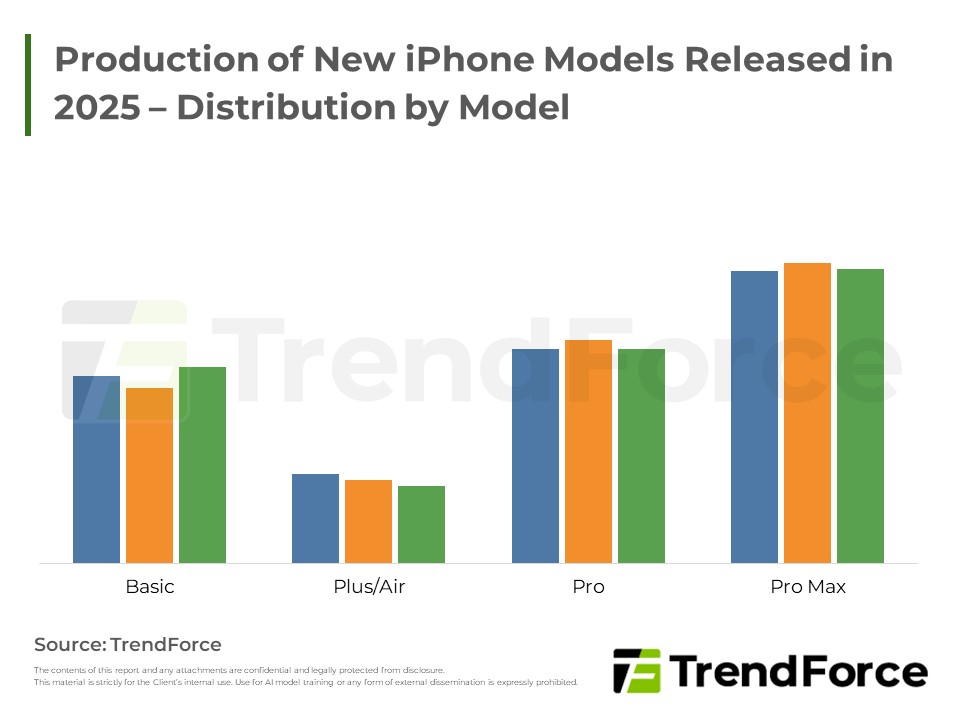
Market consolidation in the smartphone industry will persist in the short term, though brand rankings may shift. Apple is set to gain share on strong new model sales, Xiaomi’s in-house chip advances w...
Tight DRAM supply fuels rising contract/spot prices. Low supplier inventory driven by strong US CSP demand. Client stock levels vary, but continued price hikes are expected.
Robust AI server demand, driven by NVIDIA, AMD, and CSP custom ASICs, propels market growth. DDR5 is mainstream, yet DDR4 sees extended life and price rebound from storage needs. AMD and ARM challenge...
Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...
4Q25 memory prices continue upward. Strong AI demand from US CSPs and HDD shortages boosting enterprise NAND Flash are key. Suppliers prioritize profit, tightening old process supply.
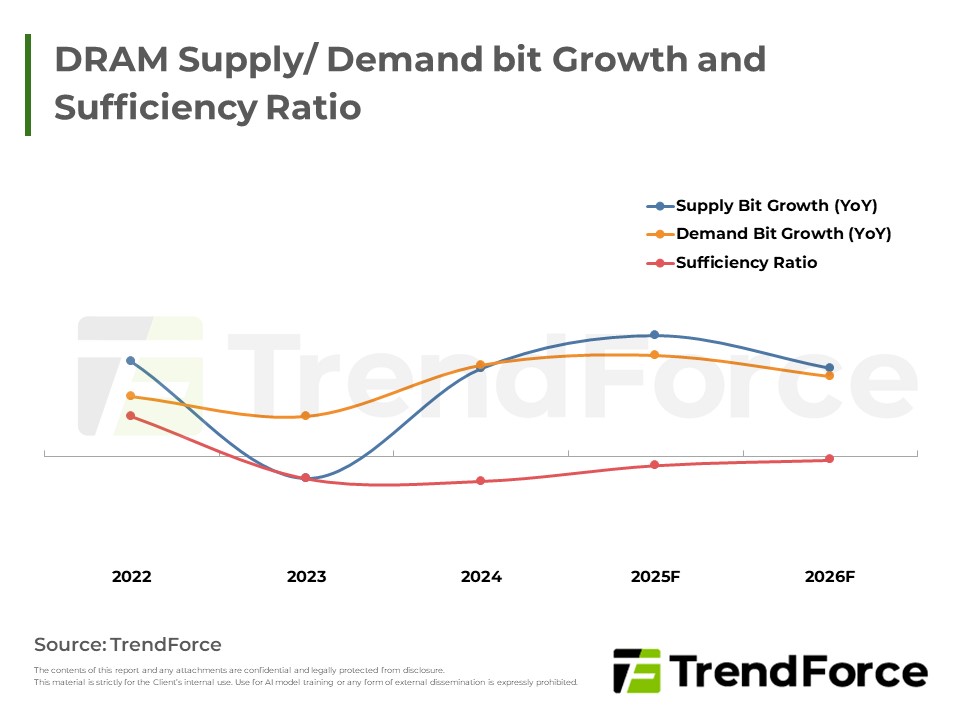
Cloud demand tightens memory supply, boosting contract prices. Spot market is soft, yet prices rise. A slight shortage supports prices, but outlook is cautious due to policy shifts.
2Q25 server DRAM revenue increased by 11% QoQ, driven by DDR5 shipments and DDR4 price recovery. CSPs shifted from destocking to restocking, and DDR4, due to strong demand for storage server applicati...






