[News] After TSMC’s 3Q26 Earnings: Key Brokerage Takeaways as 2028 Capex Forecasts Reach US$105B
Following TSMC’s bullish earnings call, which saw the foundry giant raise its 2026 revenue growth outlook to 44% YoY and forecast another record quarter in 4Q26, foreign brokerages have weighed in with a largely upbeat verdict: all looks strong—except margins.
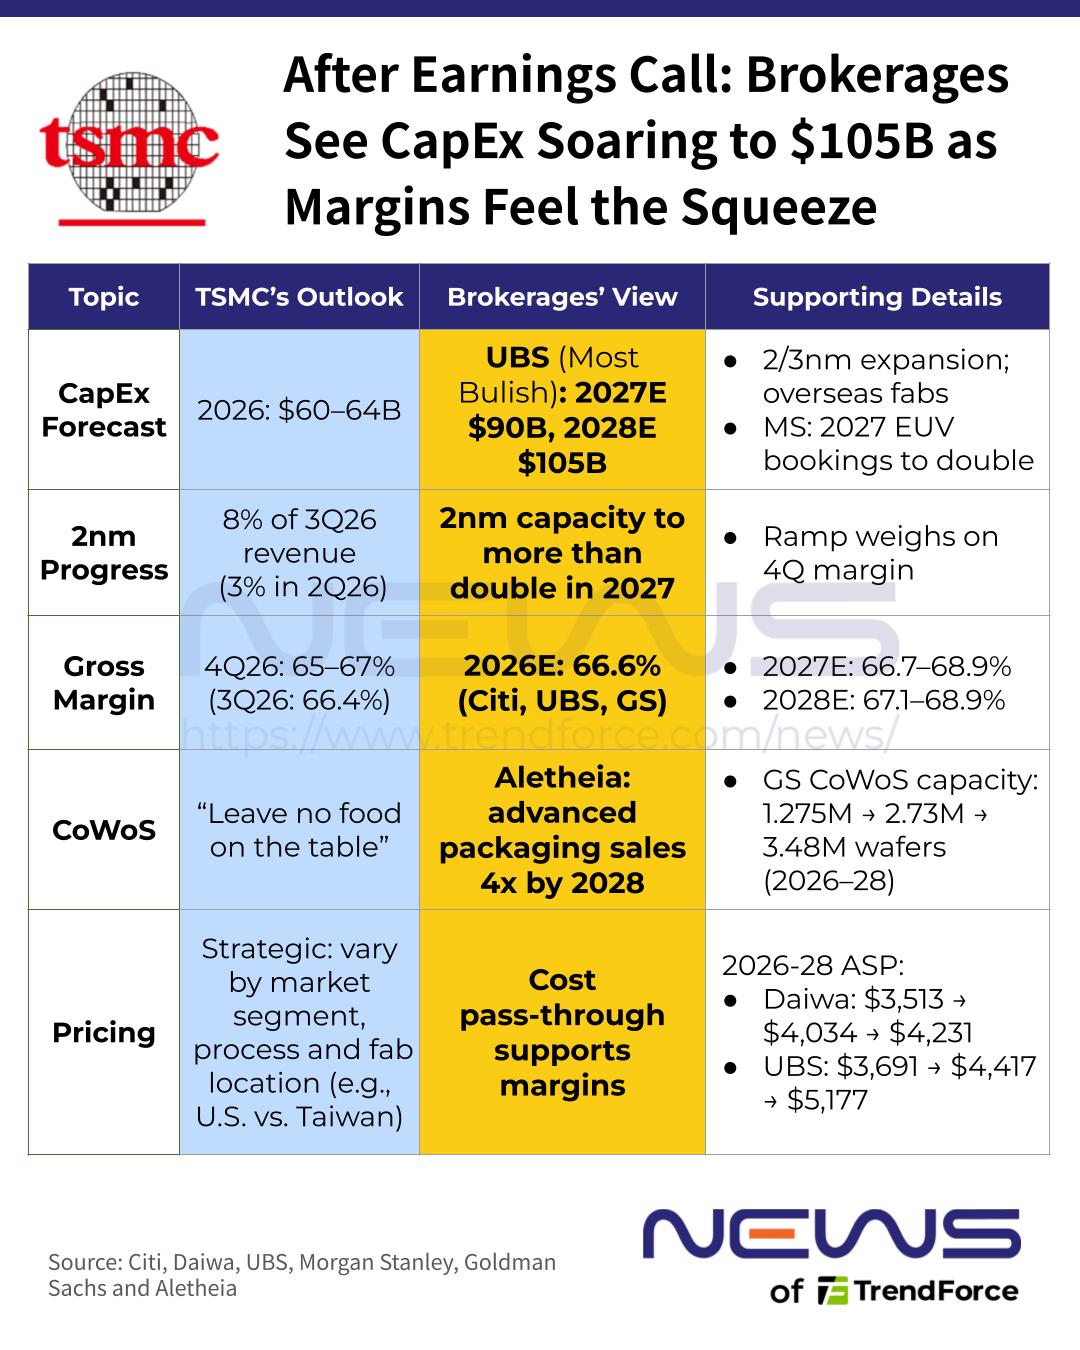
Notably, analysts have revised their 2027–2028 capex forecasts after TSMC signaled significantly higher spending over the next three years, with the most bullish estimate now reaching US$105 billion. Here are five key takeaways from the latest brokerage reports, spanning capex, 2nm momentum, gross margins, pricing and CoWoS.
Brokerages Raise Capex Forecasts; MS Sees 2027 EUV Bookings Doubling
While maintaining its 2026 capex guidance at US$60–64 billion, TSMC signaled plans to accelerate 2nm production and expand 3nm capacity, with four fabs planned for the latter. Amid reports of rising semiconductor equipment prices, the foundry giant also acknowledged that “tool inflation is real,” setting the stage for further increases in capital spending.
Against this backdrop, foreign brokerages are raising their capex forecasts for TSMC, with UBS taking the most bullish stance. The bank expects spending to surge roughly 45% YoY to US$90 billion in 2027 before climbing to US$105 billion in 2028.
Morgan Stanley, meanwhile, cited initial checks with equipment suppliers suggesting EUV tool bookings could double in 2027, followed by another 25–30% increase in 2028. The brokerage accordingly raised its capex estimates to US$83 billion and US$92 billion, respectively. Goldman Sachs and BofA Securities also see TSMC’s 2027 spending reaching US$85 billion.
2nm Gains Momentum as Margin Headwinds Linger
TSMC’s 2nm revenue share jumped to 8% in 3Q26 from 3% in the previous quarter, with foreign brokerages citing management’s expectation that capacity will “more than double in 2027.” Yet the rapid expansion comes at a cost. TSMC’s 4Q gross margin guidance of 65–67% suggests limited upside from 3Q’s 66.4%, as the 2nm ramp weighs on profitability, according to brokerage assessments.
Citi, UBS and Goldman Sachs all project a 66.6% gross margin for 2026. Despite dilution from 2nm production and overseas expansion, analysts expect gross margins to rise to 66.7–68.9% in 2027 and reach 67.1–68.9% in 2028.
Pricing Power to Support Margins, Lift ASP Through 2028
As TSMC looks to sustain margin growth over the next few years, brokerages see its pricing power as a key support. UBS, in particular, notes that the foundry giant could pass rising costs on to customers, helping preserve profitability.
That strength, coupled with a richer product mix, is also expected to lift average selling prices (ASPs). Daiwa Capital Markets forecasts TSMC’s blended ASP, based on 8-inch-equivalent wafers, to rise from US$3,513 in 2026 to US$4,034 in 2027 and US$4,231 in 2028.
UBS presents an even more bullish pricing trajectory in its financial model, projecting TSMC’s 8″-equivalent blended ASP to expand to US$3,691 in 2026, US$4,417 in 2027, and US$5,177 in 2028.
CoWoS Capacity Seen Doubling in 2027
Vowing to “leave no food on the table,” TSMC is doubling down on advanced packaging despite CoWoS capacity constraints and intensifying competition from Intel’s EMIB.
The push could fuel substantial growth. Aletheia expects TSMC’s cutting-edge wafer revenue to double between 2026 and 2028, while advanced packaging revenue could quadruple over the same period.
Goldman Sachs, meanwhile, projects TSMC’s CoWoS capacity to reach 1.275 million wafers in 2026, or roughly 106,000 per month, before surging 114% YoY to 2.73 million in 2027 (227,500 monthly). Capacity is then expected to climb another 27% to 3.48 million wafers in 2028, equivalent to nearly 290,000 per month.
Read more
- [News] TSMC Lifts 2026 Growth Forecast to 44%, Eyes Record 4Q Revenue of Up to US$54.3B, Up 14% QoQ
- [News] TSMC 3Q26 Net Profit Surges 68.7% to Record NT$763B, EPS Hits NT$29.43; 2nm Sales Share Climbs to 8%
(Photo credit: TSMC)