2025 DRAM contract prices are rising. Manufacturers prioritize strong server demand, tightening PC DRAM supply. OEMs may adjust procurement strategies to counter future price hikes.

Sept 2025 server DRAM contract prices surged due to persistent CSP demand, with DDR5/DDR4 increasing. 8000MT/s modules will see accelerated adoption. Strong 2026 demand and tight supply are set to ext...

Market consolidation in the smartphone industry will persist in the short term, though brand rankings may shift. Apple is set to gain share on strong new model sales, Xiaomi’s in-house chip advances w...

Tight DRAM supply fuels rising contract/spot prices. Low supplier inventory driven by strong US CSP demand. Client stock levels vary, but continued price hikes are expected.
Robust AI server demand, driven by NVIDIA, AMD, and CSP custom ASICs, propels market growth. DDR5 is mainstream, yet DDR4 sees extended life and price rebound from storage needs. AMD and ARM challenge...

Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...

4Q25 memory prices continue upward. Strong AI demand from US CSPs and HDD shortages boosting enterprise NAND Flash are key. Suppliers prioritize profit, tightening old process supply.
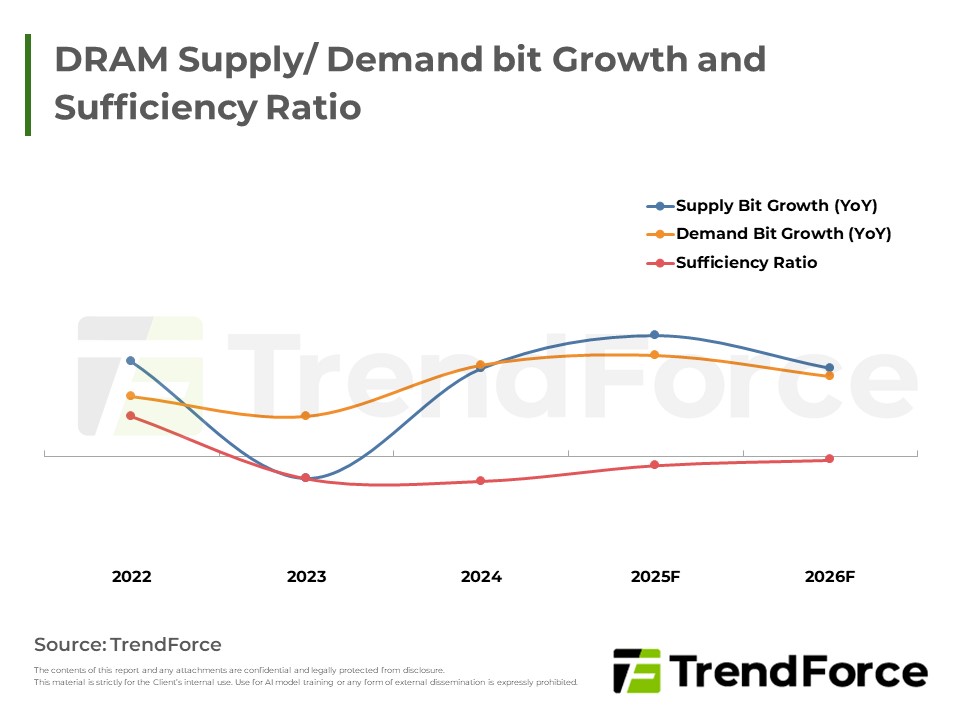
Cloud demand tightens memory supply, boosting contract prices. Spot market is soft, yet prices rise. A slight shortage supports prices, but outlook is cautious due to policy shifts.
2Q25 server DRAM revenue increased by 11% QoQ, driven by DDR5 shipments and DDR4 price recovery. CSPs shifted from destocking to restocking, and DDR4, due to strong demand for storage server applicati...

Samsung leads in smartphone market share, but mid-to-low-end shipments decline due to economic factors and competition. In 2026, select flagship models will feature Exynos 2600, segmenting markets. LP...

4Q25 Server and Smartphone DRAM contract prices are rising. TrendForce will upgrade 2026 server and DRAM demand forecasts due to AI expansion and sovereign AI, anticipating higher bit growth and narro...
In 2Q25, global smartphone production saw a slight increase due to seasonal demand and inventory adjustments. Production estimates for 2025 and 2026 suggest steady growth. Mobile DRAM revenue was driv...
2Q25 DRAM revenue grew notably from price and shipment increases. 3Q25 momentum is expected to continue, with accelerating price hikes. US CSPs show robust demand but slightly elevated inventory. Smar...

DRAM contract prices are expected to peak by late 2025, then decline as new capacity emerges. DDR4 faces critical long-term shortages. HBM3e prices soften, HBM4 maintains a premium, with Samsung leadi...

Server DRAM prices (DDR4 & DDR5) saw further gains in August 2025, propelled by robust CSP demand and supply issues. Order visibility now extends to Q4, anticipating continued price increases...


