


 Download Report
 Contact Us
DRAM Market Bulletin - Nov. 18, 2026

Last Modified
2026-11-18

Update Frequency
Weekly

Format
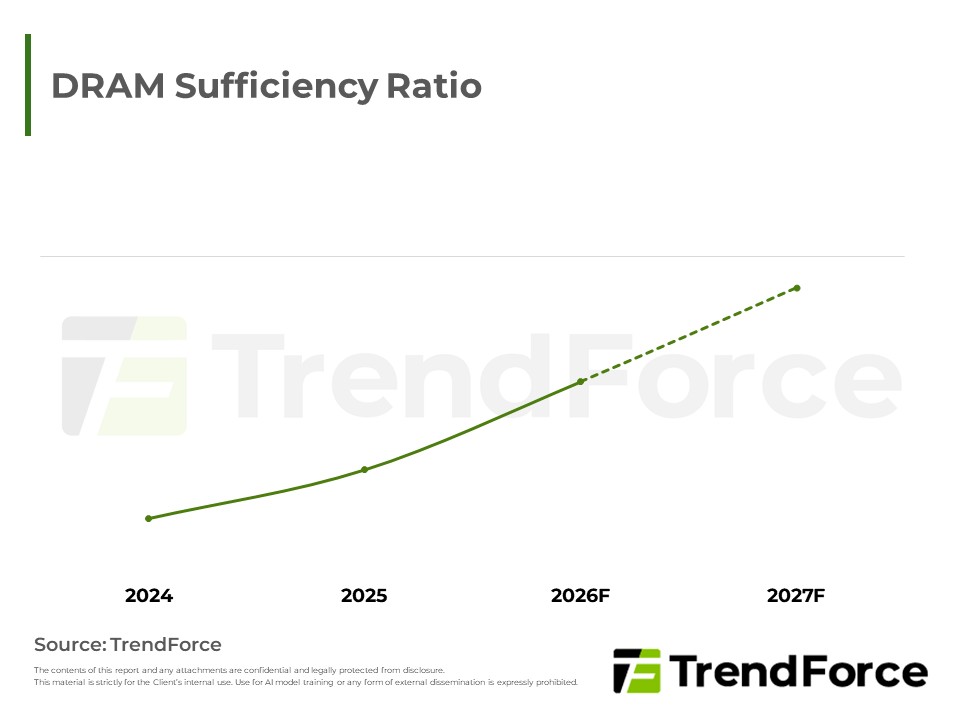
Mobile DRAM contract talks have stalled as brands hold back on purchases, and spot demand remains weak. Looking ahead, capacity expansion and node migration will lift supply. Even so, AI build-outs already underway and steady HBM and server demand will keep the market undersupplied. The shortage gap is narrowing, so contract price gains will slow quarter by quarter.
Key Highlights
- Contract market: Mobile DRAM negotiations are at a standstill. Many brands adopted the wait-and-see stance.
- Spot market: End demand is weak, and most inquiries purpose on getting quotation.
- Supply: New capacity from the three major suppliers is ramping up, and advanced nodes are becoming mainstream.
- Demand: Most AI data centers for next year are already under construction, so policy shifts will have limited impact on them. HBM procurement is largely locked in.
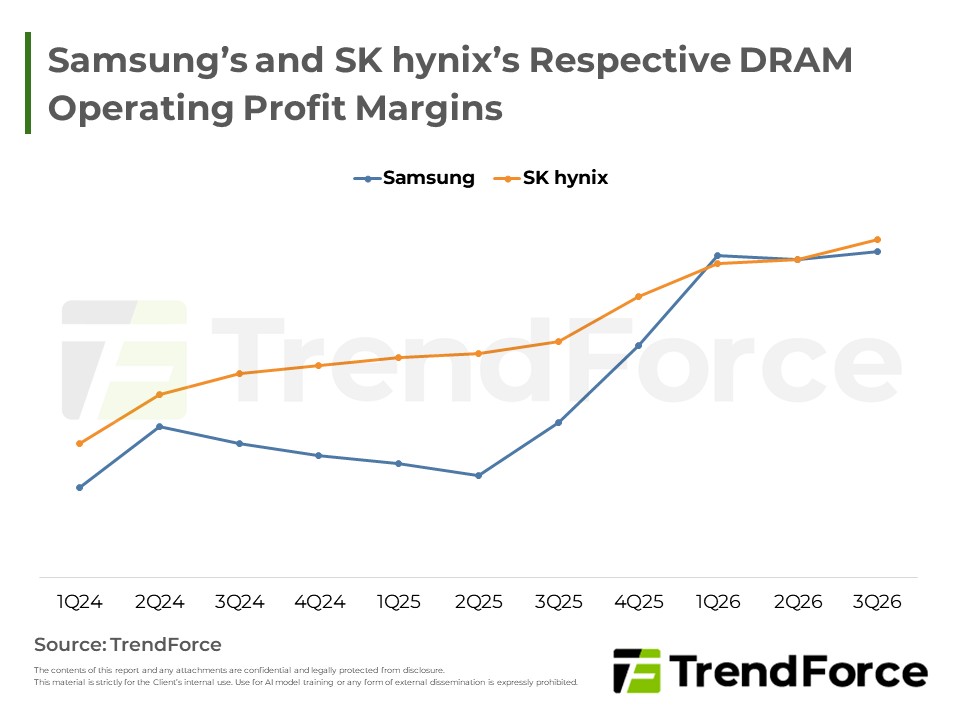
- Price outlook: Contract prices will keep rising, but the gains will shrink each quarter. The key factors are price clauses in long-term agreements, the timing of capacity expansions, and the demand outlook for 2028.
Table of Contents
- Market Update
- TrendForce’s View
- DRAM Sufficiency Ratio
- QoQ Changes in DRAM Prices
<Total Pages: 3>

Spotlight Report
-

DRAM Monthly Datasheet Nov. 2026
2026/11/16
Semiconductors
EXCEL
-

NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-

4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-

Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-

DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-

DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF
DRAM Market BulletinRelated Reports

Download Report
18,000

Membership
Spotlight Report
-
DRAM Monthly Datasheet Nov. 2026
2026/11/16
Semiconductors
EXCEL
-
NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-
4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-
Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-
DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-
DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF