


 Download Report
 Contact Us
3Q26 Global Automotive Market Decode

Last Modified
2026-09-30

Update Frequency
Quarterly

Format
Global auto demand is downgraded as China’s market weakens, slowing EV growth and reviving hybrids as a strategic focus. ADAS/AV penetration keeps rising, with automakers designing more in-house SoCs. MLCC supply chains “protect AI, limit auto semis.” Chinese battery makers gain share; Japanese/Korean firms face profit pressure and pivot to storage. Policies tighten local manufacturing, while Europe speeds Robotaxi commercialization via partnerships.
Key Highlights
- China’s domestic demand has fallen sharply, dragging down global sales forecasts. EVs and new energy vehicles are still growing, but momentum is weaker than last year.
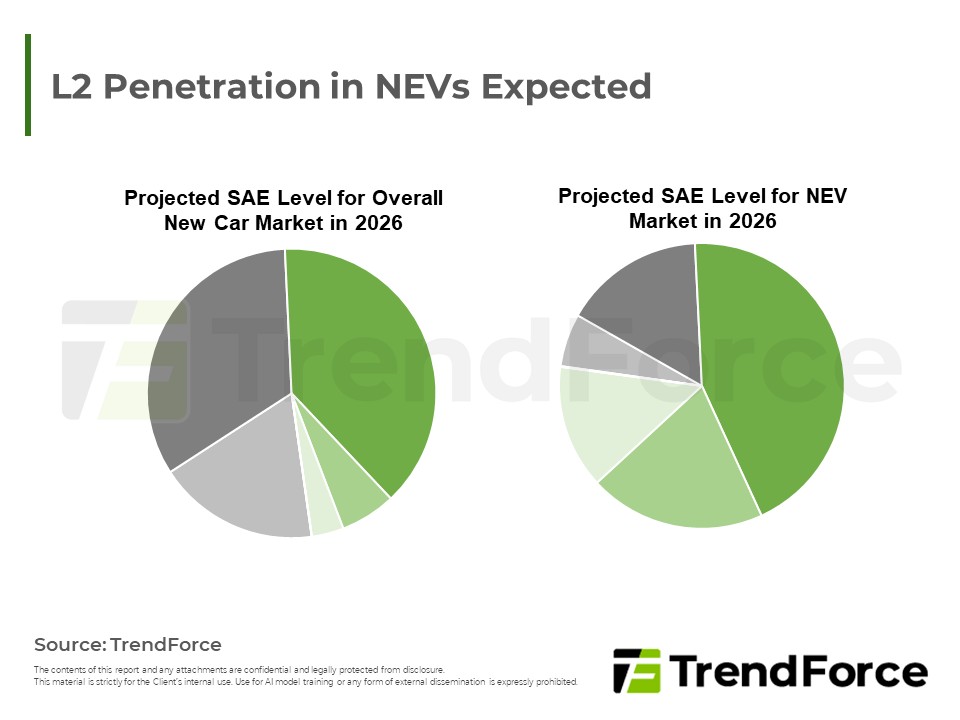
- ADAS Penetration: ADAS features, including highway and urban navigation autopilot, are increasingly becoming standard, especially across new energy vehicles.
- Despite seasonal weakness, tight supply and long lead times keep prices for high‑voltage and ADAS‑grade MLCCs relatively firm.
- Hybrid vehicles are gaining strategic importance. LFP batteries dominate the market, with Chinese suppliers increasing share. Japanese and Korean manufacturers face margin pressure and are shifting toward energy storage.
- Chinese leaders dominate global cell shipments. Mid-tier competition is intensifying, with emerging Chinese brands successfully overtaking traditional Korean competitors.
- In Europe, Robotaxi services are advanced through broad local partnerships; Chinese technology vendors are the most aggressive in expanding deployments.
Table of Contents
- Global Automotive Market Scale
- ADAS & ADS (Autonomous Driving)
- Automotive Electronics & Semiconductor
- Electrification
- Business Model and Service Market
<Total Pages: 53>

Spotlight Report
-

2Q26 AI Server Datasheet
2026/06/30
Emerging Technologies
EXCEL
-

Server Market Bulletin - Jul. 9, 2026
2026/07/09
Emerging Technologies
PDF
-

Server Market Bulletin - Aug. 6, 2026
2026/08/06
Emerging Technologies
PDF
-

Server Market Bulletin - Jul. 23, 2026
2026/07/23
Emerging Technologies
PDF
-

Server Market Bulletin - Aug. 20, 2026
2026/08/20
Emerging Technologies
PDF
-

Server Market Bulletin - Sep. 3, 2026
2026/09/03
Emerging Technologies
PDF
Global Automotive Market DecodeRelated Reports



Download Report
8,500

Membership
Spotlight Report
-
2Q26 AI Server Datasheet
2026/06/30
Emerging Technologies
EXCEL
-
Server Market Bulletin - Jul. 9, 2026
2026/07/09
Emerging Technologies
PDF
-
Server Market Bulletin - Aug. 6, 2026
2026/08/06
Emerging Technologies
PDF
-
Server Market Bulletin - Jul. 23, 2026
2026/07/23
Emerging Technologies
PDF
-
Server Market Bulletin - Aug. 20, 2026
2026/08/20
Emerging Technologies
PDF
-
Server Market Bulletin - Sep. 3, 2026
2026/09/03
Emerging Technologies
PDF