


 Download Report
 Contact Us
Unrelenting Memory Price Hikes Drive Front-Loaded Smartphone Demand, Narrowing Annual Decline

Last Modified
2026-08-31

Update Frequency
Aperiodically

Format
Rising memory costs triggered premature purchases as consumers sought to beat price hikes, driving a short-term rebound in smartphone production and prompting TrendForce to revise its full-year output forecast upward. However, this momentum reflects front-loaded demand rather than a genuine market recovery. As persistent cost pressures trickle down to end-user pricing, entry-level models are set to disappear, leaving the market vulnerable to structural contraction risks ahead.
Key Highlights
- Front-Loaded Demand: Memory price hikes sparked anticipatory buying, driving short-term production beat and forecast upgrades, though the overall quarterly weakening trend remains intact.
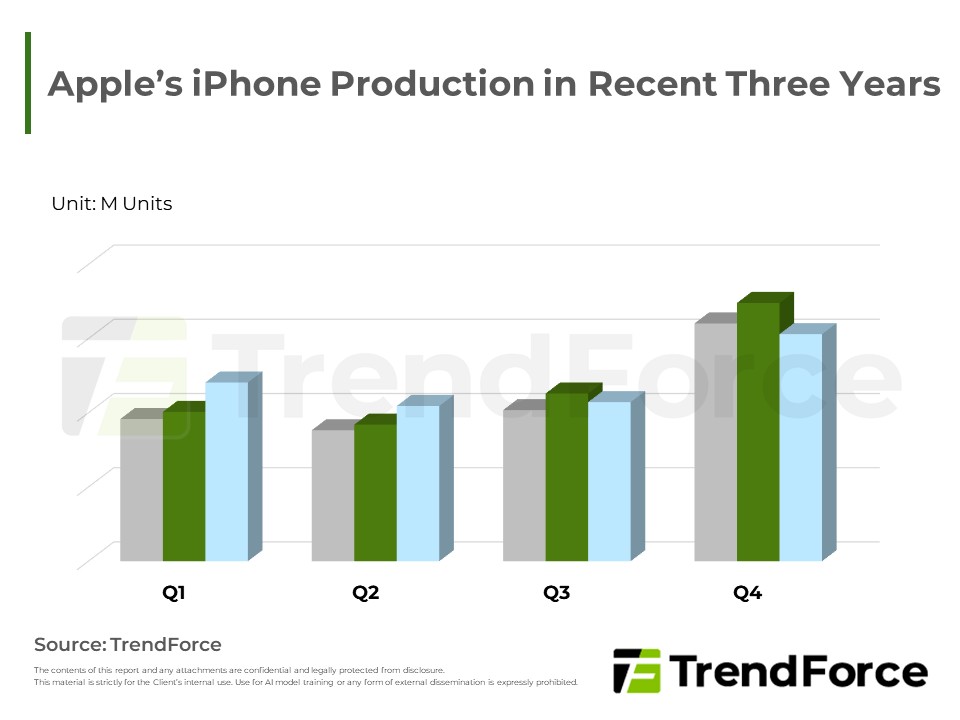
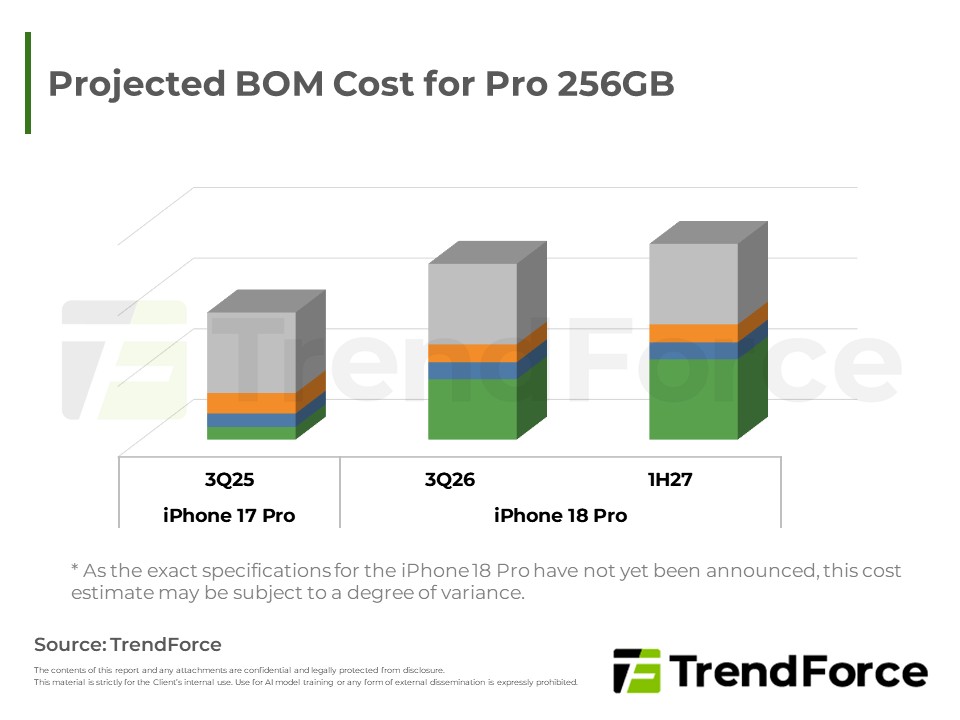
- Divergent Giant Strategies: The Korean leader expands ODM reliance to offset mid-to-low tier costs, while the American tech giant maintains prices to boost early sales, though future advanced chips and high memory costs will force price hikes.
- Chinese Brand Dynamics: Most Chinese vendors adopt conservative, margin-first strategies; entry-level brands suffer heavy inventory pressure from soaring memory costs, whereas one key player gains market share despite chip generation gaps and OS friction.
- Long-Term Downside Risks: Structural price increases will push budget users toward used devices or longer replacement cycles, heightening production risks and structural decline ahead.
Table of Contents
- 2Q26 Smartphone Production Outperformed Expectations; Full-Year Projection Revised Upward to -14.5% YoY
- Global Top Eight Smartphone Brands’ Respective Device Production Volumes for 2Q26
- Samsung and Apple Pursue Divergent Strategies to Retain and Expand Market Share
- Apple’s iPhone Production in Recent Three Years
- Huawei Continues to Expand in Market Share, Whereas Most Chinese Brands Focus on Defending Their Existing Market Shares
- Latest Upward Revision Resulted from Early Demand; Fundamental Pressure May be Worse than Expected in 2027
- Global Smartphone Production Volume
<Total Pages: 6>
Category: DRAM , Smartphones

Spotlight Report
-

DRAM Monthly Datasheet Aug. 2026
2026/08/19
Semiconductors
EXCEL
-

NAND Flash Monthly Datasheet Aug. 2026
2026/08/17
Semiconductors
EXCEL
-

3Q26 Memory Price Forecast
2026/06/30
Semiconductors
PDF
-

Global Memory Supply-Demand Divergence: Analyzing 2027 DRAM Structural Tightness and NAND Flash Oversupply
2026/07/28
Semiconductors
PDF
-

AI Servers Absorbing LPDRAM Capacity, Signaling Tight Supply as the New Norm
2026/06/05
Semiconductors
PDF
-

DRAM Contract Price Jun. 2026
2026/06/30
Semiconductors
PDF
Mobile PackageRelated Reports

Download Report
18,000

Membership
Spotlight Report
-
DRAM Monthly Datasheet Aug. 2026
2026/08/19
Semiconductors
EXCEL
-
NAND Flash Monthly Datasheet Aug. 2026
2026/08/17
Semiconductors
EXCEL
-
3Q26 Memory Price Forecast
2026/06/30
Semiconductors
PDF
-
Global Memory Supply-Demand Divergence: Analyzing 2027 DRAM Structural Tightness and NAND Flash Oversupply
2026/07/28
Semiconductors
PDF
-
AI Servers Absorbing LPDRAM Capacity, Signaling Tight Supply as the New Norm
2026/06/05
Semiconductors
PDF
-
DRAM Contract Price Jun. 2026
2026/06/30
Semiconductors
PDF