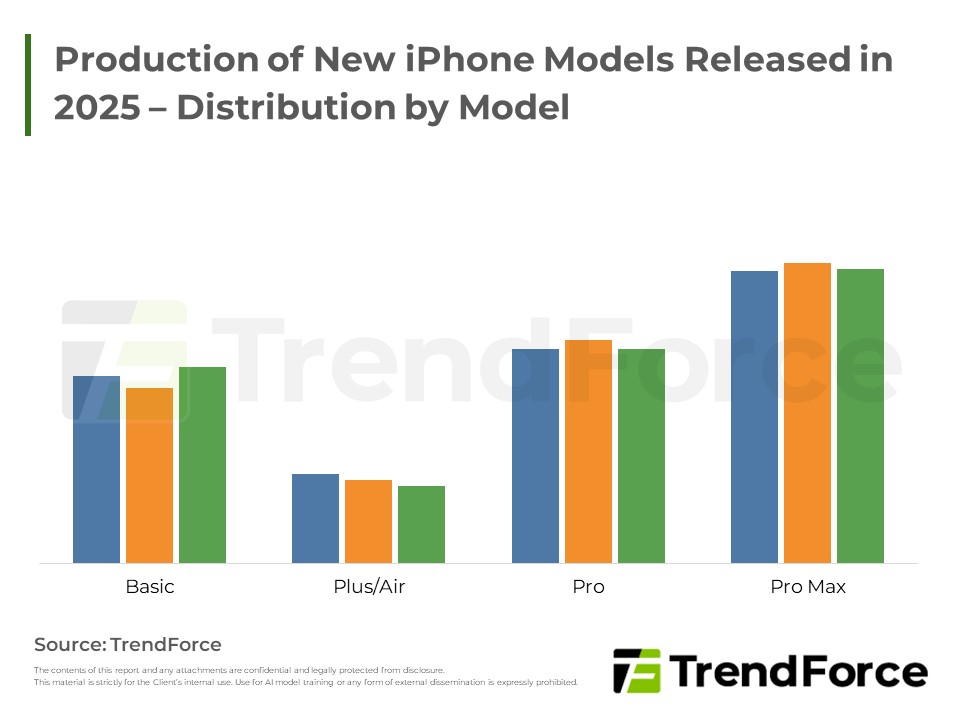
Market consolidation in the smartphone industry will persist in the short term, though brand rankings may shift. Apple is set to gain share on strong new model sales, Xiaomi’s in-house chip advances w...
Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...
NVIDIA Rubin platform plans mid-to-late year packaging and server assembly, with HBM4 sampling, certification and mass production have to be completed beforehand. To counter AMD, NVIDIA raises HBM4 sp...
2Q25 server DRAM revenue increased by 11% QoQ, driven by DDR5 shipments and DDR4 price recovery. CSPs shifted from destocking to restocking, and DDR4, due to strong demand for storage server applicati...
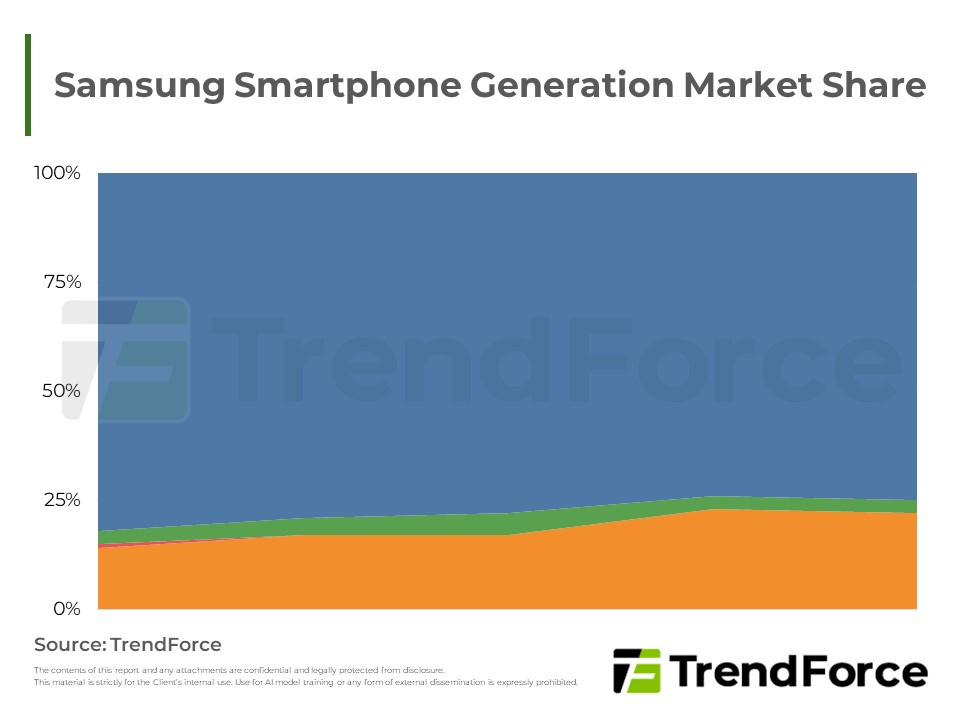
Samsung leads in smartphone market share, but mid-to-low-end shipments decline due to economic factors and competition. In 2026, select flagship models will feature Exynos 2600, segmenting markets. LP...
Micro LED penetration in consumer electronics is accelerating. Following Samsung’s launch of its 140-inch Micro LED TV in 2023, Garmin is set to introduce the Fenix 8 Pro smartwatch with Micro LED in...
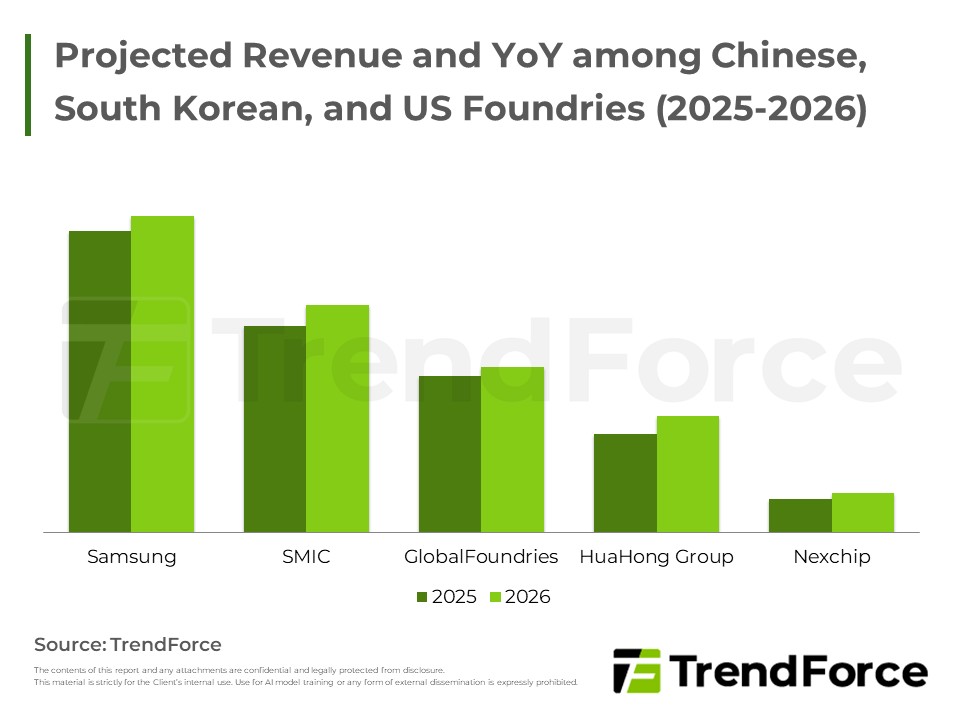
The global foundry landscape is stabilizing, with leading and regional players staying productive; pricing and localization drive growth.
DRAM contract prices are expected to peak by late 2025, then decline as new capacity emerges. DDR4 faces critical long-term shortages. HBM3e prices soften, HBM4 maintains a premium, with Samsung leadi...
Server DRAM prices (DDR4 & DDR5) saw further gains in August 2025, propelled by robust CSP demand and supply issues. Order visibility now extends to Q4, anticipating continued price increases...
In August 2025, SLC and MLC NAND Flash contract prices increased due to niche application demand and supply-side strategies. Telecom and industrial control markets boosted SLC prices, with Samsung&...
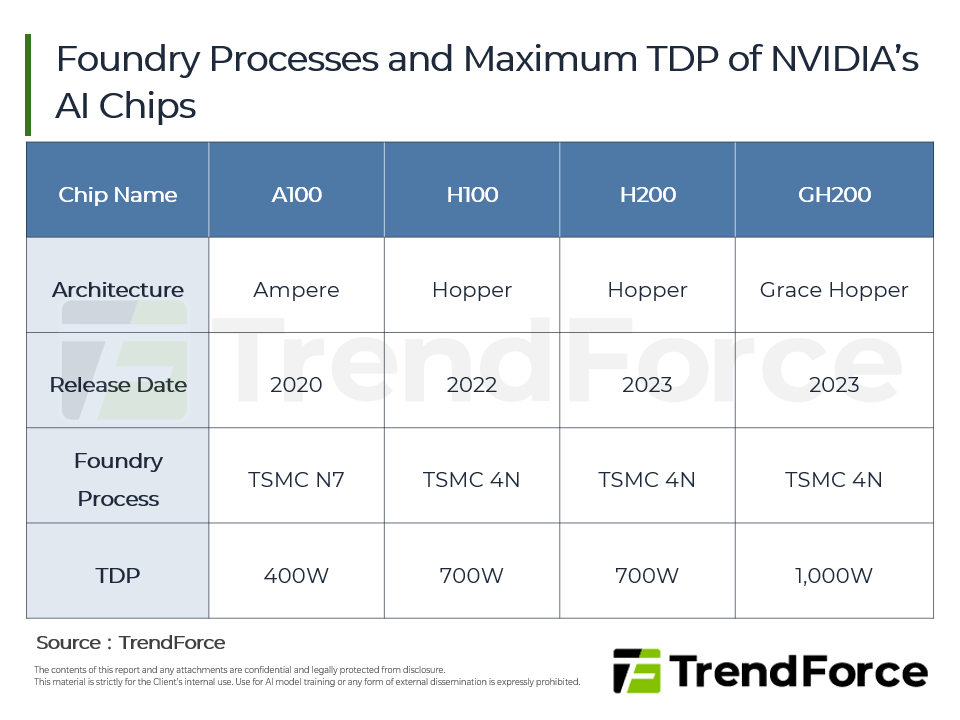
The surge in AI applications has fueled the development and growth of the semiconductor industry but has also brought new challenges. Apart from advanced process technology nearing physical limits and...
TrendForce reports 2Q25 wafer foundry growth driven by subsidies and new product stocking; TSMC leads with strong AI and mobile demand; top 10 firms dominate; 3Q25 outlook remains positive with rising...
The 2Q25 Enterprise SSD market experienced significant growth, driven by robust AI applications and expanding general server deployments. However, severe supply chain challenges, including DDR4 memory...
Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...
In 2Q25, China's subsidies and US tariff stocking drove NAND Flash shipments and revenue. Growth will moderate in 3Q25 as demand normalizes.






