
3Q25 PC DRAM contract prices surged 8-13% quarterly, continuing upward in August. Cloud demand squeezed PC manufacturers'; supply, driving increases. However, a projected 4Q25 PC market slowdown may t...
2Q25 DRAM revenue surged from rising contract prices and robust shipments, especially DDR4. This positive trend is expected to continue into 3Q25, with further price and profit increases.

After sharp increases, DDR4 buyers resisted, slowing its rise and causing spot prices to fall. DDR3, due to capacity shifts and rising demand, became a new price focus. Panic buying eased, suggesting...

Amid rising geopolitical awareness, smartphone brands have gradually diversified production to countries like India and Vietnam in recent years; however, China remains the primary manufacturing hub in...

Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...

DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.

In 2Q25, global smartphone production reached approximately 300 million units, up 4% quarter-over-quarter and 4.8% year-over-year. In terms of market share, Samsung maintained its leading position, be...

3Q25 DRAM contract prices has been set in Aug., DDR5 rising modestly while the shipments increasing. Spot market stays calm, DDR4 is influenced by potential Samsung EOL delay. TrendForce update on CXM...

Contract negotiations see Samsung under pressure, while spot prices hold due to tight supply. Samsung's call highlights HBM3e oversupply and likely price declines. Despite higher mature DRAM prices, S...
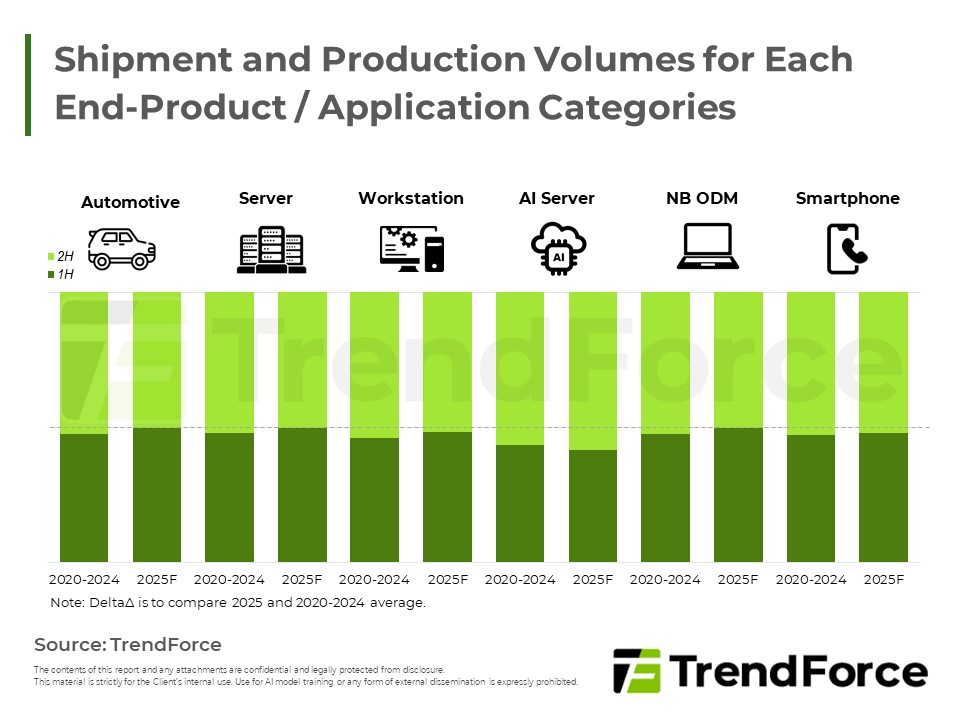
In 2025, the electronics industry sees diverging trends: strong AI demand, weak consumer devices, early pull-in erases seasonality, and future growth slows.

In the second half of 2025, DDR4 faces structural shortages and soaring prices due to limited capacity and robust demand, with supply prioritized for servers. PC and consumer markets struggle with hig...

PC DRAM contract prices rose this quarter, with DDR4 increasing more than DDR5. Tight supply, strong Nanya output, and overall price consolidation are observed, with DDR4 showing higher prices on lowe...

Server module prices rise as CSPs drive demand; DDR4 faces tight supply and price hikes, DDR5 prices lifted by high-capacity modules. However, demand growth is expected to slow in 2026, leading to a p...

DDR4 market remains undersupplied, with low consumer DRAM fulfillment and sharp price hikes; near-term price strength will persist, but further increases will moderate as buyers adjust strategies and...

Driven by both reduced supply and intensified price competition among suppliers, contract prices for LPDDR4X in 3Q25 have seen further significant increases. LPDDR5X prices have also risen, supported...


