


 Download Report
 Contact Us
NAND Flash Market Bulletin - Nov. 18, 2026

Last Modified
2026-11-18

Update Frequency
Weekly

Format
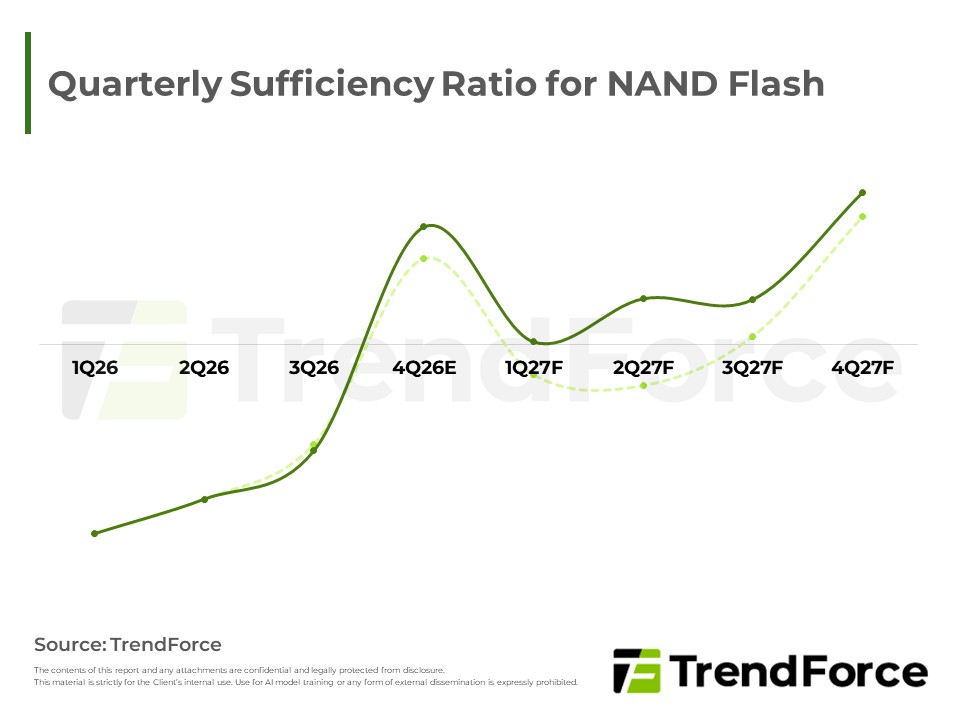
NAND Flash contract price gains are fading, while channel destocking widens the spot-contract gap and weighs on negotiations. TrendForce’s updated model shows Chinese CSP order cuts and consumer spec downgrades, against continued capacity ramps, will tip the market into oversupply next year. Contract price declines now arrive a quarter earlier and deepen each quarter.
Key Highlights
- Contract market: Weaker orders from China and for enterprise SSD have narrowed contract price gains across applications. With soft demand and high inventory, price hikes are unlikely to hold into early next year.
- Spot market: Channel destocking is pushing sellers to cut prices while buying stays weak. The spot-contract gap is widening and dragging on contract talks.
- Demand downgrade: Chinese CSPs are sharply cutting purchases because of GPU shortages, high inventory and stalled AI monetization, which offsets North American CSP growth driven by AI Agents. On the consumer side, higher device prices are suppressing upgrades, and brands are trimming storage specs to control costs.
- Supply growth: New capacity ramps and a rising QLC share keep bit supply and capex growth strong.
- Price outlook: The market turns to oversupply next year, with contract prices falling a quarter earlier than expected and declines deepening each quarter. Watch Chinese CSP inventory digestion, whether brands keep downgrading specs, and the pace of US data center approvals and power buildout.
Table of Contents
- Market Update
- TrendForce’s View
- Quarterly Sufficiency Ratio for NAND Flash
<Total Pages: 2>

Spotlight Report
-

DRAM Monthly Datasheet Nov. 2026
2026/11/16
Semiconductors
EXCEL
-

NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-

4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-

Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-

DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-

DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF
NAND Flash Market BulletinRelated Reports

Download Report
18,000

Membership
Spotlight Report
-
DRAM Monthly Datasheet Nov. 2026
2026/11/16
Semiconductors
EXCEL
-
NAND Flash Monthly Datasheet Nov. 2026
2026/11/13
Semiconductors
EXCEL
-
4Q26 Memory Price Forecast
2026/09/24
Semiconductors
PDF
-
Memory Market Outlook: 2026-2027 DRAM & NAND Revenue and Capex Analysis
2026/10/01
Semiconductors
PDF
-
DRAM Contract Price Aug. 2026
2026/08/31
Semiconductors
PDF
-
DRAM Contract Price Sep. 2026
2026/09/30
Semiconductors
PDF