


 Download Report
 Contact Us
2Q26 Revenue Ranking among NAND Flash Suppliers

Last Modified
2026-08-14

Update Frequency
Quarterly

Format
Driven by surge in AI server demand, enterprise SSD shortages have catapulted average selling prices and gross margins to record highs, pushing the sector into a supercycle. Despite weakening consumer end-market demand and constrained capacity expansion caused by capital expenditure shifting toward DRAM/ HBM, supply imbalances are expected to sustain price momentum into the next quarter while accelerating high-capacity storage adoption.
Key Highlights
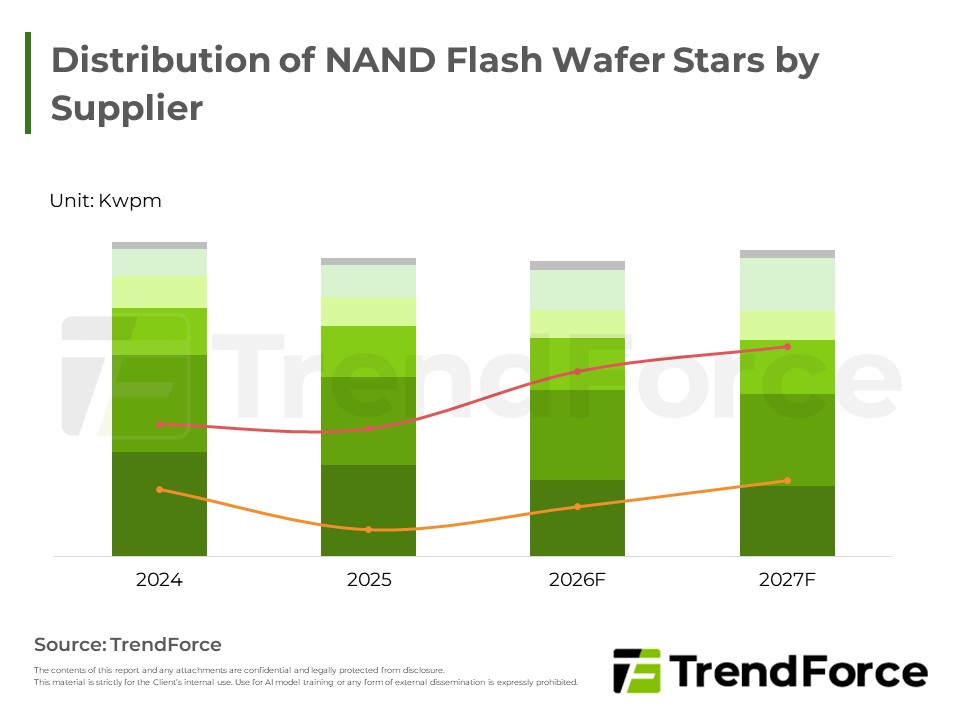
- Record Demand & Revenue: Strong AI server demand drove an enterprise SSD shortage, enhancing supplier pricing power. Sharply increased average selling prices propelled industry revenue and gross margins to historical highs.
- Supply Constraints: Capital expenditures prioritised for DRAM and HBM resulted in limited flash capacity additions, providing solid support for sustained price strength.
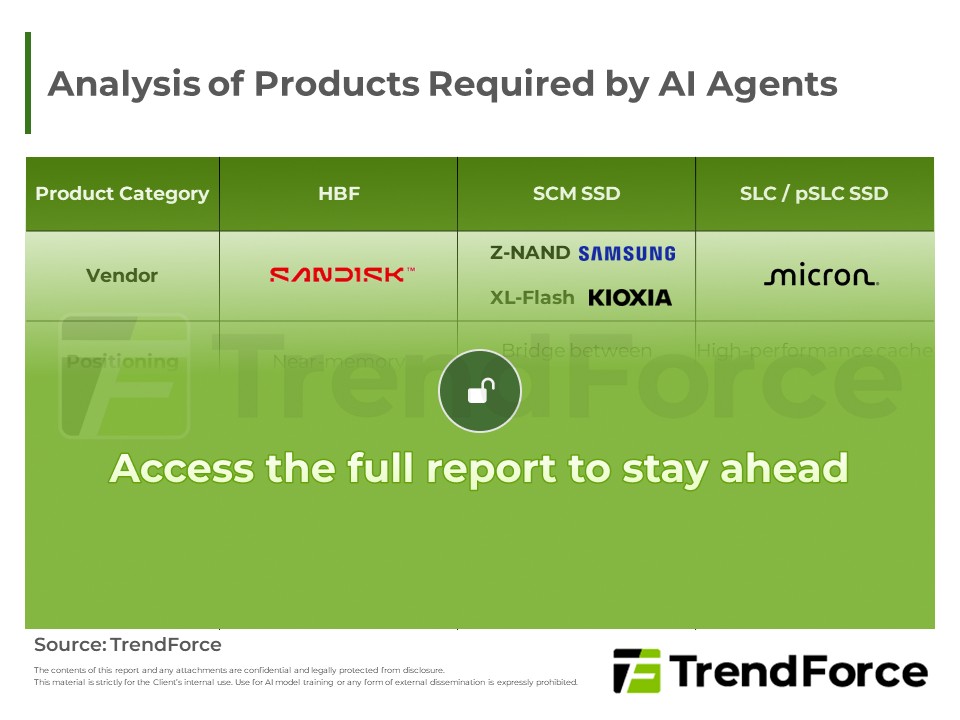
- Supplier Dynamics: Samsung maintained its leadership position. SK Hynix Group leveraged advanced stack processes and high-capacity solutions to boost profitability. Micron jumped to third in market share, while Kioxia and SanDisk accelerated product validation and portfolio optimization.
- Technology Trends & Outlook: Adoption of advanced multi-layer stacking and ultra-high-capacity enterprise SSDs will accelerate. The industry continues to shift toward AI server applications with strong revenue momentum expected into the third quarter.
Table of Contents
- With AI Demand Driving a Surge in ASPs, NAND Flash Industry’s Revenue Rose by 83.6% QoQ to Hit a New Record High in 2Q26
- Suppliers’ 2Q26 Revenue Performances and Outlooks
- Summary and Technical Trends for 2Q26
- 2Q26 Revenue Ranking among NAND Flash Suppliers
<Total Pages: 5>

Category: NAND Flash

Spotlight Report
-

DRAM Monthly Datasheet Aug. 2026
2026/08/19
Semiconductors
EXCEL
-

NAND Flash Monthly Datasheet Aug. 2026
2026/08/17
Semiconductors
EXCEL
-

3Q26 Memory Price Forecast
2026/06/30
Semiconductors
PDF
-

Global Memory Supply-Demand Divergence: Analyzing 2027 DRAM Structural Tightness and NAND Flash Oversupply
2026/07/28
Semiconductors
PDF
-

AI Servers Absorbing LPDRAM Capacity, Signaling Tight Supply as the New Norm
2026/06/05
Semiconductors
PDF
-

DRAM Contract Price Jun. 2026
2026/06/30
Semiconductors
PDF
NAND Flash PlatinumRelated Reports

Download Report
18,000

Membership
Spotlight Report
-
DRAM Monthly Datasheet Aug. 2026
2026/08/19
Semiconductors
EXCEL
-
NAND Flash Monthly Datasheet Aug. 2026
2026/08/17
Semiconductors
EXCEL
-
3Q26 Memory Price Forecast
2026/06/30
Semiconductors
PDF
-
Global Memory Supply-Demand Divergence: Analyzing 2027 DRAM Structural Tightness and NAND Flash Oversupply
2026/07/28
Semiconductors
PDF
-
AI Servers Absorbing LPDRAM Capacity, Signaling Tight Supply as the New Norm
2026/06/05
Semiconductors
PDF
-
DRAM Contract Price Jun. 2026
2026/06/30
Semiconductors
PDF