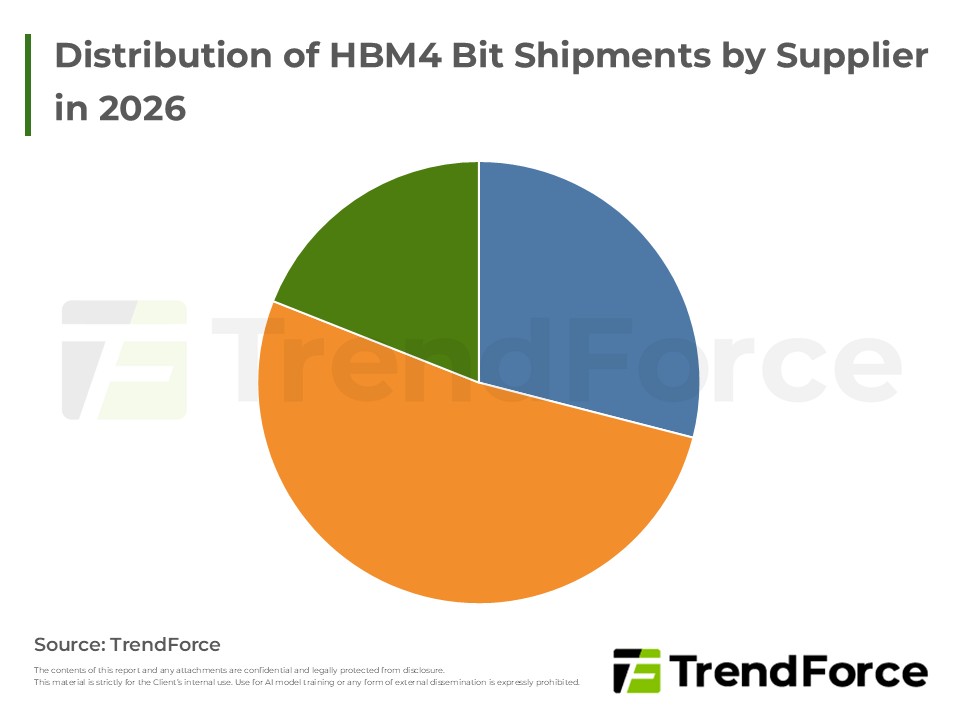
NVIDIA's upgraded HBM4 specifications have delayed supplier validations. Samsung, leading in chip performance, is poised to complete certification first and increase market share, while competitors re...
Propelled by surging contract prices, Mobile DRAM revenue broke the $10 billion mark in 4Q25, a quarterly jump of over 30%. Entering the off-peak 1Q26, while bit demand is expected to contract, the si...
Driven by the proliferation of inference applications and the recovery in general server demand, the market is undergoing a structural transformation. Demand for high-capacity storage solutions is exh...
AI infrastructure expansion is driving an explosion in enterprise storage demand. With manufacturers prioritizing DRAM and HBM, the market faces a persistent supply deficit. The industry is transition...
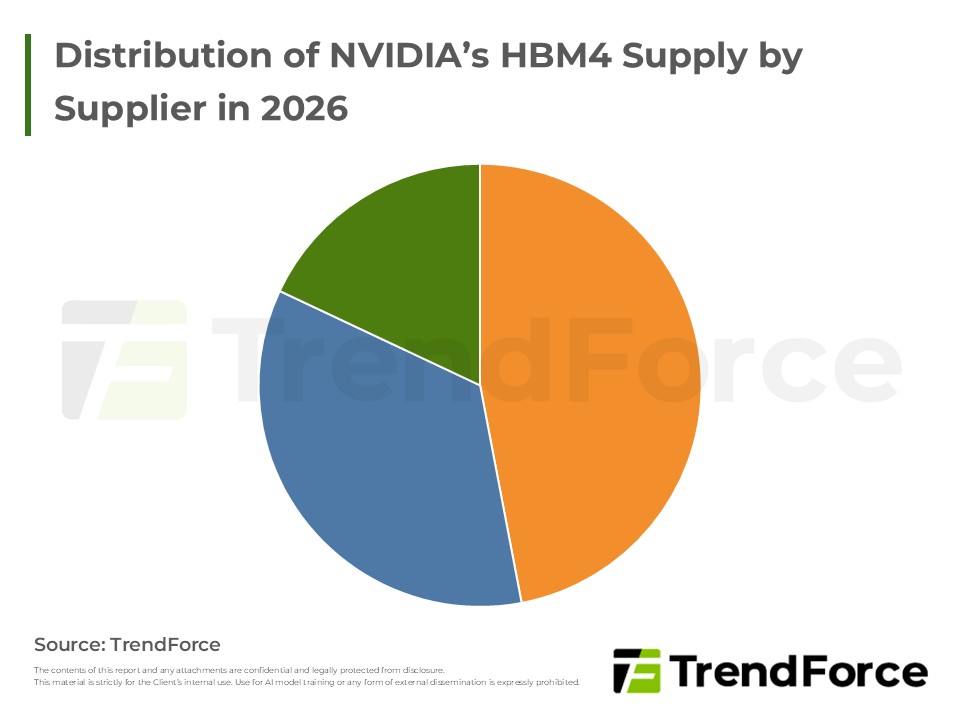
Samsung currently leads HBM4 validation due to process improvements enhancing stability. SK hynix retains volume leadership despite re-sampling, while Micron trails slightly. Given robust AI demand an...
DRAM industry will focus on HBM capacity expansion, with Chinese suppliers limited by equipment restrictions; major players like Samsung, SK hynix, and Micron emphasize tech migration and AI applicati...
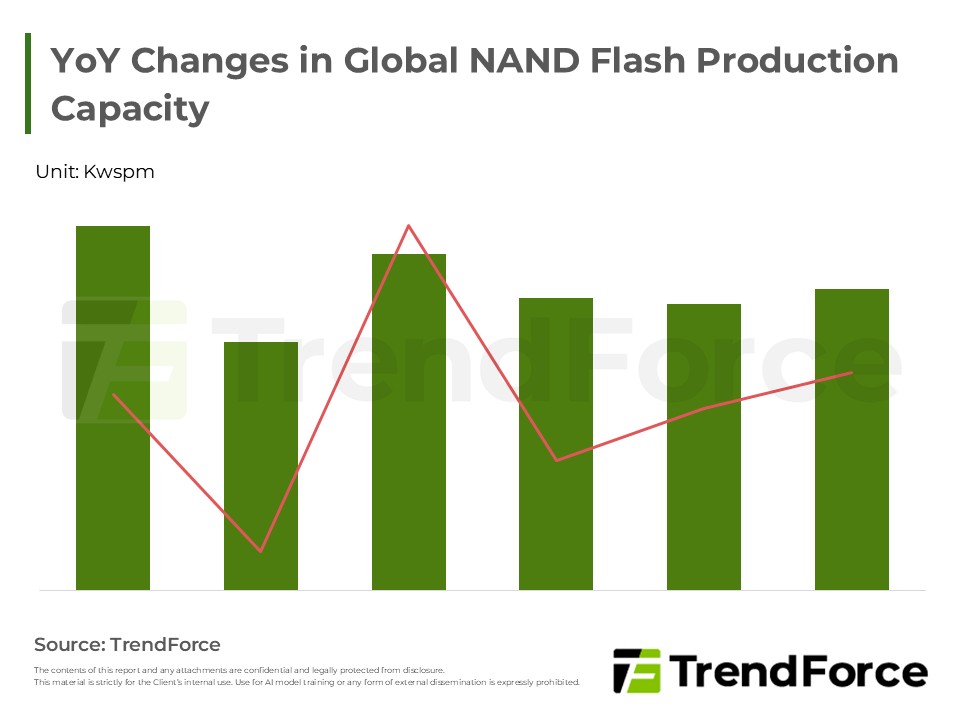
AI shifting to inference drives a surge in enterprise SSD demand. With new fab capacity delayed by cleanroom construction, supply remains tight through the next two years. Top vendors focus on node up...
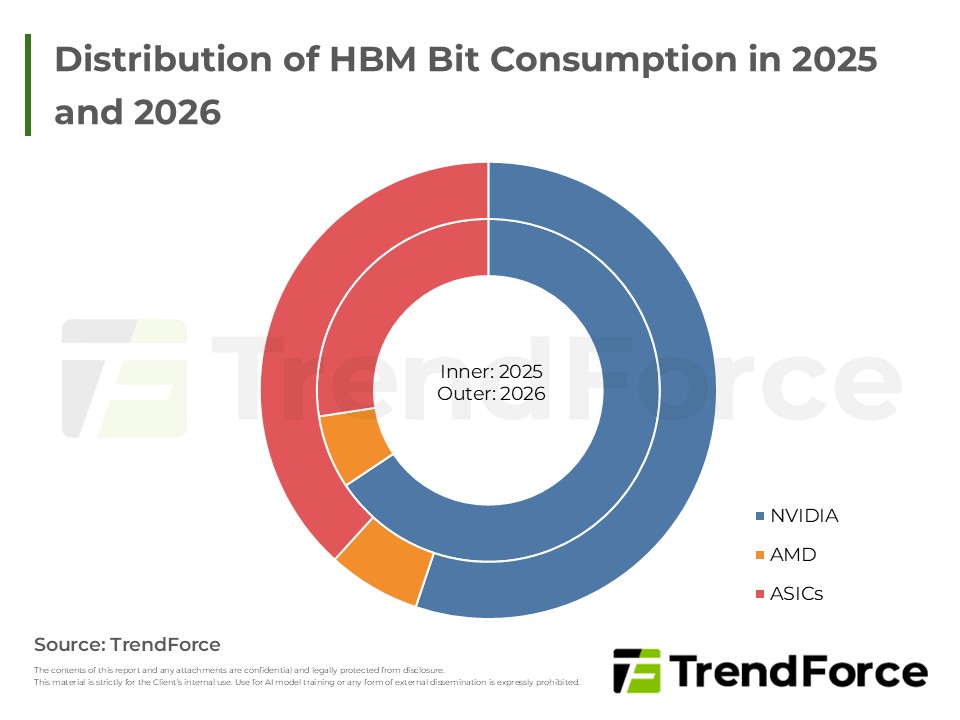
In 2026, the HBM market continues to grow, with SK hynix maintaining its lead and Samsung recovering significantly via HBM3e and HBM4 contributions. Micron also expands aggressively. While HBM3e domin...
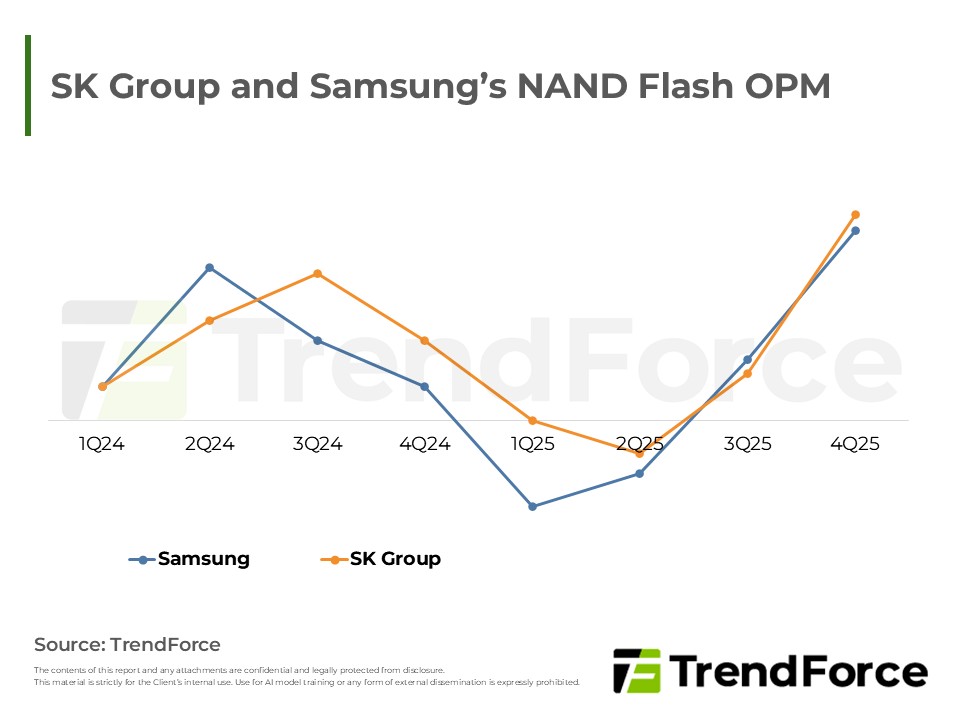
Supply constraints favor sellers with rising contract prices, though high costs dampen spot trading. Earnings confirm AI enterprise SSDs are driving profits. Future strategies prioritize technology up...
While most smartphone brands have not yet officially initiated price negotiations for 1Q26 mobile DRAM, market signals indicate that the upward trend will persist this quarter, with momentum exceeding...
Raised specs delayed HBM4 production, keeping HBM3e dominant. Samsung leads verification with advanced tech, while SK hynix retains the top share.
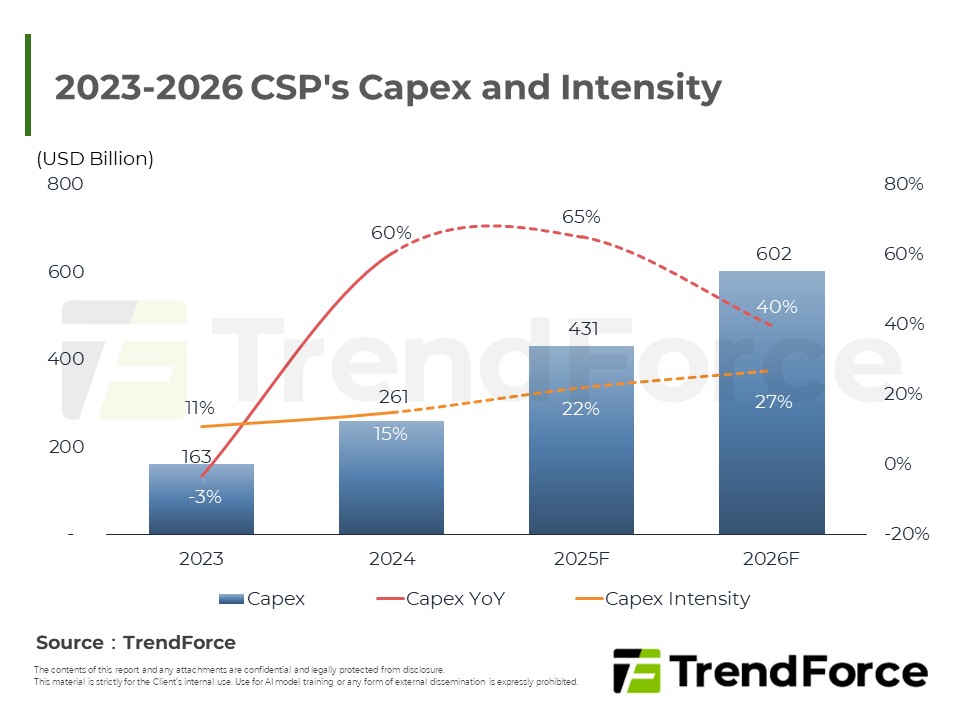
North American CSPs' expanded investment in AI and general servers has confirmed a DRAM industry upcycle. With supplier inventory bottoming out and buyers actively restocking, prices and revenue...
Revenue of mobile DRAM was driven by the increase of contract prices in 3Q25, and accomplished a QoQ growth of nearly 30% in market value. Revenue is looking to continue ascending in 4Q25 after anothe...
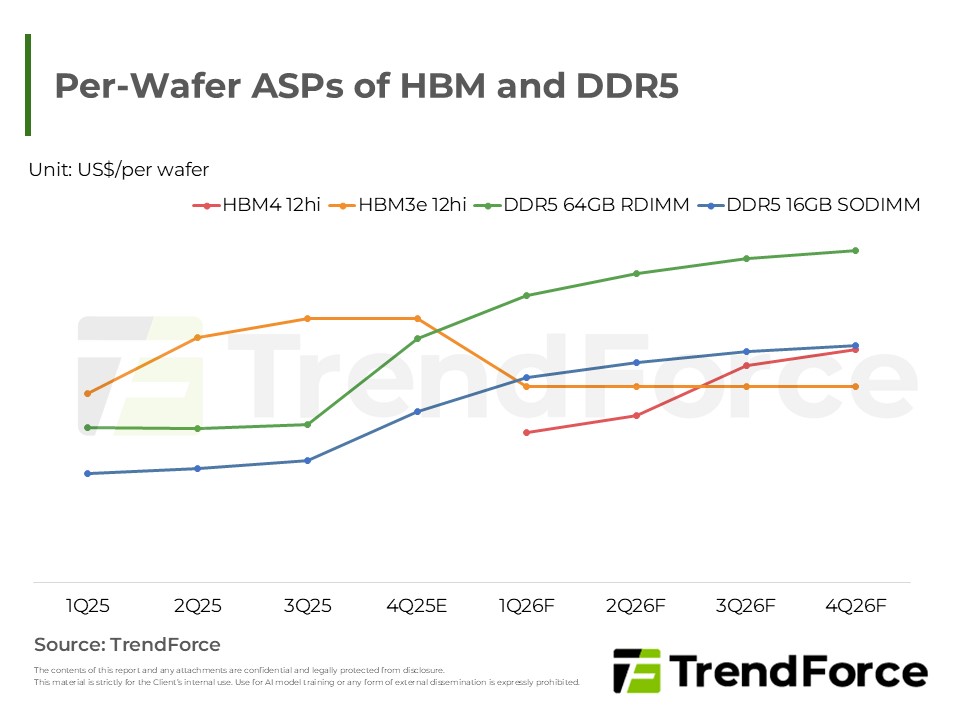
TrendForce shows AI-driven DRAM demand surge, creating supply tension. Samsung, SK hynix, and Micron plan to expand DRAM production through 2026.
3Q25 DRAM market achieved strong price and volume growth, fueled by cloud demand and HBM. Low inventories forecast significant price acceleration in 4Q25, boosting manufacturers' profitability.






