4Q25 mobile DRAM contract prices have risen sharply due to tight supply-demand and competitive bidding among chipmakers, with smartphone applications seeing particularly large increases. This upward t...
CXMT, through capacity expansions, yield improvement, and related policies, has emerged swiftly in the LPDDR4X market. Its production capacity has helped replenished the supply void left behind by maj...
Sep consumer DRAM contract price growth slowed. Looking ahead, strong CSP server demand displaces capacity, pushing 4Q25 consumer DRAM to double-digit hikes, with the rally extending into 1H26.
Sept 2025 server DRAM contract prices surged due to persistent CSP demand, with DDR5/DDR4 increasing. 8000MT/s modules will see accelerated adoption. Strong 2026 demand and tight supply are set to ext...
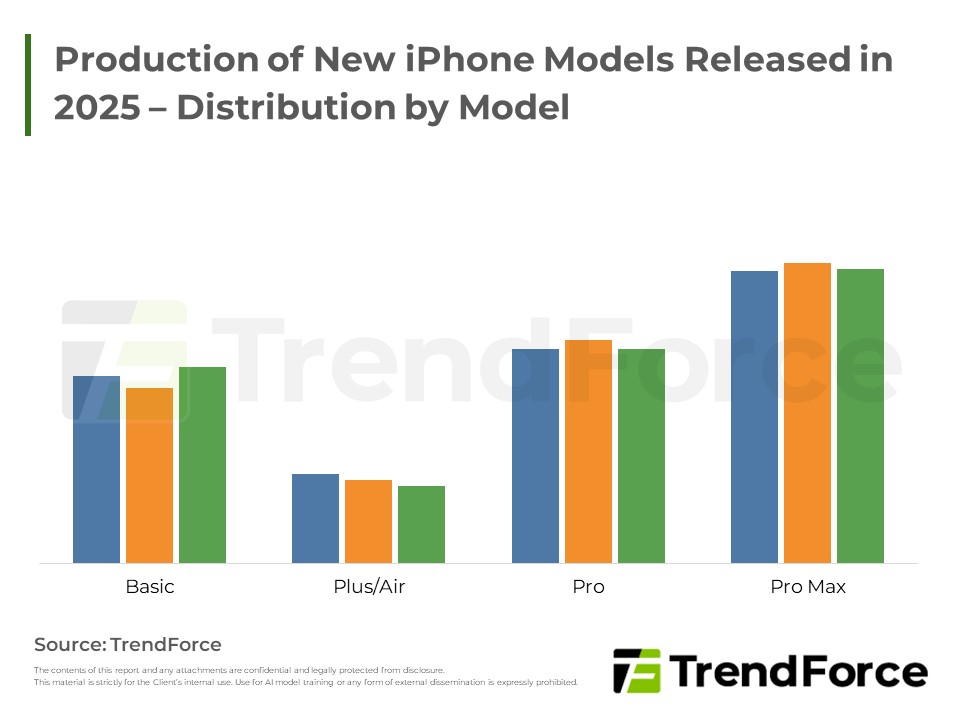
Market consolidation in the smartphone industry will persist in the short term, though brand rankings may shift. Apple is set to gain share on strong new model sales, Xiaomi’s in-house chip advances w...
Tight DRAM supply fuels rising contract/spot prices. Low supplier inventory driven by strong US CSP demand. Client stock levels vary, but continued price hikes are expected.
AI demand boosts storage; HDD scarcity shifts orders to enterprise SSDs, strengthening NAND Flash market sentiment. Supplier inventories are healthy, projecting widespread 4Q25 contract and spot price...
Analyst summary: Samsung completed NVIDIA certification for HBM3e and began limited shipments; HBM3e will be the near‑term mainstream. Supplier competition is intensifying while HBM4 upgrades are expe...
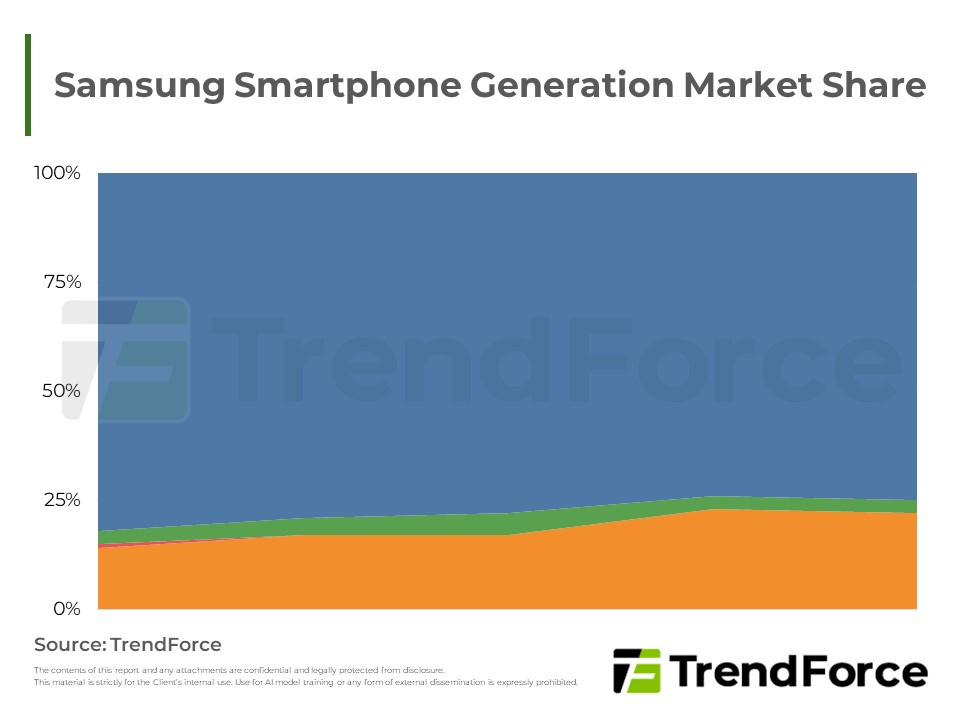
Samsung leads in smartphone market share, but mid-to-low-end shipments decline due to economic factors and competition. In 2026, select flagship models will feature Exynos 2600, segmenting markets. LP...
4Q25 Server and Smartphone DRAM contract prices are rising. TrendForce will upgrade 2026 server and DRAM demand forecasts due to AI expansion and sovereign AI, anticipating higher bit growth and narro...
In 2Q25, global smartphone production saw a slight increase due to seasonal demand and inventory adjustments. Production estimates for 2025 and 2026 suggest steady growth. Mobile DRAM revenue was driv...
2Q25 DRAM revenue grew notably from price and shipment increases. 3Q25 momentum is expected to continue, with accelerating price hikes. US CSPs show robust demand but slightly elevated inventory. Smar...
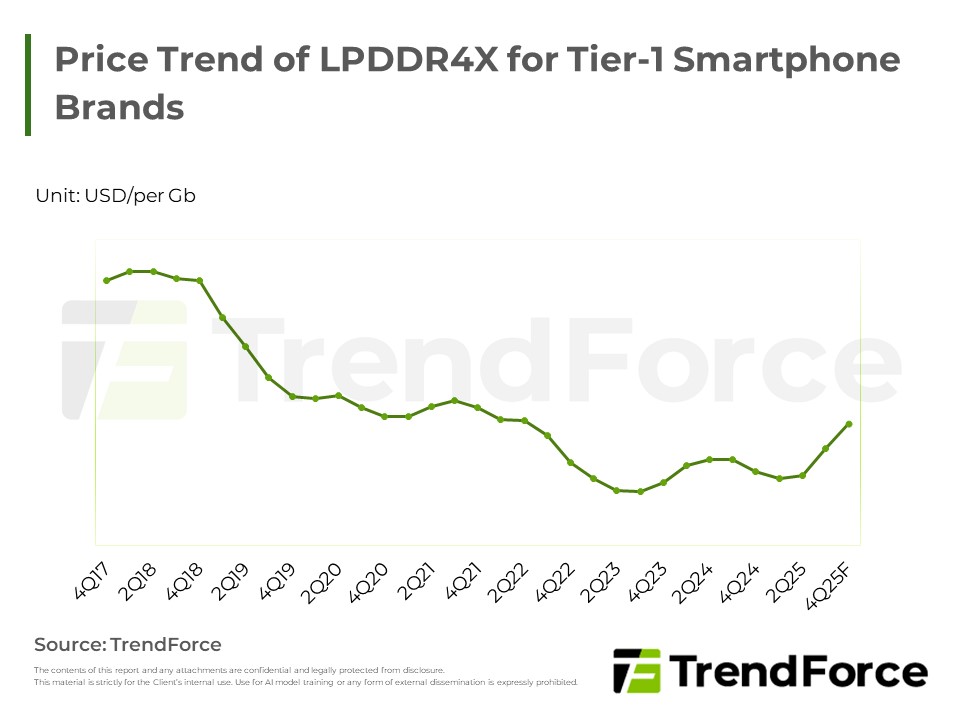
Amid rising geopolitical awareness, smartphone brands have gradually diversified production to countries like India and Vietnam in recent years; however, China remains the primary manufacturing hub in...
Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...
DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.






