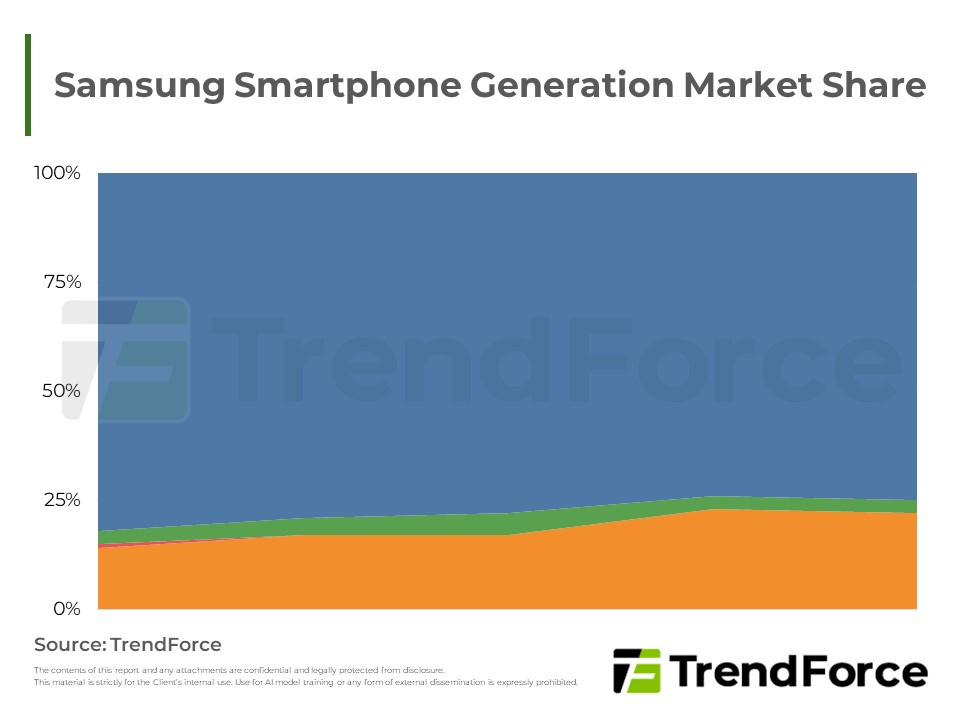
Samsung leads in smartphone market share, but mid-to-low-end shipments decline due to economic factors and competition. In 2026, select flagship models will feature Exynos 2600, segmenting markets. LP...
4Q25 Server and Smartphone DRAM contract prices are rising. TrendForce will upgrade 2026 server and DRAM demand forecasts due to AI expansion and sovereign AI, anticipating higher bit growth and narro...
In 2Q25, global smartphone production saw a slight increase due to seasonal demand and inventory adjustments. Production estimates for 2025 and 2026 suggest steady growth. Mobile DRAM revenue was driv...
2Q25 DRAM revenue grew notably from price and shipment increases. 3Q25 momentum is expected to continue, with accelerating price hikes. US CSPs show robust demand but slightly elevated inventory. Smar...
DRAM contract prices are expected to peak by late 2025, then decline as new capacity emerges. DDR4 faces critical long-term shortages. HBM3e prices soften, HBM4 maintains a premium, with Samsung leadi...
Server DRAM prices (DDR4 & DDR5) saw further gains in August 2025, propelled by robust CSP demand and supply issues. Order visibility now extends to Q4, anticipating continued price increases...
3Q25 PC DRAM contract prices surged 8-13% quarterly, continuing upward in August. Cloud demand squeezed PC manufacturers'; supply, driving increases. However, a projected 4Q25 PC market slowdown may t...
2Q25 DRAM revenue surged from rising contract prices and robust shipments, especially DDR4. This positive trend is expected to continue into 3Q25, with further price and profit increases.
After sharp increases, DDR4 buyers resisted, slowing its rise and causing spot prices to fall. DDR3, due to capacity shifts and rising demand, became a new price focus. Panic buying eased, suggesting...
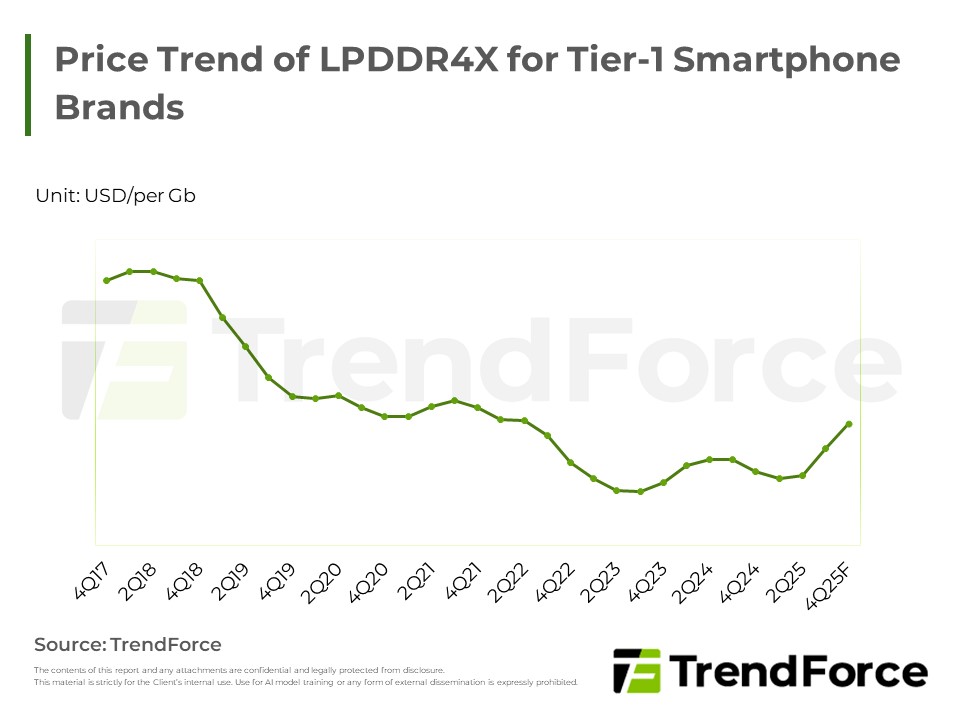
Amid rising geopolitical awareness, smartphone brands have gradually diversified production to countries like India and Vietnam in recent years; however, China remains the primary manufacturing hub in...
Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...
DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.
In 2Q25, global smartphone production reached approximately 300 million units, up 4% quarter-over-quarter and 4.8% year-over-year. In terms of market share, Samsung maintained its leading position, be...
3Q25 DRAM contract prices has been set in Aug., DDR5 rising modestly while the shipments increasing. Spot market stays calm, DDR4 is influenced by potential Samsung EOL delay. TrendForce update on CXM...
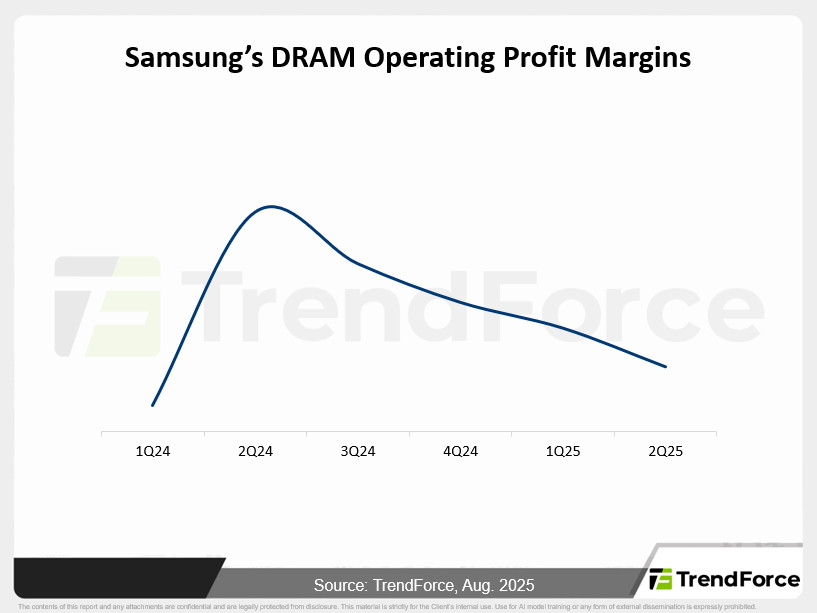
Contract negotiations see Samsung under pressure, while spot prices hold due to tight supply. Samsung's call highlights HBM3e oversupply and likely price declines. Despite higher mature DRAM prices, S...






