4Q25 Server and Smartphone DRAM contract prices are rising. TrendForce will upgrade 2026 server and DRAM demand forecasts due to AI expansion and sovereign AI, anticipating higher bit growth and narro...
Nearline HDD shortages are driving QLC SSD demand. Suppliers foresee tight supply and rising NAND contract prices next year, despite spot market resistance. AI-driven data center needs make QLC SSD a...
In 2Q25, global smartphone production saw a slight increase due to seasonal demand and inventory adjustments. Production estimates for 2025 and 2026 suggest steady growth. Mobile DRAM revenue was driv...
2Q25 DRAM revenue grew notably from price and shipment increases. 3Q25 momentum is expected to continue, with accelerating price hikes. US CSPs show robust demand but slightly elevated inventory. Smar...
DRAM contract prices are expected to peak by late 2025, then decline as new capacity emerges. DDR4 faces critical long-term shortages. HBM3e prices soften, HBM4 maintains a premium, with Samsung leadi...
Strong 4Q25 enterprise SSD demand boosts prices. Yet, 1H26 NAND Flash faces server platform shifts, weak smartphone demand, and supply expansion, dimming its outlook.
In 2Q25, NAND Flash saw client SSD prices rise from tariff-driven PC pre-stocking, with moderate overall ASP growth. 3Q25 shifts to AI/server-led enterprise SSD demand, creating controller IC shortage...
Server DRAM prices (DDR4 & DDR5) saw further gains in August 2025, propelled by robust CSP demand and supply issues. Order visibility now extends to Q4, anticipating continued price increases...
3Q25 PC DRAM contract prices surged 8-13% quarterly, continuing upward in August. Cloud demand squeezed PC manufacturers'; supply, driving increases. However, a projected 4Q25 PC market slowdown may t...
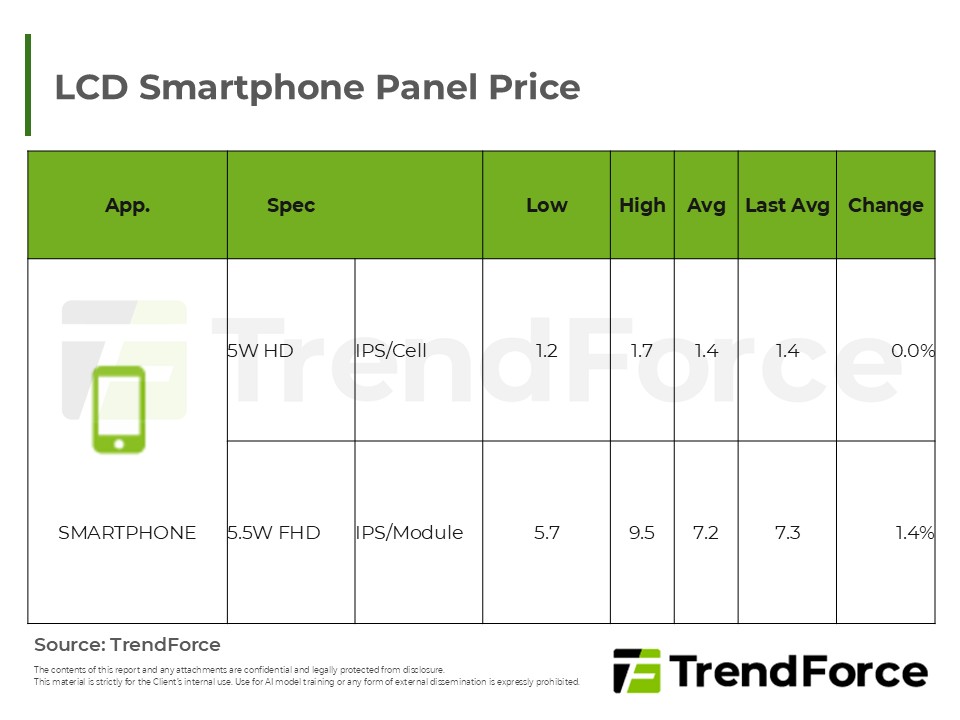
This report will show surveys of the mainstream smartphone panel sizes' quote prices, which will be categorized by including different resolutions, specifications, modules or product form...
2Q25 DRAM revenue surged from rising contract prices and robust shipments, especially DDR4. This positive trend is expected to continue into 3Q25, with further price and profit increases.
After sharp increases, DDR4 buyers resisted, slowing its rise and causing spot prices to fall. DDR3, due to capacity shifts and rising demand, became a new price focus. Panic buying eased, suggesting...
Supply strong, demand weak, August NAND Flash Wafer prices continue rising but with smaller increases. Demand focuses on depleting inventory, September market predicted stagnant, 3Q25-end prices expec...
In August 2025, SLC and MLC NAND Flash contract prices increased due to niche application demand and supply-side strategies. Telecom and industrial control markets boosted SLC prices, with Samsung&...
The 2Q25 Enterprise SSD market experienced significant growth, driven by robust AI applications and expanding general server deployments. However, severe supply chain challenges, including DDR4 memory...






