While most smartphone brands have not yet officially initiated price negotiations for 1Q26 mobile DRAM, market signals indicate that the upward trend will persist this quarter, with momentum exceeding...
Contract price forecasts were raised sharply, led by PC DRAM, with further upside potential. High spot costs stalled advanced chip trading, shifting demand to mature products. CXMT is accelerating pro...
Driven by policy, Chinese firms accelerate HBM development to support domestic AI chips. CXMT targets advanced nodes while JHICC focuses on mature processes. Both face technical hurdles and are in ear...
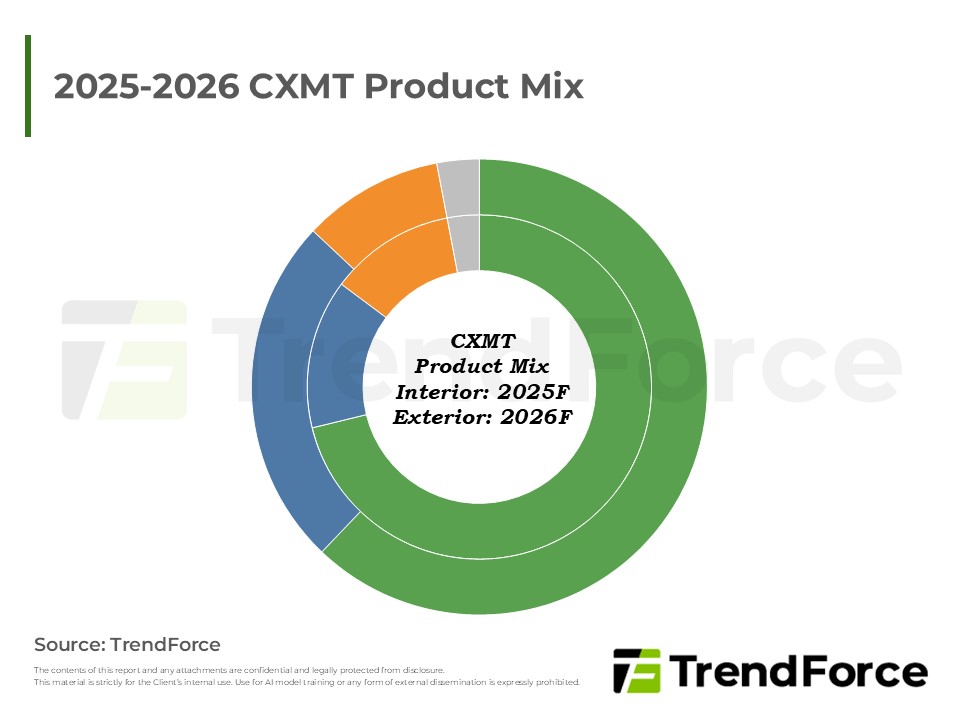
Looking to early next year, contract prices are projected to rise significantly due to low inventory and strong supplier leverage, with spot prices remaining high. While CXMT's capacity expansion...
Revenue of mobile DRAM was driven by the increase of contract prices in 3Q25, and accomplished a QoQ growth of nearly 30% in market value. Revenue is looking to continue ascending in 4Q25 after anothe...
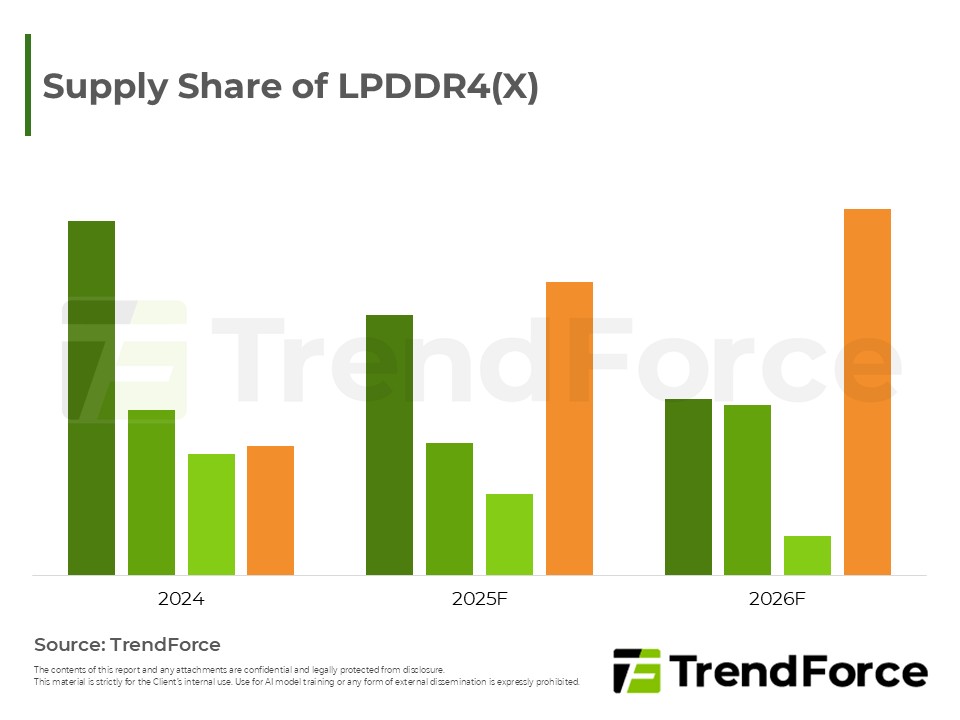
CXMT, through expansions and yield improvement, has once again taken the crown for YoY growth of output bit for 2026. The supplier’s major product, mobile DRAM, highly corresponds to DRAM products req...
4Q25 mobile DRAM contract prices have risen sharply due to tight supply-demand and competitive bidding among chipmakers, with smartphone applications seeing particularly large increases. This upward t...
CXMT, through capacity expansions, yield improvement, and related policies, has emerged swiftly in the LPDDR4X market. Its production capacity has helped replenished the supply void left behind by maj...
The 6th to 10th spots of global smartphone ranking for 2025 are occupied by Transsion, Honor, Lenovo, Huawei, and Google in sequential order. Among which, Transsion has slightly dropped in share due t...
Robust AI server demand, driven by NVIDIA, AMD, and CSP custom ASICs, propels market growth. DDR5 is mainstream, yet DDR4 sees extended life and price rebound from storage needs. AMD and ARM challenge...
2Q25 server DRAM revenue increased by 11% QoQ, driven by DDR5 shipments and DDR4 price recovery. CSPs shifted from destocking to restocking, and DDR4, due to strong demand for storage server applicati...
Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...
3Q25 DRAM contract prices has been set in Aug., DDR5 rising modestly while the shipments increasing. Spot market stays calm, DDR4 is influenced by potential Samsung EOL delay. TrendForce update on CXM...
Driven by both reduced supply and intensified price competition among suppliers, contract prices for LPDDR4X in 3Q25 have seen further significant increases. LPDDR5X prices have also risen, supported...

DRAM contract prices keep rising. DDR5 and LPDDR5x remain stable, but DDR4 jumps amid supply strain and may stabilize. CXMT expands capacity, but future progress hinges on equipment and policy.






