Benefiting from a low base effect, as well as simultaneous increases in shipment volume and pricing, the 2Q25 Mobile DRAM market delivered an outstanding revenue performance. In terms of market share,...
In 2Q25, China's subsidies and US tariff stocking drove NAND Flash shipments and revenue. Growth will moderate in 3Q25 as demand normalizes.
TrendForce provide weekly spot prices for key photovoltaic components by conducting cross-investigations with major suppliers and buyers in the photovoltaic industry supply chain. We use historical co...
DRAM contract prices rise in late August, spot market slows, suppliers’ inventory down, and market dynamics diverge by segment.
NAND Flash contract prices remain stable with weak spot demand. Suppliers keep healthy inventory; PC and smartphone brands hold low stocks. Module house inventory steady, while hyperscalers increased...
The 2026 HBM3e market faces oversupply with Samsung likely ramping up HBM3e capacity causing price declines; HBM4 sees premium pricing amid fierce competition and concentrated NVIDIA supply.
In 2Q25, global smartphone production reached approximately 300 million units, up 4% quarter-over-quarter and 4.8% year-over-year. In terms of market share, Samsung maintained its leading position, be...
In the third quarter, enterprise SSD demand is strong, supporting NAND Flash capacity, while the smartphone and PC markets are weak. YMTC expands capacity and improves yield rates, increasing market s...
3Q25 DRAM contract prices has been set in Aug., DDR5 rising modestly while the shipments increasing. Spot market stays calm, DDR4 is influenced by potential Samsung EOL delay. TrendForce update on CXM...
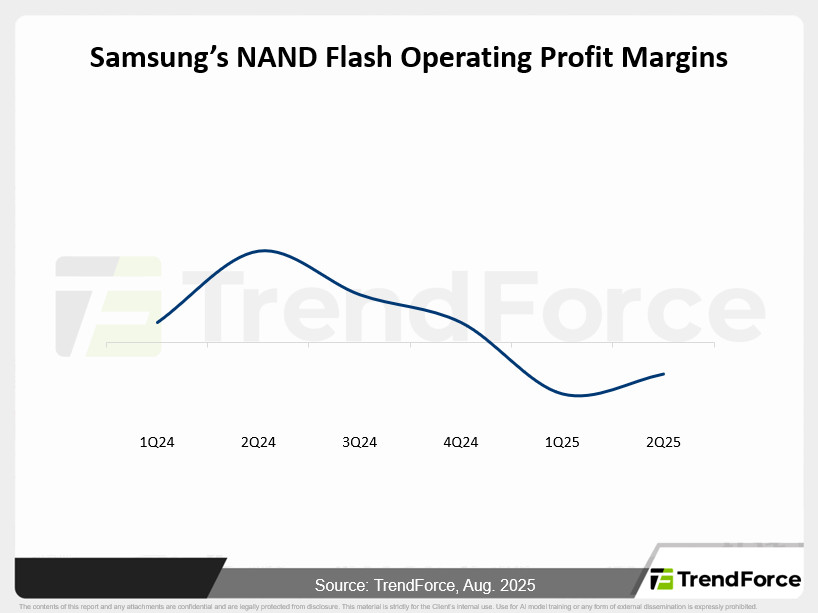
Samsung advances high-value NAND Flash technology amid rising AI and data center demand. Enterprise SSD growth boosts inventory digestion, yet overall NAND market recovery remains limited due to econo...
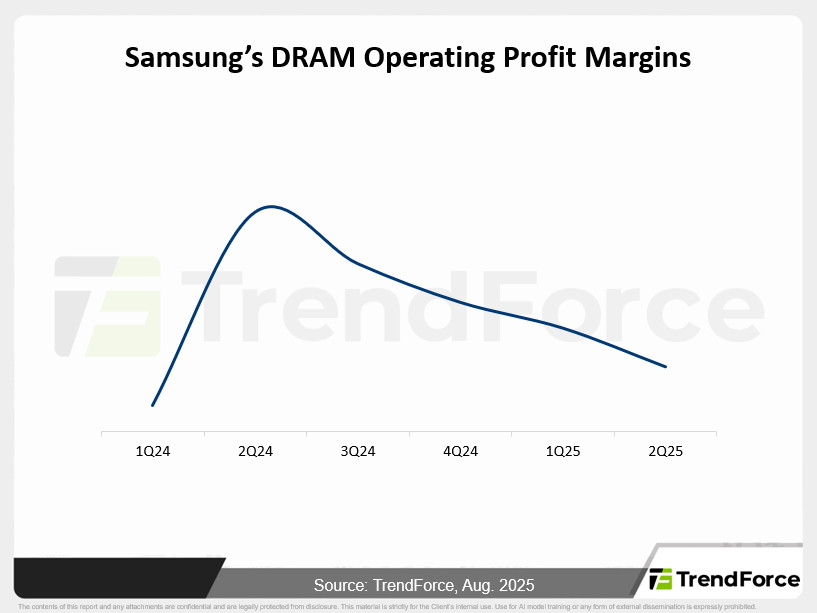
Contract negotiations see Samsung under pressure, while spot prices hold due to tight supply. Samsung's call highlights HBM3e oversupply and likely price declines. Despite higher mature DRAM prices, S...
In the second half of 2025, DDR4 faces structural shortages and soaring prices due to limited capacity and robust demand, with supply prioritized for servers. PC and consumer markets struggle with hig...
Strong demand for AI and general server orders is driving up enterprise SSD prices. The aggressive procurement and rise of self-built SSD strategies by North American and Chinese CSPs are likely to li...
PC DRAM contract prices rose this quarter, with DDR4 increasing more than DDR5. Tight supply, strong Nanya output, and overall price consolidation are observed, with DDR4 showing higher prices on lowe...
DDR4 market remains undersupplied, with low consumer DRAM fulfillment and sharp price hikes; near-term price strength will persist, but further increases will moderate as buyers adjust strategies and...






